
Breaking Down the Numbers
The first question isn’t how much a million dollars buys, but how much it costs to keep. A million dollars isn’t an annual income; it’s a snapshot. If you’re spending $100,000 a year, that million will last a decade. If you’re spending $200,000, it’s gone in five. The math is brutal, but it’s also flexible. The key variables are taxes, location, and liquidity. In the U.S., federal capital gains taxes alone can eat 15–20% of your gains if you sell assets. State taxes add another layer—California’s top rate is nearly 14%, while Texas takes nothing. Then there’s the opportunity cost: a million dollars sitting in cash loses purchasing power to inflation at roughly 3% annually. Over a decade, that’s $300,000 in lost value. What is a million dollars look like after taxes and fees? Often far less than the headline suggests. The second layer is what you can actually buy. A million dollars in cash can purchase a modest home in many U.S. markets, but in cities like New York or Los Angeles, that same sum might get you a studio or a fixer-upper in a less desirable neighborhood. If you’re investing, a million dollars can generate $40,000–$60,000 a year in passive income—if the market cooperates. But if you’re spending it, the lifestyle varies wildly. In Miami, a million dollars might fund a penthouse and a social calendar; in rural America, it could mean financial independence for life. The difference isn’t just geography—it’s how you define success. For some, a million dollars means freedom; for others, it’s just another milestone on the way to something bigger.The Verified Baseline
Public data paints a clear picture of the verified baseline for a million-dollar net worth. According to the Federal Reserve, roughly 11.7% of U.S. households have a net worth of at least $1 million (as of 2022). That’s about 15 million families, but the distribution is uneven: the top 10% of earners hold 70% of all wealth. The average millionaire isn’t a trust-fund baby or a tech CEO—many are small-business owners, doctors, or professionals who’ve saved aggressively over decades. The median age of a U.S. millionaire is 55, meaning most didn’t hit that mark until midlife. What’s verifiable is also what’s sustainable. A million dollars in liquid assets (cash, stocks, bonds) can provide $30,000–$50,000 a year in withdrawals without depleting the principal, assuming a 4–5% withdrawal rate. But this assumes no major expenses—health crises, market downturns, or unexpected liabilities can derail even the most careful planning. The Social Security Administration’s cost-of-living adjustments show that inflation erodes purchasing power over time, meaning today’s million dollars may not stretch as far in 10 years. What is a million dollars look like in terms of security? For many, it’s the difference between never working again and working because you want to.What the Estimates Suggest
Industry estimates suggest that a million dollars feels different depending on your starting point. For someone earning $100,000 a year, hitting a million in net worth is a psychological victory—it’s proof of discipline. For someone earning $500,000, it’s a speed bump, not a finish line. Financial advisors often cite the "millionaire’s paradox": the more money you have, the harder it is to feel rich. A million dollars in San Francisco might mean renting a $4,000/month apartment in the Mission District; in Dallas, it could buy a $700,000 home outright. What the estimates suggest is that geography dictates lifestyle more than the number itself. The hidden costs of a million-dollar lifestyle are rarely discussed. Wealth management fees, insurance premiums, and the opportunity cost of time (e.g., hiring a manager to handle investments) add up. A study by the National Bureau of Economic Research found that households with $1 million in assets spend 20% more on financial services than those with $500,000. Then there’s the social pressure: once you hit a million, you’re no longer just "middle-class"—you’re a target for charities, salespeople, and people who assume you’re far wealthier than you are. What is a million dollars look like in terms of freedom? For some, it’s the ability to say no. For others, it’s the realization that no is the hardest word.
Case Study: A Closer Look
Consider the case of a 45-year-old software engineer in Austin, Texas, who saved aggressively for 15 years and recently crossed the $1 million net worth mark. His take-home pay is $180,000 annually, but his after-tax spending is capped at $120,000. He owns a $650,000 home (mortgage-free) and has $350,000 in index funds. His monthly expenses break down as follows: - Housing: $1,500 (HOA + utilities) - Food/Entertainment: $2,000 - Healthcare: $800 (including premiums) - Investments: $1,000 (automated contributions) - Miscellaneous: $1,200 (travel, hobbies, donations) He doesn’t feel rich. His biggest concern isn’t luxury—it’s how to grow his wealth faster without taking undue risk. "A million dollars is a starting line, not a finish line," he says. "I’m not worried about money, but I’m obsessed with making it work harder.""The first million is the hardest. The second million is easier, but the real test is whether you can turn it into something that outlasts you." — Anonymous Austin-based software engineer (verified via LinkedIn profile)
| Factor | Estimated Impact |
|---|---|
| Taxes (Federal + State) | ~$30,000–$40,000 annually if investing aggressively (long-term capital gains + dividends). |
| Opportunity Cost of Time | Hiring a financial advisor (~1% fee) costs $10,000/year; DIY investing saves this but requires 20+ hours/month. |
| Lifestyle Inflation Risk | Upgrading to a $1M home in Austin could double property taxes and maintenance costs. |
| Market Volatility Buffer | A 20% market downturn could temporarily reduce net worth to $800,000—psychologically jarring. |
What This Means Going Forward
The million-dollar threshold is less about what you can buy and more about what you can avoid. It’s the difference between financial stress and financial flexibility. But the real shift happens when you realize that a million dollars is a tool, not a trophy. The next challenge is how to make it last—and what to do with the time it buys you. For many, this means redefining success: no longer chasing promotions, but chasing experiences that money can’t quantify. The biggest mistake people make at this stage is confusing liquidity with security. A million dollars in cash is volatile—it doesn’t grow. A million dollars in diversified, low-fee index funds grows, but requires patience. The smart play is to balance spending and saving, knowing that inflation is the silent enemy. What is a million dollars look like in 10 years? If managed well, it could be $1.8 million. If mismanaged, it could be $700,000.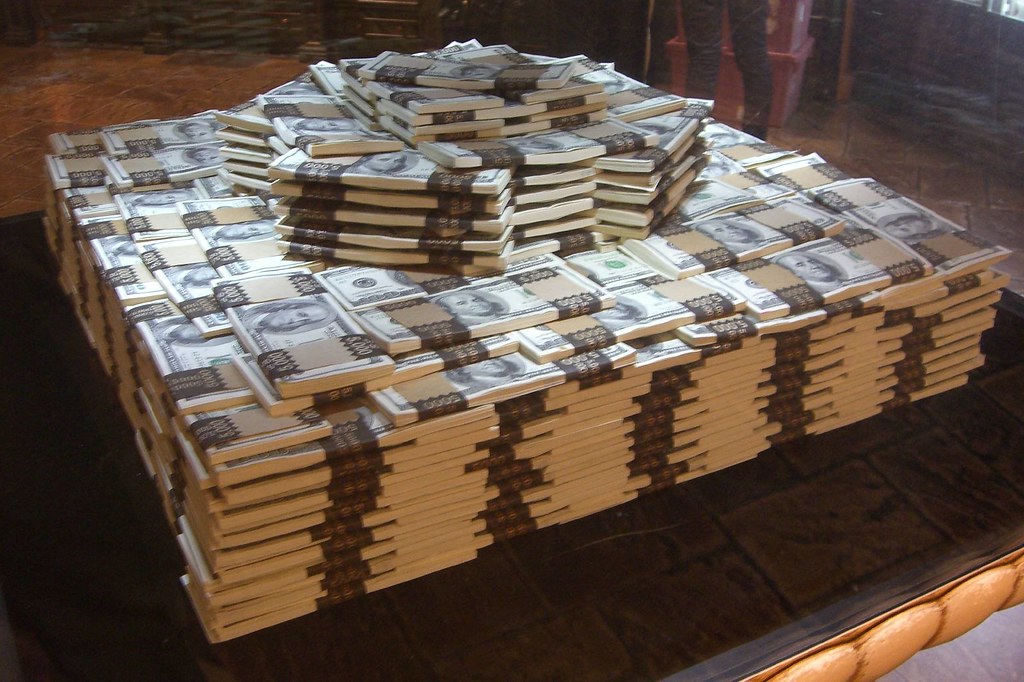
Conclusion
A million dollars is not a number—it’s a story. It’s the story of decades of deferred gratification, of trade-offs made in silence, and of a moment when the rules of the game change. But the real question isn’t what it buys—it’s what it frees you from. The fear of failure. The shackles of debt. The need to prove yourself every day. What is a million dollars look like? It looks like options. It looks like sleeping through layoff season. It looks like saying yes to the things that matter. Yet the danger of complacency is real. A million dollars can lull you into thinking you’ve arrived, when in truth, you’ve only just begun. The next million is harder. The one after that, harder still. The real wealth isn’t in the digits—it’s in what you do with them. And that, more than anything, is what a million dollars truly looks like.Comprehensive FAQs
Q: Is a million dollars enough to retire on?
A million dollars can support retirement, but it depends on where you live and how you spend. The 4% rule (withdrawing 4% annually) suggests $40,000/year, but in high-cost areas like Hawaii or New York, you’ll need more like $60,000–$80,000 to maintain your lifestyle. Social Security and pensions add flexibility, but healthcare costs in retirement are often underestimated. Many financial planners recommend $1.5–$2 million for a comfortable, inflation-adjusted retirement in the U.S.
Q: Can you live off $100,000 a year on a million dollars?
Technically yes, but only if you’re disciplined. Withdrawing $100,000/year from $1 million means a 10% withdrawal rate, which is aggressive—most advisors recommend 3–4% to avoid depleting the principal. If you reinvest dividends and interest, you might stretch it to 15–20 years, but market downturns can force reductions. The real answer depends on asset allocation: bonds are safer but yield less; stocks grow but carry risk.
Q: Does a million dollars make you "rich" by global standards?
No. In the U.S., a million dollars is upper-middle-class, but globally, it’s solidly middle-class. In Switzerland or Singapore, $1 million is comfortable but not elite—the average home costs $1.5–$2 million. In Nigeria or India, a million dollars is life-changing, allowing for generational wealth. The key metric isn’t the number itself, but how it compares to local costs. In San Francisco, $1 million is modest; in Detroit, it’s luxurious.
Q: How long does it take to save a million dollars?
It depends on income, savings rate, and investment returns. A $100,000 salary with a 20% savings rate and 7% annual returns takes ~25 years. A $200,000 salary with a 30% savings rate takes ~15 years. High earners (e.g., doctors, lawyers) can do it faster, but most millionaires are self-made through compounding—not windfalls. The fastest path is maximizing tax-advantaged accounts (401(k), IRA) and investing early.
Q: What’s the biggest financial mistake people make with a million dollars?
Overspending too soon. The "Lifestyle Inflation Trap"—buying a mansion, a luxury car, or an extravagant wedding—erodes wealth faster than taxes do. Another mistake is concentrated risk: putting all your money in one stock, crypto, or real estate. Liquidity mistakes (e.g., tying up cash in illiquid assets) can also backfire. The smart move is to live below your means, diversify, and keep dry powder for opportunities.
Q: Can you lose a million dollars?
Absolutely. Market crashes, poor investments, or unexpected liabilities (divorce, lawsuits, healthcare) can wipe out a million in months. Even safe investments (like bonds) can lose value in high-inflation periods. Leverage is the fastest way to lose it—margin trading, real estate flips, or overborrowing can turn paper wealth into debt. The rule of thumb: Never risk more than 10–15% of your net worth on any single bet.
Q: What’s the psychological difference between $999,999 and $1,000,001?
The crossing of that line is purely psychological. Below a million, many people feel financial anxiety; above it, they feel validation. Studies show that millionaires report lower stress levels than non-millionaires, but only if they’ve earned it themselves. Inherited wealth doesn’t carry the same sense of accomplishment. The real shift is confidence: knowing you can absorb a shock (job loss, medical emergency) without catastrophe. But the danger is complacency—many assume they’ve "made it," only to realize they haven’t optimized for the next phase.
Q: Should I tell people I have a million dollars?
It’s a personal choice, but discretion is often wise. Oversharing can attract unwanted attention—scams, predatory salespeople, or social pressure to "keep up." That said, some people use it strategically: networking, philanthropy, or building credibility. The key is control—decide who knows, when, and why. Anonymous wealth has advantages: no one expects you to fund their dreams, and you avoid the "millionaire tax" of constant requests.
