
Breaking Down the Numbers
The net worth of the poorest countries is a moving target, defined by what economists call national balance sheets. Unlike GDP, which tracks annual economic activity, net worth assesses a nation’s stock of assets (physical capital, human capital, natural resources) minus its liabilities (debt, infrastructure decay). For the bottom 20 countries on the UN’s Human Development Index, this exercise reveals a paradox: some have vast untapped resources (oil in Chad, minerals in the DRC), while others—like Haiti—possess almost no measurable assets beyond their labor force. The World Bank’s Wealth Accounting and Valuation of Ecosystem Services (WAVES) initiative has attempted to quantify these balances, but even its most rigorous models rely on gross approximations for nations with limited fiscal transparency. The challenge lies in the data itself. Many of these countries lack comprehensive asset registers, meaning estimates for infrastructure (roads, ports), environmental assets (forests, water tables), or even underground wealth (minerals, hydrocarbons) are educated guesses. For instance, the Democratic Republic of Congo’s mineral wealth is estimated at hundreds of billions, yet its net worth remains negative due to conflict-related losses and uncollected revenues. Meanwhile, nations like Timor-Leste saw their net worth surge after oil discoveries—but only after decades of instability. The net worth of poorest countries is thus less about static figures and more about volatility: a single shock (drought, coup, commodity crash) can erase decades of theoretical growth.The Verified Baseline
Publicly available data on the net worth of the poorest countries is sparse but critical. The World Bank’s International Comparison Program (ICP) provides GDP-adjusted figures, while the UN’s System of Environmental-Economic Accounting (SEEA) attempts to value natural capital. For example: - Burundi’s net worth is estimated at negative $2–3 billion, with liabilities (external debt, land degradation) far exceeding its modest infrastructure and agricultural output. - South Sudan’s net worth collapsed after independence in 2011, with oil revenues failing to offset $20+ billion in debt and conflict damages. - Haiti’s net worth is effectively zero, as its physical capital (ports, schools) has depreciated beyond replacement value, and its only "asset" is diaspora remittances (~$4 billion annually). These figures are derived from official government reports and multilateral audits, but even they are incomplete. Most poorest nations do not publish national balance sheets, leaving gaps in data on unrecorded assets (e.g., informal housing, subsistence agriculture) or hidden liabilities (corruption-linked debt, climate vulnerability).What the Estimates Suggest
Beyond verified data, analyst-driven estimates paint a broader picture. The Brookings Institution’s 2022 study on "wealth inequality" suggested that the bottom 50 countries collectively hold negative net worth, with liabilities exceeding $1 trillion when accounting for climate adaptation costs and post-conflict reconstruction. For instance: - Yemen’s net worth is estimated at –$50 billion, with war damages, port destruction, and lost tourism revenues far outweighing its pre-conflict infrastructure. - Central African Republic’s mineral wealth (gold, diamonds) is valued at $10–15 billion, but its net worth remains negative due to $1.2 billion in outstanding debt and $3 billion in annual conflict-related losses. - Nepal’s net worth is slightly positive (~$5 billion), but its human capital (education, health) is undervalued in standard models, masking deep inequalities. These estimates rely on cross-country benchmarks and proxy indicators (e.g., satellite data for deforestation, IMF debt reports). They are not audited but offer a framework for understanding how external shocks (COVID-19, Ukraine war) disproportionately erode the net worth of poorest countries by 3–5% annually.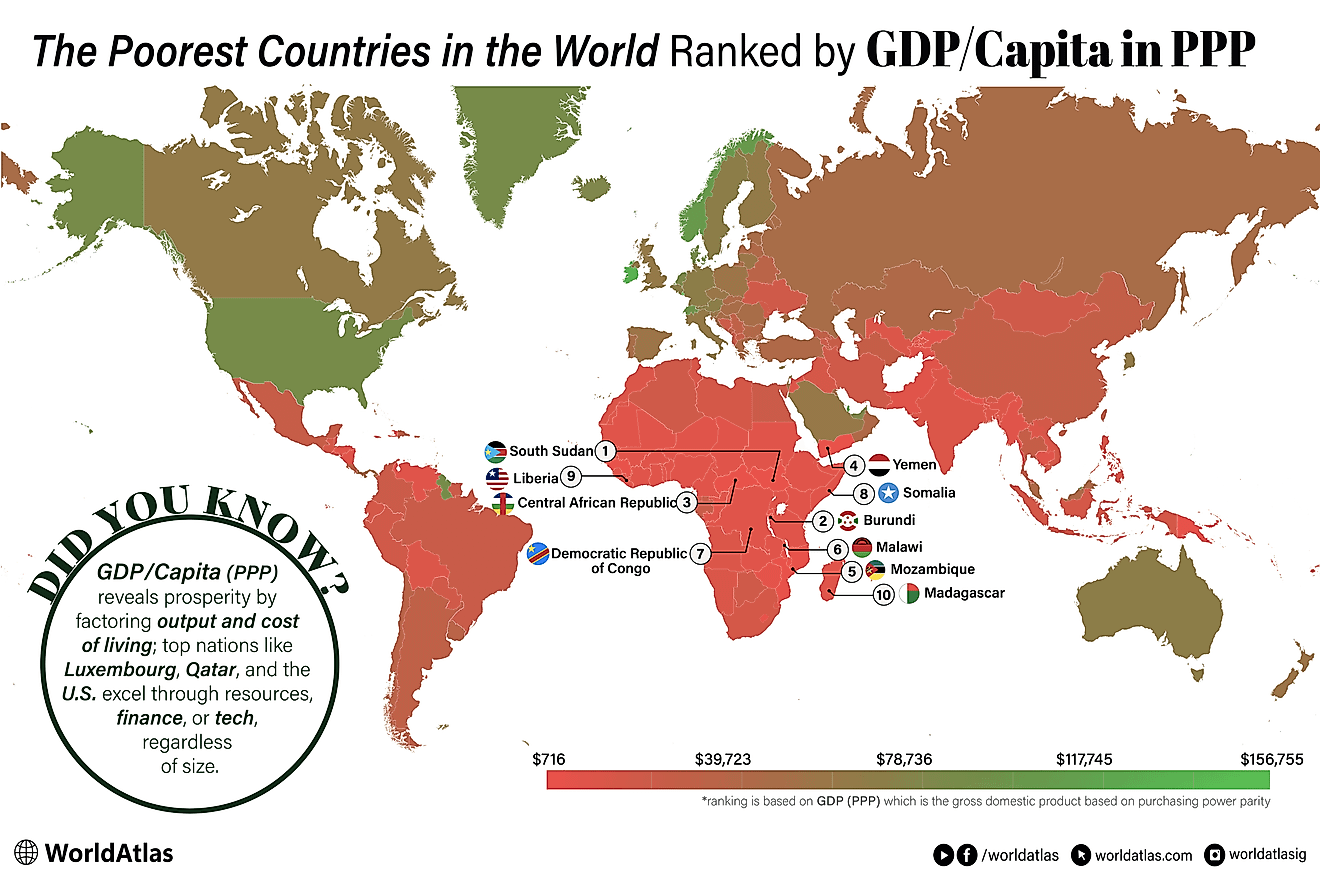
Case Study: A Closer Look
No example illustrates the net worth of poorest countries more starkly than Ethiopia, where rapid growth masked deep structural imbalances. Between 2000 and 2020, Ethiopia’s GDP expanded at ~9% annually, yet its net worth stagnated—and in some years, declined. The disconnect stems from three factors: 1. Debt-fueled growth: Ethiopia borrowed heavily for infrastructure (e.g., the Grand Ethiopian Renaissance Dam), but $30+ billion in external debt now exceeds the value of its completed projects. 2. Asset depletion: Deforestation (losing 140,000 hectares/year) and soil degradation reduce its natural capital by $1–2 billion annually. 3. Conflict costs: The Tigray war (2020–2022) destroyed $8 billion in infrastructure and agricultural output, offsetting decades of GDP gains. Ethiopia’s case shows how GDP growth can coexist with negative net worth—a phenomenon economists call "growth without accumulation." The country’s official net worth (if calculated) would likely be negative, despite its status as Africa’s second-most populous nation."Ethiopia’s economy is like a house built on sand: the bricks (GDP) look impressive, but the foundation (assets) is crumbling." — Abebe Aemro Selassie, former Ethiopian finance minister (2018)
| Factor | Estimated Impact on Net Worth |
|---|---|
| External debt (2023) | –$32 billion (IMF estimates) |
| Infrastructure losses (Tigray war) | –$8 billion (World Bank assessment) |
| Natural capital depletion (2000–2023) | –$20 billion (UN SEEA projections) |
| Diaspora remittances (annual) | +$5 billion (partial offset) |
What This Means Going Forward
The net worth of the poorest countries is not just a statistical footnote—it’s a predictor of stability. Nations with negative net worth are three times more likely to experience debt crises or social unrest, according to the OECD’s 2021 fragility report. The implications for global policy are clear: - Debt relief must account for asset depletion: Current IMF programs focus on GDP growth, not balance-sheet recovery. Yet Zambia’s 2020 debt restructuring revealed that its liabilities exceeded the value of its copper mines. - Climate adaptation is wealth creation: For small island states (e.g., Kiribati), negative net worth is exacerbated by sea-level rise. Investing in climate-resilient infrastructure could shift their balance sheets from –$1 billion to +$500 million over a decade. - Diaspora and informal economies are unrecognized assets: Remittances to Sub-Saharan Africa (~$50 billion/year) often exceed official aid, yet they’re excluded from most net worth calculations. The net worth of poorest countries will remain a moving target as long as traditional economics ignores stock vs. flow distinctions. Without addressing asset accumulation—not just income—these nations will continue to cycle through growth spurts followed by collapse.
Conclusion
The net worth of the world’s poorest countries is a silent crisis: one that receives far less attention than GDP rankings or poverty rates, yet determines whether a nation can recover from shocks. The data is incomplete, the estimates are speculative, but the pattern is undeniable—wealth in these contexts is often a liability. For policymakers, the takeaway is simple: poverty reduction requires asset-building, not just income support. For economists, it’s a call to refine models that treat nations as income streams rather than balance sheets. The challenge ahead is not just measuring the net worth of poorest countries but designing interventions that reverse negative balances. That will require better data, bolder debt restructuring, and a shift from GDP obsession to wealth equity. Until then, the numbers will keep telling the same story: growth without accumulation is just another form of poverty.Comprehensive FAQs
Q: What’s the difference between GDP and net worth for poor countries?
GDP measures annual economic activity (income), while net worth assesses total assets minus liabilities (wealth). A country can have high GDP growth but negative net worth if debt or asset depletion outpaces gains. Example: Ethiopia’s GDP grew rapidly, but its infrastructure and natural capital losses kept its net worth stagnant.
Q: Are there any poor countries with positive net worth?
Few, but some landlocked nations with stable institutions (e.g., Rwanda, Botswana) have slightly positive net worth due to low debt and high human capital. Most at the bottom (e.g., Burundi, South Sudan) remain deeply negative due to conflict, climate vulnerability, and debt burdens.
Q: How does climate change affect the net worth of poorest countries?
Climate shocks erode assets faster than GDP can recover. For instance, Haiti’s 2021 earthquake destroyed $1.5 billion in infrastructure, while droughts in Somalia reduce agricultural output by 20% annually. The World Bank estimates that by 2050, climate-related losses could halve the net worth of the poorest 30 nations.
Q: Why don’t these countries publish net worth reports?
Most lack the fiscal transparency or institutional capacity to compile national balance sheets. Even when data exists (e.g., mineral reserves), corruption or conflict prevents accurate valuation. The UN and World Bank have pushed for Wealth Accounting frameworks, but adoption remains low.
Q: Can debt relief improve a country’s net worth?
Yes, but only if structured to reduce liabilities without increasing future borrowing. Zambia’s 2020 debt restructuring cut its debt-to-GDP ratio by 15%, but new loans for COVID recovery risked offsetting gains. Ideal relief would write down debt while investing in asset-building (e.g., renewable energy, education).
Q: What role do diaspora remittances play in net worth?
Remittances are often the only positive contributor to net worth in poorest nations. For Nepal, they exceed 20% of GDP and fund informal infrastructure (housing, small businesses). However, they’re not counted as assets in standard net worth models, masking their true economic impact.
Q: Are there any success stories in reversing negative net worth?
Timor-Leste is a rare case: after gaining independence in 2002, its oil wealth (managed via a sovereign wealth fund) shifted its net worth from –$1 billion to +$15 billion by 2015. Rwanda’s post-genocide recovery also improved its balance sheet through debt restructuring and infrastructure investment, though its net worth remains slightly negative due to climate vulnerability.
Q: How accurate are estimates of the net worth of poorest countries?
Very uncertain. Most figures rely on proxy data (e.g., satellite imagery for deforestation, IMF debt reports). The World Bank’s WAVES program improves accuracy but still underestimates informal assets (e.g., subsistence farming) and overestimates liabilities (e.g., uncollected tax revenues). For conflict zones, estimates can vary by 50–100% due to missing data.
