Common Myths About Dealshare’s Financial Standing
The most persistent narrative around dealshare net worth is that the platform’s valuation sits in the billions, a claim often repeated in tech circles without verification. This myth gains traction because deal-sharing platforms, by their nature, attract high-profile investors and media attention, creating an aura of exclusivity. Yet private valuations are rarely static; they fluctuate with funding rounds, market conditions, and strategic pivots. A valuation cited in a 2021 funding announcement, for example, could be obsolete by the time the next round is announced—or never announced at all. The second myth revolves around the idea that Dealshare’s founders are sitting on personal fortunes comparable to those of retail moguls. While equity stakes can indeed be lucrative, especially if the company scales or undergoes an acquisition, the reality is far more nuanced. Founder wealth in private companies is often tied to vesting schedules, dilution over time, and the company’s ability to generate revenue—not just its valuation on paper. Another widespread misconception is that Dealshare’s revenue model is purely transaction-based, ignoring the role of subscriptions, ads, or data monetization. While transaction fees are a cornerstone, the platform’s dealshare net worth is also influenced by how aggressively it diversifies income streams. Some competitors, for instance, have experimented with premium memberships or even white-label solutions for retailers, adding layers to their financial health. Finally, there’s the assumption that Dealshare’s valuation is directly tied to its user base, as if more members automatically mean higher profits. In reality, user growth doesn’t always correlate with profitability, especially in markets where customer acquisition costs (CAC) outpace lifetime value (LTV). These myths persist because the deal-sharing sector lacks the regulatory scrutiny of public markets, allowing speculation to fill the gaps.Myth 1: Dealshare’s valuation is in the billions
The idea that dealshare net worth includes a multi-billion-dollar valuation stems from a few key factors. First, the platform’s funding history—particularly if it secured a high-profile round—can create a halo effect, making observers assume the company is worth far more than its last disclosed valuation. For example, if Dealshare raised $100 million at a $1 billion pre-money valuation in 2022, some might extrapolate that its current worth is significantly higher, ignoring dilution, burn rate, or changes in market conditions. Second, comparisons to public companies like Groupon or even retail giants with loyalty programs can distort perceptions. Groupon’s market cap, for instance, reflects decades of operations, whereas Dealshare’s valuation is tied to its growth stage and investor confidence. What’s actually known is far less dramatic. Private valuations are often private for a reason—they’re not meant to be benchmarked against public metrics. Industry estimates suggest that while Dealshare may have a strong position in its niche, its dealshare net worth is likely tied to a more modest valuation range, especially if it hasn’t achieved profitability. Funding rounds don’t always translate to proportional increases in valuation; some companies see their valuations stagnate or even decline if growth slows. Without an exit or IPO, the true dealshare net worth remains speculative, even for those with insider knowledge.Myth 2: Founders are billionaires due to their stake
The notion that Dealshare’s founders are personal billionaires because of their equity is a common oversimplification. Founder wealth in private companies is rarely liquid; it’s tied to the company’s performance, vesting schedules, and potential exit strategies. If a founder holds a 10% stake in a company valued at $500 million, that stake might be worth $50 million on paper—but realizing that value requires selling shares, which isn’t always an option without triggering tax events or dilution. Additionally, founders often face vesting periods, meaning they don’t own their full stake immediately. If the company’s valuation drops before vesting is complete, their personal dealshare net worth could take a hit. The reality is that founder wealth in private tech companies is often a mix of equity, salary, and secondary sales. Some founders diversify their holdings by selling portions of their stake to early investors or employees, but this is rare without a clear liquidity event. Dealshare’s leadership, like many in the space, may have significant personal wealth tied to the company—but calling them billionaires without concrete evidence is premature. Even if the company’s valuation were to reach the billions, founder payouts would depend on how those funds are distributed, whether through acquisitions, IPOs, or other mechanisms.Myth 3: Revenue is purely from transaction fees
Many assume that Dealshare’s dealshare net worth is solely a reflection of its transaction fee model, where the company takes a cut of each deal facilitated on its platform. While this is a major revenue driver, it’s not the only one. Subscription models, where users pay for premium access to exclusive deals, can add a steady income stream. Some platforms also monetize through ads, sponsorships, or even data insights sold to retailers. The diversification of revenue sources can make a company more resilient, especially if one stream underperforms. For example, if transaction volumes dip, subscriptions or ads might compensate for the loss. What the evidence suggests is that Dealshare’s financial health is a blend of these models, though the exact mix isn’t publicly disclosed. A reliance solely on transaction fees can be risky; if user engagement drops or deal quality declines, revenue could take a hit. The platform’s ability to balance these streams will play a key role in shaping its dealshare net worth over time.
What Holds Up to Scrutiny
At its core, Dealshare’s financial standing is built on three verifiable pillars: its funding history, user growth metrics, and strategic partnerships. Funding rounds provide the clearest snapshot of investor confidence, with each infusion of capital often tied to a revised valuation. While these valuations are private, they offer a baseline for understanding the company’s perceived worth. User growth, measured in active members or deal volume, is another tangible indicator—though it doesn’t always translate to profitability. Strategic partnerships, such as collaborations with retailers or payment processors, can also signal financial stability, as they often come with revenue-sharing agreements or upfront investments. What’s less clear is the company’s profitability. Many deal-sharing platforms operate at a loss initially, reinvesting revenue into growth. Without public disclosures, it’s difficult to assess whether Dealshare has achieved break-even status or remains in a high-burn phase. The dealshare net worth, in this context, is less about a single number and more about the interplay of these factors. Investors and analysts often look beyond valuation to metrics like customer retention, deal conversion rates, and operational efficiency to gauge true health. > "Private valuations are a snapshot, not a destination. What matters is whether the company can convert growth into sustainable revenue—and that’s where the real story lies."| Common Belief | What the Evidence Says |
|---|---|
| Dealshare’s valuation is in the billions. | Valuations are private and fluctuate; industry estimates suggest a lower range unless proven otherwise. |
| Founders are personal billionaires. | Founder wealth is tied to equity, vesting, and liquidity—rarely realized without an exit. |
| Revenue comes only from transaction fees. | Subscriptions, ads, and partnerships also contribute, though exact breakdowns are undisclosed. |
| User growth equals profitability. | High user numbers don’t guarantee profits; customer acquisition costs and retention are critical. |
Why the Confusion Persists
The lack of transparency in private companies is the primary driver of confusion around dealshare net worth. Unlike public firms, which must disclose financials quarterly, private platforms operate under no such obligation. Investors and employees may have non-disclosure agreements (NDAs) that prevent them from sharing details, leaving outsiders to piece together information from funding announcements, hiring trends, or industry rumors. This opacity creates a vacuum that speculation fills, particularly when platforms like Dealshare operate in high-growth sectors where valuations are a proxy for success. Another factor is the nature of the deal-sharing industry itself. Companies in this space often prioritize expansion over profitability, leading to high burn rates and valuations that don’t immediately reflect revenue. Media coverage can amplify this narrative, focusing on user milestones rather than financial health. When combined with the natural human tendency to project linear growth onto exponential metrics, the result is a distorted view of what dealshare net worth truly represents.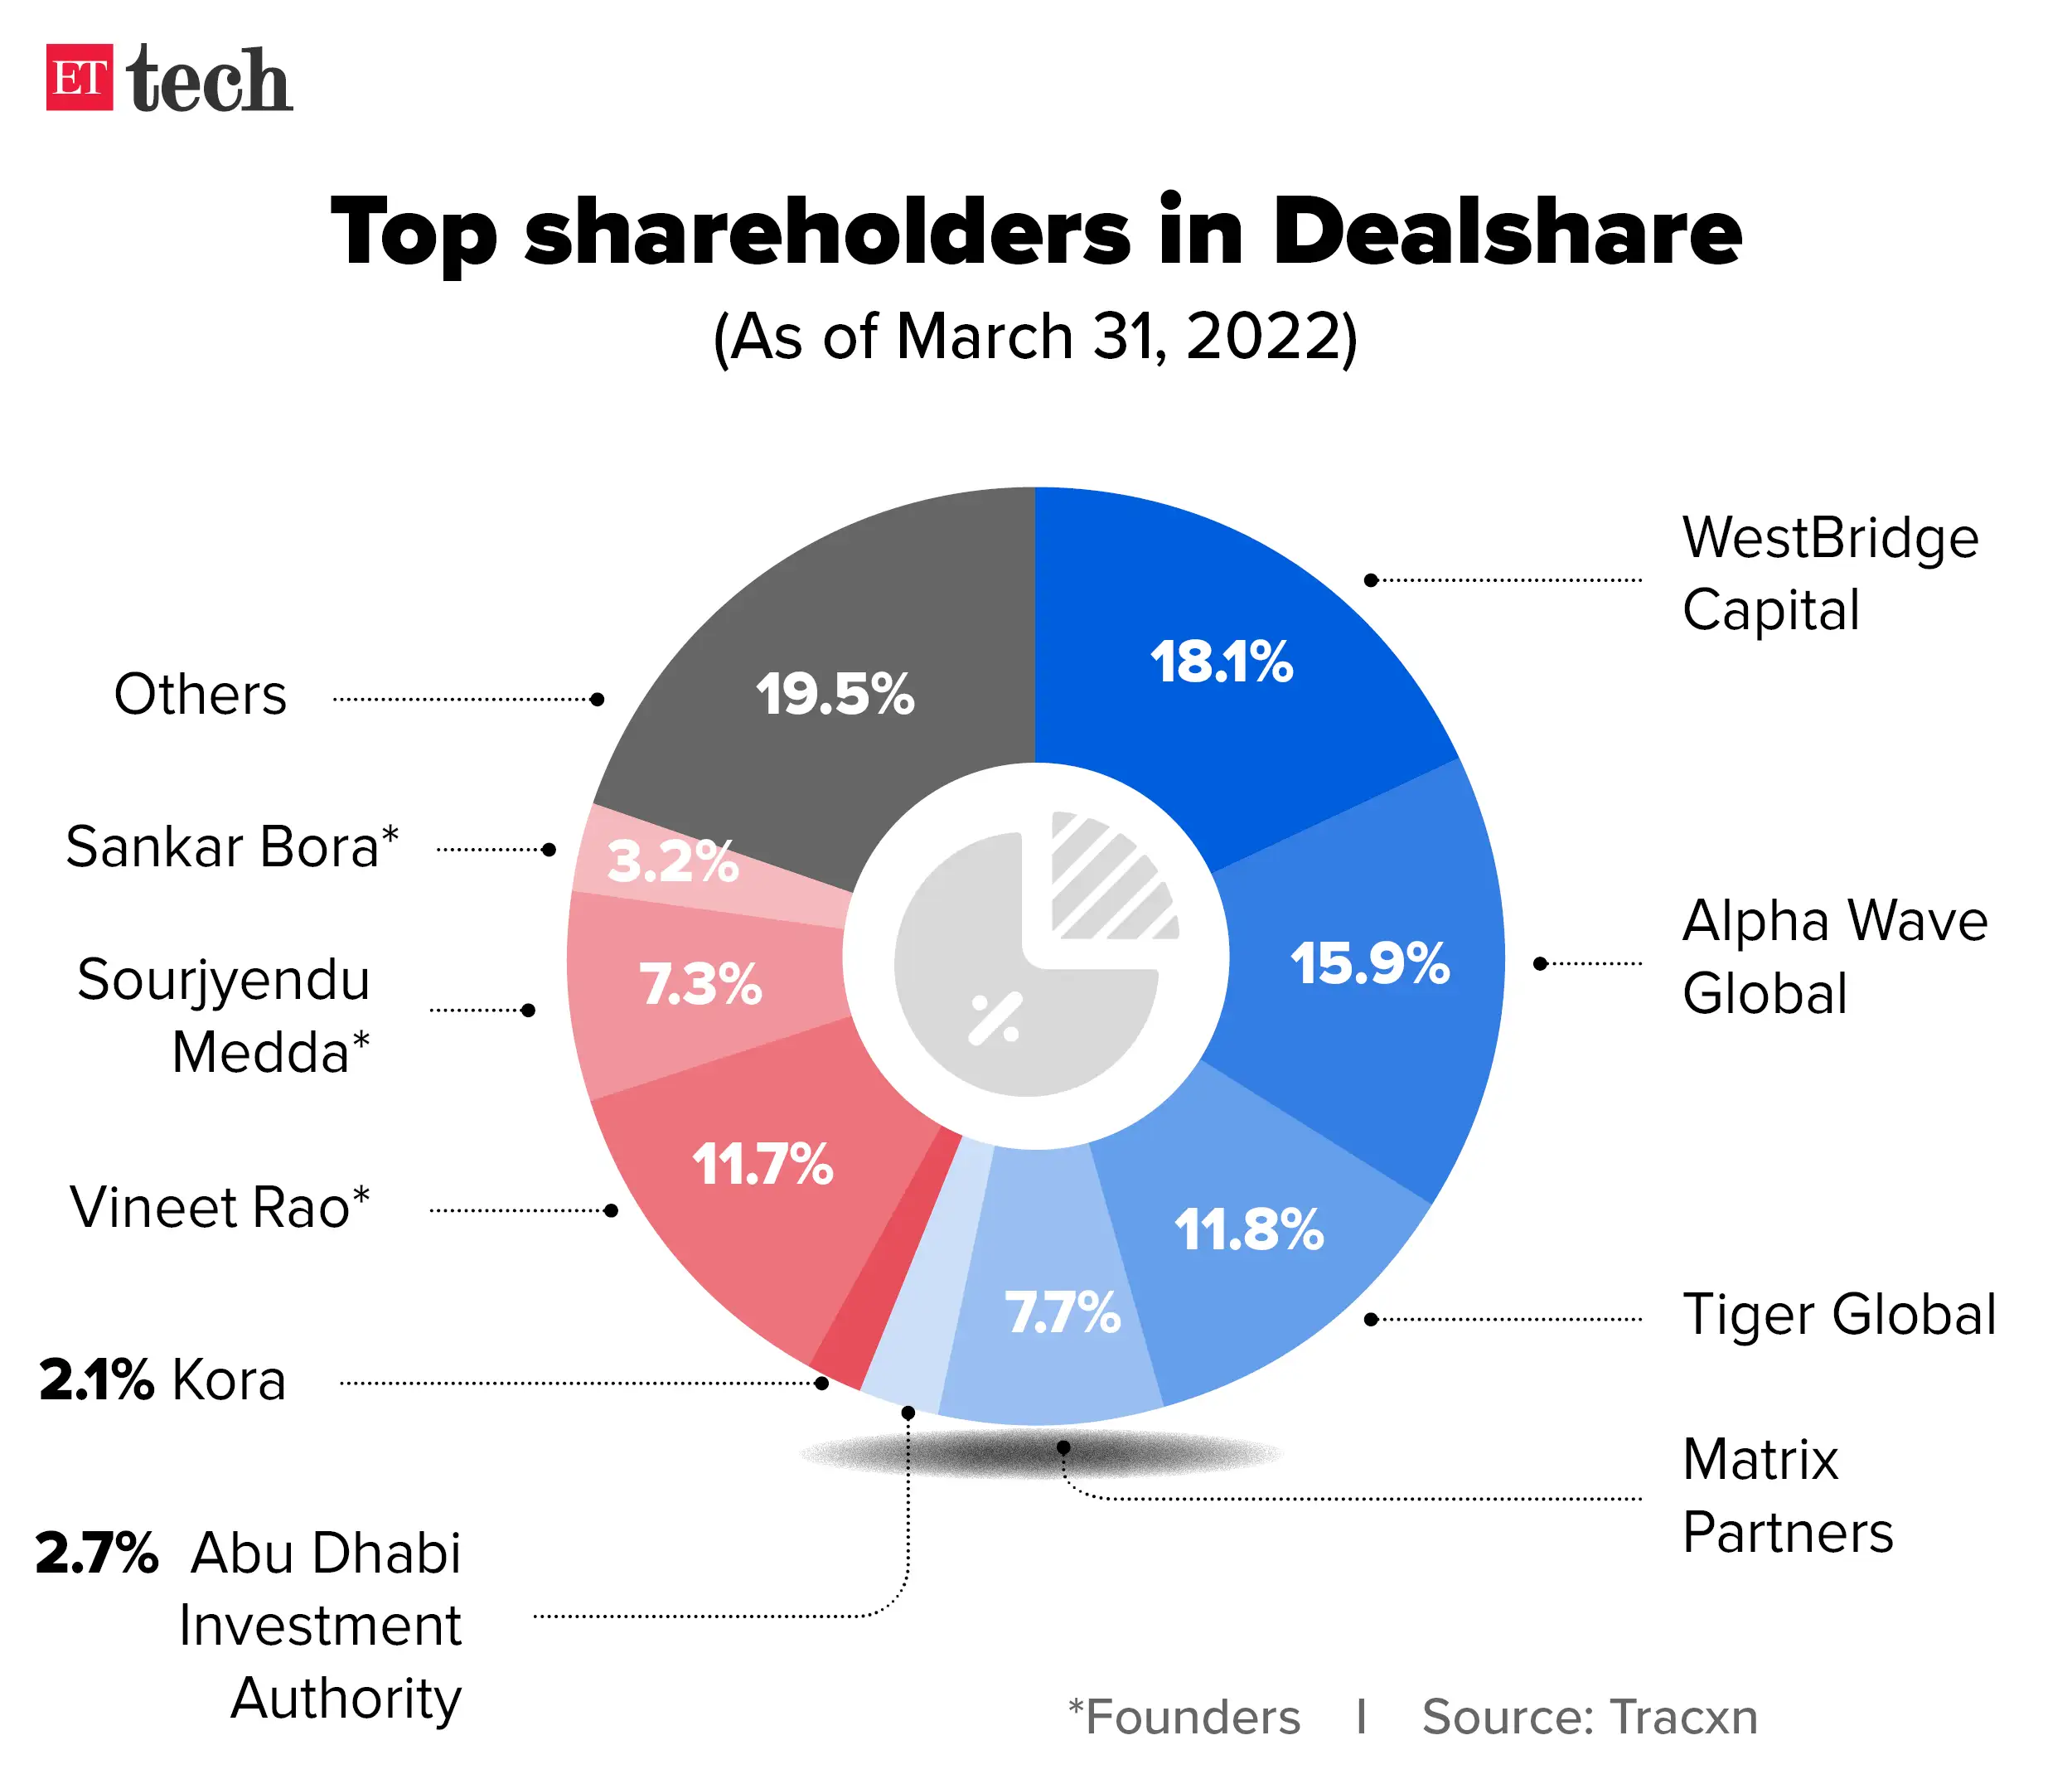
Conclusion
The debate over dealshare net worth is less about uncovering a single truth and more about understanding the limitations of the information available. Private valuations, founder wealth, and revenue models are all shaped by factors that remain outside public view. What’s certain is that Dealshare’s financial standing is a product of its ability to balance growth with sustainability—a challenge many in the tech sector face. The myths surrounding its worth highlight a broader issue: the gap between perception and reality in private markets, where speculation often outweighs concrete data. For those tracking dealshare net worth, the key takeaway is to approach figures with skepticism. Valuations are fluid, founder wealth is rarely liquid, and revenue streams are more complex than they appear. The most reliable indicators lie in the company’s ability to execute on its business model, retain users, and—ultimately—deliver returns to its investors. Until then, the true dealshare net worth remains a work in progress, one that only time and transparency will fully reveal.Comprehensive FAQs
Q: Is Dealshare’s valuation publicly disclosed?
No, Dealshare’s valuation is private and only becomes public if the company undergoes an acquisition, IPO, or other liquidity event. Funding rounds may provide snapshots, but these are rarely updated in real time.
Q: How do founders’ stakes translate to personal wealth?
Founder wealth is tied to equity ownership, vesting schedules, and the company’s performance. Without selling shares or an exit, equity is illiquid. Even if the company’s valuation is high, founders may not realize significant personal wealth until shares are sold or the company goes public.
Q: What are Dealshare’s main revenue streams?
The primary revenue streams include transaction fees, subscription models, and potentially ads or partnerships. The exact breakdown isn’t public, but diversification helps mitigate risk if one stream underperforms.
Q: Why can’t I find accurate figures on Dealshare’s net worth?
Private companies aren’t required to disclose financials, and valuations are often tied to funding rounds rather than ongoing metrics. Without an exit or IPO, the true dealshare net worth remains speculative, even for industry insiders.
Q: Does Dealshare’s user growth directly impact its valuation?
User growth is a key metric, but it doesn’t automatically translate to valuation increases. Investors also consider profitability, customer retention, and revenue diversification. High user numbers alone don’t guarantee a higher dealshare net worth.
Q: Are there any public records or filings that detail Dealshare’s finances?
Unless Dealshare has filed for an IPO or is subject to regulatory disclosures (unlikely for a private platform), there are no public financial records. Funding announcements and hiring trends are the closest proxies for financial health.
