7 Things Worth Knowing About the Disparity of Wealth in the United States
The disparity of wealth in the United States is a multifaceted crisis, shaped by history, policy, and global economic forces. Below are seven critical insights that explain how this divide functions—and why it persists.1. The Top 1% Own More Than the Bottom 90% Combined
The disparity of wealth in the United States reached a historic milestone in recent decades: the combined net worth of the top 1% now exceeds that of the entire bottom 90%. According to Federal Reserve data, this group—roughly 3.5 million households—holds more wealth than the 120 million Americans in the lower economic tiers. The concentration is even more extreme when considering financial assets alone: the top 10% of households own nearly 85% of all stocks and mutual funds. This isn’t just about income; it’s about generational wealth accumulation, where assets compound over time through inheritances, real estate, and investment returns. The disparity of wealth in the United States is further exacerbated by the fact that the ultra-rich—those with net worths exceeding $50 million—have seen their share of total wealth grow from 17% in 1989 to over 30% today. Tax policies like the 2017 Tax Cuts and Jobs Act, which slashed rates for capital gains and corporate taxes, accelerated this trend. Meanwhile, wages for the bottom 50% have stagnated for decades, adjusted for inflation. The result? A society where economic mobility is increasingly a myth, and where the children of the wealthy inherit not just money but the infrastructure to make it grow.2. Racial Wealth Gaps Persist Despite Civil Rights Progress
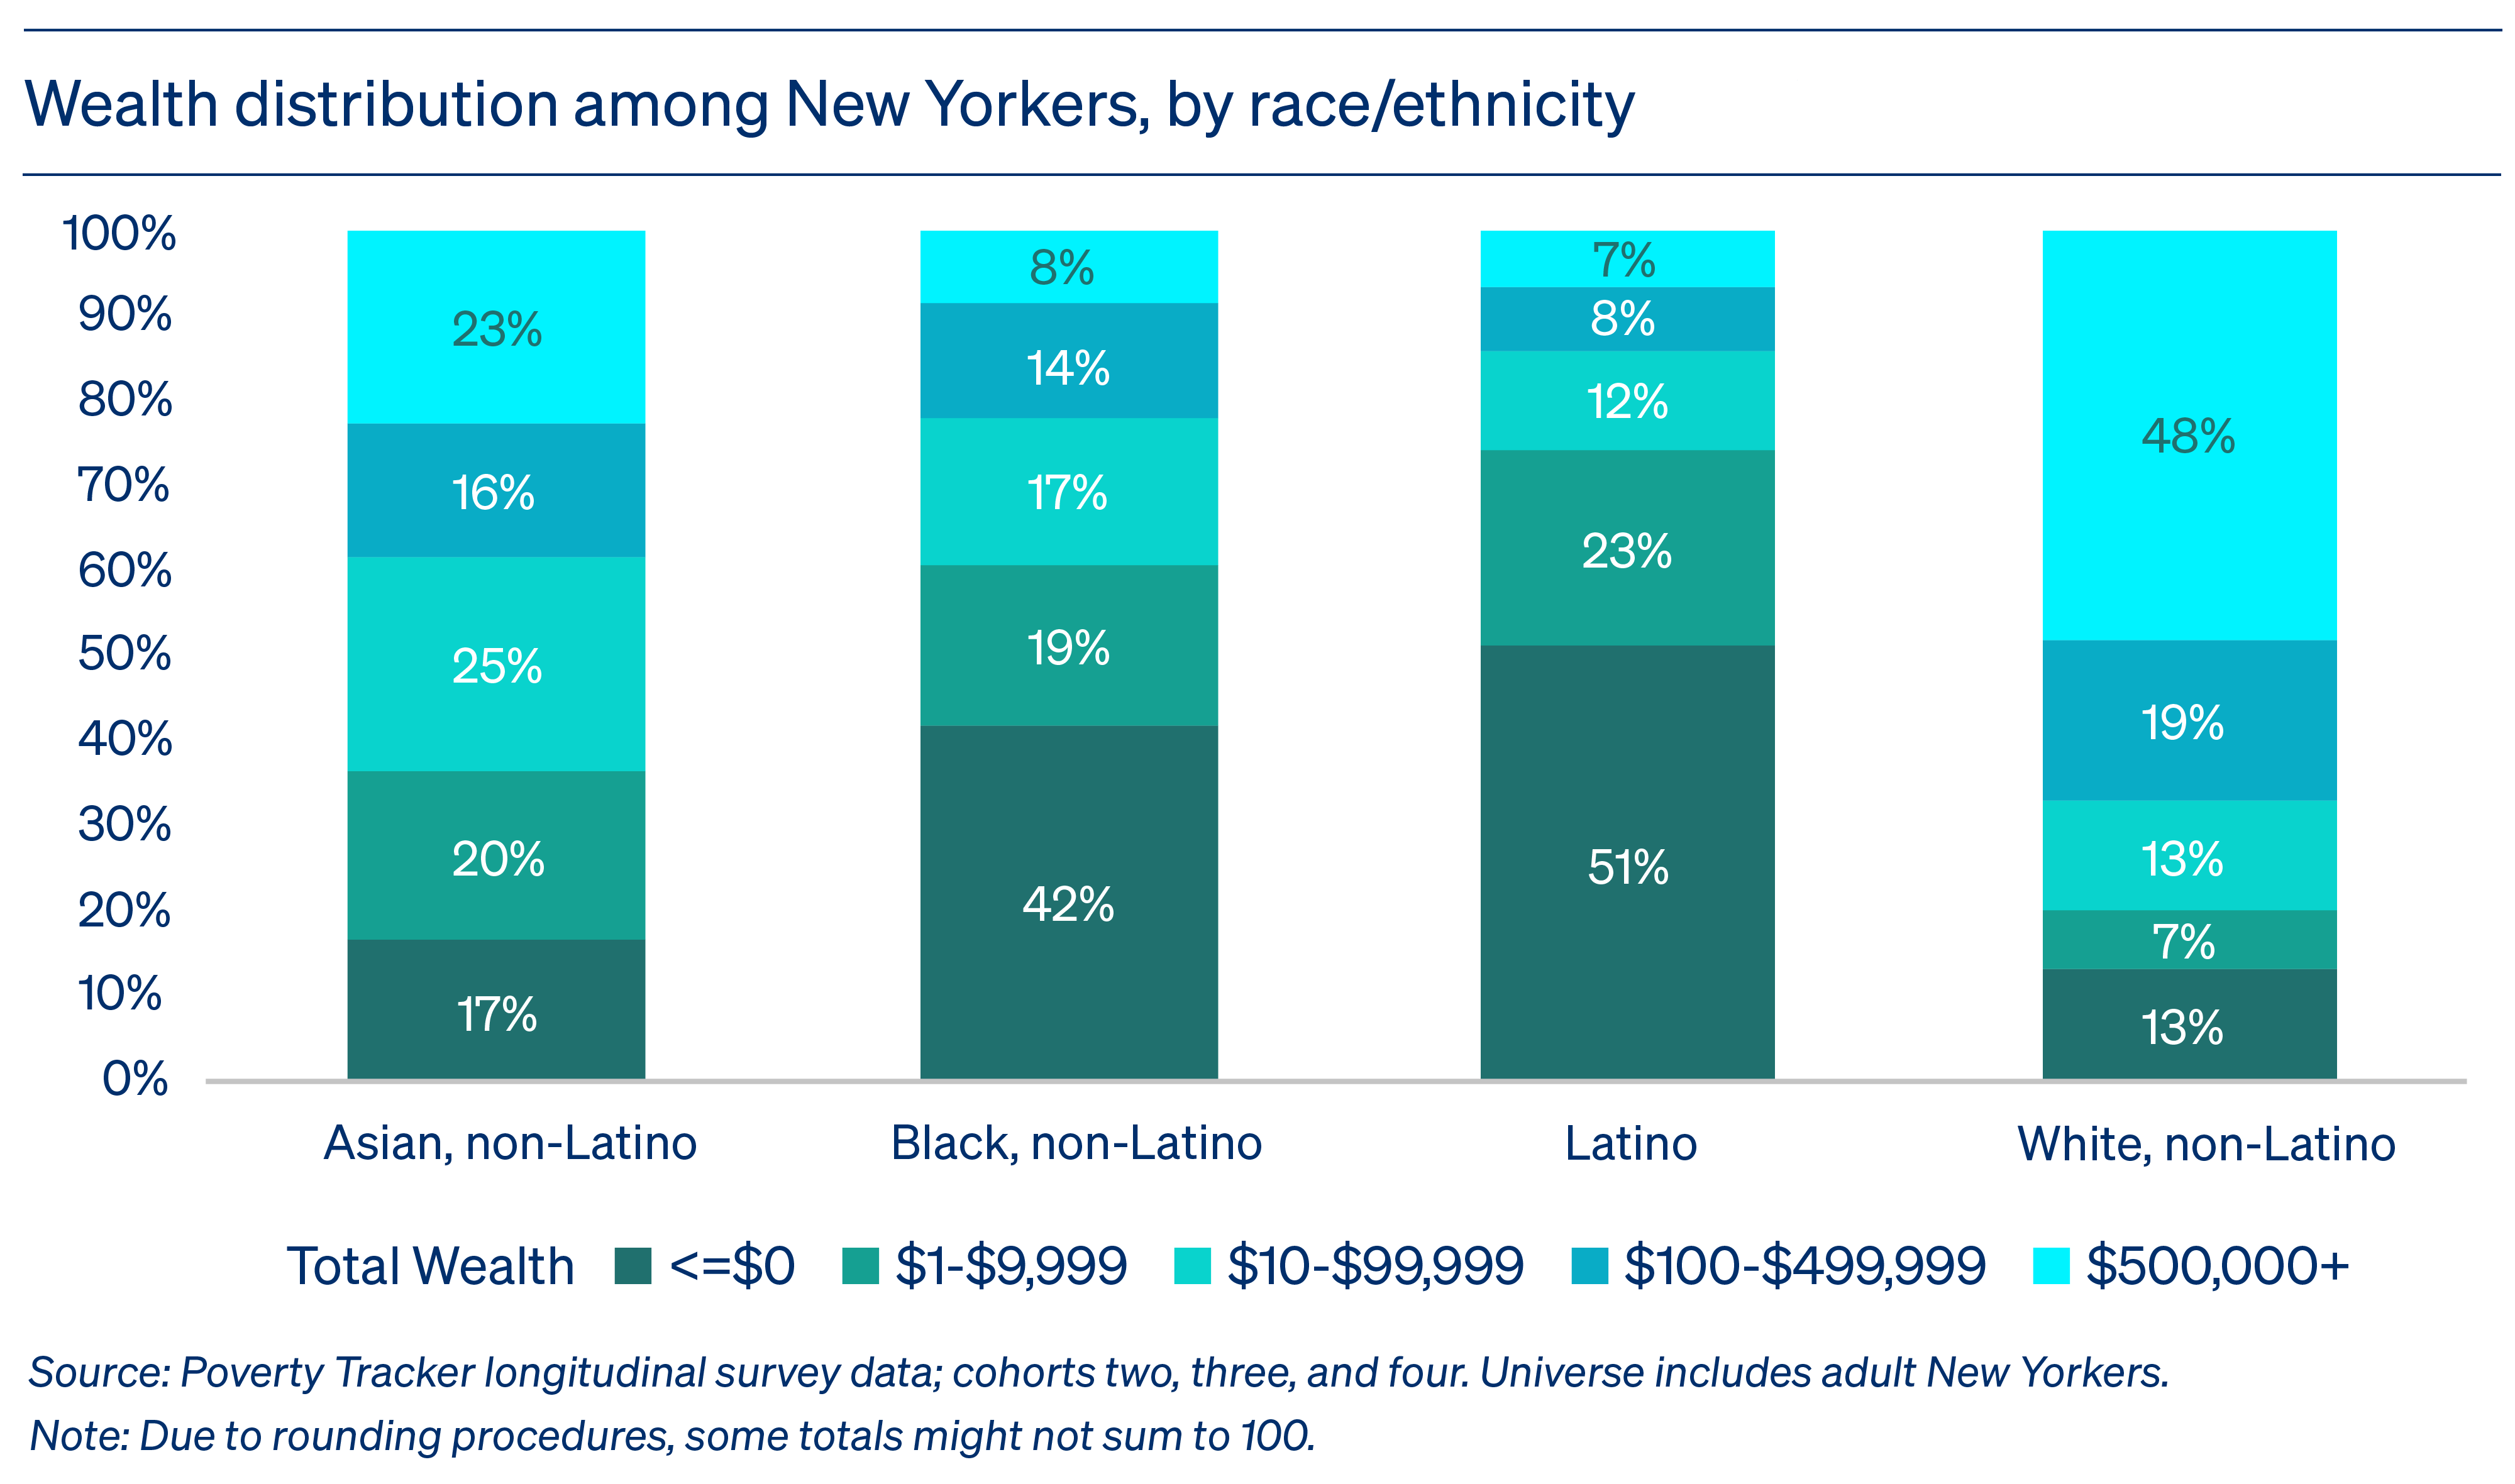
The disparity of wealth in the United States is deeply racialized. The median white family holds eight times the wealth of the median Black family and six times that of the median Latino family, according to the Federal Reserve’s 2022 Survey of Consumer Finances. These gaps did not emerge overnight; they are the legacy of systemic exclusion, from redlining in the mid-20th century to predatory lending practices that targeted minority communities. Even today, Black and Latino families face higher rates of unemployment, lower homeownership rates, and limited access to high-paying industries. The disparity of wealth in the United States is also reflected in education and opportunity. While white families can rely on inherited wealth to fund college educations or small businesses, Black and Latino families often lack these safety nets. The result? A cycle where racial disparities in wealth translate into disparities in political influence, healthcare access, and even life expectancy. Studies show that wealthier Americans live an average of 10 years longer than those in the bottom income quintile—a gap that mirrors racial health disparities.3. Corporate Profits Soar While Worker Pay Lags
One of the most striking aspects of the disparity of wealth in the United States is the divergence between corporate profits and worker compensation. Since the 1980s, productivity has surged, but wages for the majority of Americans have barely kept pace with inflation. Meanwhile, S&P 500 companies have seen their profits grow by over 600% since 1980, with much of that wealth flowing to shareholders rather than employees. The disparity of wealth in the United States is reinforced by executive pay packages that often exceed hundreds of times the average worker’s salary—CEOs of major corporations now earn over 300 times more than their typical employee. This imbalance is not accidental. Deregulation, the decline of unions, and the rise of gig economy jobs have all contributed to a labor market where workers hold less bargaining power. The disparity of wealth in the United States is further deepened by the fact that the richest 0.1%—those with net worths exceeding $20 million—pay an effective tax rate of just 8.2%, according to the Institute on Taxation and Economic Policy. Meanwhile, the bottom 20% face tax burdens that often exceed their income, thanks to regressive sales and payroll taxes.4. Homeownership Remains the Great Equalizer—But Only for Some
Wealth in the United States is heavily tied to homeownership, which remains the single largest asset for most middle-class families. However, the disparity of wealth in the United States is stark when examining who owns property and who rents. White families have a homeownership rate of 74%, compared to just 44% for Black families and 48% for Latino families. The gap is even wider when considering home equity: the median white household has $250,000 in home equity, while the median Black household has just $25,000. The disparity of wealth in the United States is also reflected in housing markets. In cities like San Francisco and New York, the median home price exceeds $1 million, pricing out all but the wealthiest. Meanwhile, in Rust Belt cities, abandoned properties and blighted neighborhoods reflect decades of disinvestment. Policies like the Homeowners Protection Act of 1995, which expanded mortgage lending to low-income families, often led to predatory practices that deepened racial wealth gaps. Today, even with rising home prices, Black and Latino families are less likely to benefit from equity growth due to historical barriers in accessing mortgages.5. Student Loan Debt Deepens the Wealth Gap
The disparity of wealth in the United States is increasingly tied to student debt, which now exceeds $1.7 trillion—more than the total value of all credit card debt in the country. While college education is often touted as the path to upward mobility, the reality is that student loans disproportionately burden low- and middle-income families. Black borrowers, for example, carry $25,000 more in student debt on average than white borrowers, even after controlling for income and education level. This debt not only delays major wealth-building milestones like homeownership but also reduces the ability to invest in assets that appreciate over time. The disparity of wealth in the United States is further exacerbated by the fact that wealthier families are far more likely to attend elite universities, where alumni networks and family connections can lead to high-paying jobs. Meanwhile, those who take on debt for community college or trade schools often face lower earning potential, trapping them in a cycle of debt without the corresponding returns. Policies like income-driven repayment plans have helped, but they do little to address the root cause: the cost of higher education has risen nearly 1,200% since 1980, far outpacing inflation.6. Political Power Follows the Money
The disparity of wealth in the United States has a direct impact on political representation. Wealthy individuals and corporations wield disproportionate influence over elections, policy, and regulatory decisions. The top 0.01%—about 14,000 families—spend more on political donations than the entire bottom 90% combined. This influence shapes everything from tax policy to labor laws, ensuring that the rules of the economy favor those who already have wealth. For example, the Citizens United decision in 2010 allowed unlimited corporate spending on elections, further tilting the playing field toward the wealthy. The disparity of wealth in the United States is also reflected in local governance. Zoning laws, school funding, and infrastructure investments often benefit affluent neighborhoods while neglecting poorer ones. Studies show that wealthier districts spend nearly twice as much per student on education as lower-income districts. This isn’t just about resources; it’s about who gets to shape the future of their communities. When political power is concentrated among the wealthy, policies that could reduce inequality—like progressive taxation or strong labor protections—are often watered down or blocked entirely.7. The Middle Class Is Shrinking
Perhaps the most alarming aspect of the disparity of wealth in the United States is the erosion of the middle class. Since the 1970s, the share of Americans in the middle-income tier has fallen from 61% to 50%, according to the Pew Research Center. Meanwhile, the top 20% now accounts for 45% of all income, up from 32% in 1970. The disparity of wealth in the United States is further deepened by the fact that two-thirds of Americans are now considered "lower-income" or "middle-income" by historical standards, yet their purchasing power has stagnated. The middle class is also aging. Younger generations—Millennials and Gen Z—are less likely to own homes, have retirement savings, or earn stable incomes compared to previous generations. The disparity of wealth in the United States is particularly stark for young adults: only 44% of Millennials own homes, compared to 62% of Baby Boomers at the same age. This generational divide suggests that the American Dream is becoming increasingly elusive for those who didn’t inherit wealth. Without significant policy changes, the middle class may continue to shrink, leaving the United States with a two-tiered economy: the ultra-rich and the precariously employed.
How These Facts Connect
The disparity of wealth in the United States is not a series of isolated problems—it is a self-reinforcing system where economic inequality fuels political inequality, which in turn perpetuates economic inequality. The concentration of wealth among the top 1% distorts the political process, allowing the rich to shape policies that benefit them while stifling upward mobility for others. Meanwhile, racial and regional disparities ensure that certain groups are systematically excluded from wealth-building opportunities, reinforcing cycles of poverty and disadvantage. The disparity of wealth in the United States also has cultural consequences. When opportunity is no longer tied to merit but to inheritance and connections, social trust erodes. Studies show that countries with greater wealth inequality have lower levels of social cohesion and higher rates of mental health issues. The American Dream—once a symbol of limitless possibility—now feels like a relic for many, replaced by a sense of stagnation and resentment. This cultural shift has political ramifications, fueling populist movements on both the left and the right as Americans search for scapegoats for their economic struggles.| Key Driver | Impact on Wealth Gap | Policy Response Needed |
|---|---|---|
| Corporate profits vs. worker wages | Top 10% own 85% of stocks; CEO pay 300x average worker | Progressive taxation, stronger unions, wage subsidies |
| Racial wealth disparities | White families: $250K home equity; Black families: $25K | Reparations debates, expanded mortgage access, anti-discrimination enforcement |
| Student debt burden | Black borrowers carry $25K more debt; higher education costs outpace inflation | Debt relief, tuition caps, income-based repayment reforms |
Conclusion
The disparity of wealth in the United States is not an accident—it is the result of deliberate policy choices, historical exclusion, and unchecked corporate power. While some argue that inequality is a natural outcome of free markets, the data shows otherwise: wealth accumulation is heavily skewed toward those who already have it, while barriers to entry for the rest grow higher. The consequences are visible in every corner of American life, from political polarization to public health crises. Addressing the disparity of wealth in the United States will require more than economic fixes—it will demand a reckoning with the country’s history and a commitment to structural change. Whether through progressive taxation, expanded social safety nets, or direct investments in underserved communities, the goal must be to create an economy where wealth is distributed more fairly. Without action, the divide will only widen, leaving future generations to inherit a society where opportunity is no longer the great equalizer but the privilege of the few.Comprehensive FAQs
Q: How does the disparity of wealth in the United States compare to other developed nations?
The U.S. has one of the highest levels of wealth inequality among developed nations, surpassed only by countries like Mexico and Turkey. The Gini coefficient—a measure of income inequality—places the U.S. at 0.48, higher than Canada (0.33), Germany (0.30), and Sweden (0.28). This disparity is driven by weaker social safety nets, lower taxes on the wealthy, and a more rigid class structure compared to European welfare states.
Q: Can the disparity of wealth in the United States be fixed without raising taxes on the rich?
While tax policy is a critical tool, reducing wealth inequality will likely require a combination of approaches. Stronger labor protections, expanded access to education and healthcare, and policies that promote homeownership among low-income families are essential. However, without progressive taxation—such as higher rates on capital gains and estates—there is little incentive for the wealthy to invest in systems that benefit the broader population.
Q: How does the disparity of wealth in the United States affect small businesses?
Small businesses are disproportionately owned by wealthy families, meaning the disparity of wealth in the United States stifles competition from entrepreneurs without inherited capital. Studies show that white-owned businesses receive 10 times more in government contracts than Black-owned businesses, even after controlling for size and industry. This creates a two-tiered economy: established firms with access to credit and networks, and startups struggling to gain traction.
Q: What role does globalization play in the disparity of wealth in the United States?
Globalization has contributed to inequality by offshoring jobs, suppressing wages, and concentrating wealth in industries like tech and finance. While it has created opportunities for some, it has also hollowed out the middle class in manufacturing and retail. The disparity of wealth in the United States is further exacerbated by trade agreements that prioritize corporate profits over worker protections, leading to stagnant wages and reduced union power.
Q: Are there any bright spots in reducing the disparity of wealth in the United States?
Yes, but they are often localized and underfunded. Cities like Minneapolis have experimented with wealth taxes on the ultra-rich, while states like California have expanded earned income tax credits. Community land trusts and cooperative housing models in places like New York and Boston are also helping low-income families build wealth. However, these efforts are nowhere near enough to offset national trends without federal policy changes.
