Common Myths About Avarage Net Worth by Age
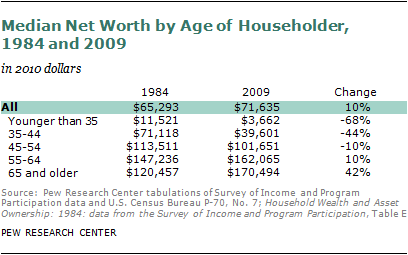
The first myth is the most persistent: that avarage net worth by age follows a smooth, upward curve. Financial media often presents these figures as a roadmap, implying that if you’re not hitting the "average" at each milestone, you’re failing. In reality, the data is skewed by extreme outliers—tech founders, late-career executives, or those who inherited wealth—while the median (the middle point) tells a far more modest story. For example, the median net worth for a 45-year-old in the U.S. is estimated at around $130,000, but the mean (average) jumps to $727,000 because of a handful of ultra-high-net-worth individuals pulling the numbers upward. Most people don’t recognize this distinction, leading to unnecessary anxiety when their own balance sheet doesn’t match the inflated average. Another widespread misconception is that avarage net worth by age is universal. The numbers vary dramatically by country, city, and even neighborhood. A 30-year-old in San Francisco might have a net worth that looks dismal compared to the U.S. average, but that’s largely because home prices in the Bay Area have outpaced wages for decades. Meanwhile, in Germany or Japan, where housing is more affordable relative to income, the same age group might appear wealthier by conventional metrics—even if their purchasing power is lower. Ignoring these geographic disparities leads to dangerous comparisons. Someone in London might see their net worth stagnating while rent eats into their salary, only to realize that in a city like Porto, their financial situation would look far healthier. The third myth is the most insidious: that avarage net worth by age is a measure of personal success. This framing ignores the fact that wealth accumulation is deeply tied to systemic advantages. A 2021 Brookings Institution study found that 60% of wealth inequality in the U.S. can be explained by differences in inheritance and family background, not just individual choices. Someone who starts a business at 25 might see their net worth skyrocket, while someone who takes a stable corporate job at the same age might barely keep pace with inflation. The data doesn’t account for risk tolerance, career flexibility, or the sheer luck of timing—factors that can make or break financial trajectories.Myth 1: "You Should Have X by Age Y—or You’re Behind"
The pressure to hit specific avarage net worth by age targets is a modern financial obsession, fueled by influencers and algorithms that thrive on urgency. But the truth is, these benchmarks are often based on outdated or cherry-picked data. For instance, the "millionaire by 35" mantra gained traction in the 2010s, yet the majority of self-made millionaires in that age group are entrepreneurs—who represent a tiny fraction of the workforce. The average salary worker, meanwhile, is far more likely to see their net worth grow incrementally, tied to home equity and retirement savings rather than asset appreciation. The myth persists because it’s easier to sell a simple narrative than to acknowledge the messy reality of financial progress. What the evidence says is far less binary. A 2023 study by the Urban Institute found that only 1 in 10 Americans under 40 have a net worth above $250,000, yet this figure is often treated as the "expected" outcome. The reality is that most people’s net worth grows in fits and starts—accelerating during homeownership, dipping during career pivots, and spiking only later in life. The key takeaway? Avarage net worth by age is a lagging indicator, not a leading one. Someone who appears "behind" at 30 might outpace the curve by 50 if they’ve made strategic moves like paying off high-interest debt or investing in skills that future-proof their income.Myth 2: "Gen Z Is Doomed Because They’re Falling Behind"
The narrative that younger generations are financially worse off than their predecessors is overstated. While it’s true that Gen Z enters the workforce with higher student debt and lower homeownership rates, the avarage net worth by age for this cohort isn’t as bleak as headlines suggest. The median net worth for a 25-year-old in the U.S. is estimated at $50,000, but this includes many who are still in school or living with family. When adjusted for debt and cost of living, the gap narrows significantly. Moreover, Gen Z is entering a job market where remote work, gig economies, and side hustles offer more flexibility than ever before—factors that traditional net worth metrics don’t capture. The confusion stems from comparing apples to oranges. Previous generations built wealth through homeownership and defined-benefit pensions, which are no longer the norm. Today’s young adults are more likely to rely on 401(k)s, rental income, and liquid investments—assets that don’t show up in traditional net worth calculations. The data also ignores the fact that younger cohorts are living longer, meaning their wealth-building timeline is stretched out. Avarage net worth by age for Gen Z might look lower today, but if they maintain steady income growth and avoid lifestyle inflation, they could surpass previous generations by retirement.Myth 3: "Women Always Lag in Net Worth—Period"
The gender wealth gap is real, but the assumption that women’s avarage net worth by age will always trail men’s ignores critical nuances. Women today are more likely to earn advanced degrees, delay marriage and children, and invest in careers with long-term growth potential—all of which can offset traditional disparities. A 2022 Federal Reserve analysis found that women’s net worth has been growing faster than men’s since 2010, particularly among younger cohorts. The gap persists in older age groups largely because women are more likely to take career breaks for caregiving, which disrupts wealth accumulation. However, this isn’t an inevitable outcome; it’s a function of systemic barriers that are slowly being addressed. What’s often overlooked is that women’s wealth strategies differ from men’s—and these differences can lead to stronger long-term outcomes. Studies show that women are more likely to diversify investments, pay down debt aggressively, and prioritize financial security over aggressive growth. While this might result in lower avarage net worth by age in the short term, it often translates to greater resilience in retirement. The myth that women are inherently at a disadvantage ignores the fact that financial success isn’t a zero-sum game. As more women enter high-earning fields and gain access to capital, the gap will continue to close—not because men are failing, but because women are redefining what wealth looks like.
What Holds Up to Scrutiny
At its core, the most reliable data on avarage net worth by age comes from large-scale surveys conducted by government agencies and non-partisan research institutions. These sources avoid the pitfalls of self-reported data or influencer-driven benchmarks by using rigorous sampling methods. For example, the Federal Reserve’s Survey of Consumer Finances is the gold standard in the U.S., providing a clear picture of how wealth accumulates across different demographics. What these studies consistently show is that homeownership is the single biggest driver of net worth growth, accounting for nearly 70% of the wealth gap between renters and owners. This is a critical insight often lost in discussions about avarage net worth by age, which tend to focus on income alone. Another verifiable trend is the role of inheritance and intergenerational wealth transfer. Data from the World Inequality Database reveals that inherited wealth accounts for 20–30% of total net worth in high-income countries, a figure that rises with age. This explains why avarage net worth by age appears to stagnate for many in their 40s and 50s: without access to family capital, their growth is limited to earned income and modest investments. The evidence also underscores that diversified portfolios outperform single-asset strategies over time, meaning those who treat net worth as a static number—rather than a dynamic balance sheet—are at a disadvantage. > "Wealth isn’t just about what you earn; it’s about what you own, what you owe, and what you’re positioned to inherit. The avarage net worth by age figures we see in headlines are useful only if you understand the hidden levers behind them." > — Edward N. Wolff, Professor of Economics at NYU and author of The Asset Price Meltdown| Common Belief | What the Evidence Says |
|---|---|
| By 35, you should have at least $100,000 in net worth. | Only the top 20% of earners in that age group meet this threshold; the median is closer to $50,000–$70,000. |
| Gen Z is financially worse off than Millennials at the same age. | Adjusted for debt and cost of living, Gen Z’s avarage net worth by age is competitive, but their wealth trajectory depends more on gig income and liquid assets than home equity. |
| Women’s net worth will always lag men’s by a fixed percentage. | The gap narrows significantly by retirement, with women often outperforming men in long-term investment returns due to lower risk tolerance and higher savings rates. |
Why the Confusion Persists
Part of the problem lies in how financial data is presented. Avarage net worth by age figures are often stripped of context, making them seem like universal truths. Media outlets and personal finance gurus prioritize simplicity over accuracy, leading to oversimplified takeaways like "You must have X by age Y." This approach ignores the fact that financial progress is nonlinear—career setbacks, health crises, or market downturns can derail even the most disciplined plans. The result? A culture of financial shame where people measure their worth against an unattainable ideal. Another factor is the halo effect of success stories. When a 30-year-old tech CEO or reality TV star flaunts their wealth, it creates the illusion that such outcomes are common. In reality, these are outliers, not averages. The avarage net worth by age for someone in their 30s is more likely to reflect a mix of student loans, modest home equity, and a 401(k) balance than a seven-figure portfolio. Yet because the media amplifies the exceptions, most people assume the rule. The confusion is further fueled by the lack of transparency in how these figures are calculated—whether they include primary residences, retirement accounts, or other assets—making direct comparisons meaningless.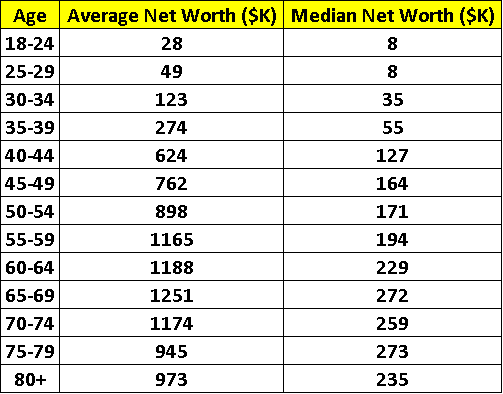
Conclusion
The data on avarage net worth by age is neither a roadmap nor a judgment. It’s a snapshot—a useful but incomplete tool for understanding financial progress. The key to making sense of it lies in recognizing that wealth accumulation is a function of systemic advantages, personal strategy, and sheer luck. Someone who inherits a family business will always appear wealthier at a given age than someone who starts from scratch, but that doesn’t mean the latter is failing. Similarly, a 40-year-old with no mortgage but high student debt might have a lower net worth than a peer who bought a home early—but their liquidity and flexibility could make them far more resilient in a downturn. What matters most isn’t hitting an arbitrary benchmark, but building a financial foundation that aligns with your goals and circumstances. If avarage net worth by age teaches us anything, it’s that wealth is a process, not a destination. The numbers are just one piece of the puzzle; the real story is in how you navigate the gaps between them.Comprehensive FAQs
Q: How accurate are the avarage net worth by age figures I see online?
A: Most online figures are based on median or mean estimates from surveys like the Federal Reserve’s SCF or OECD reports. However, they often exclude key details—such as whether home equity is included, how debt is treated, or whether the data is adjusted for inflation. Always check the source: government data is more reliable than influencer-driven benchmarks.
Q: Why does my net worth seem lower than the "average" for my age?
A: Several factors could explain this: high student debt, renting instead of owning, lower-than-average income, or career delays. The avarage net worth by age is heavily influenced by outliers (like homeowners or entrepreneurs), so if you’re in the median or below, you’re not alone. Focus on liquidity and cash flow rather than raw net worth.
Q: Does avarage net worth by age differ significantly by country?
A: Yes. In Nordic countries, where housing is affordable and social safety nets are strong, the avarage net worth by age tends to be more evenly distributed. In high-cost cities like Hong Kong or New York, homeownership pushes net worth higher earlier, but at the cost of liquidity. Meanwhile, in Germany or Japan, lower home prices mean younger adults appear wealthier by traditional metrics.
Q: Can I "catch up" if my net worth is below average for my age?
A: Absolutely, but the strategy depends on your situation. High earners can accelerate growth through tax-efficient investments or side income. Those with debt should prioritize paying down high-interest obligations before aggressive investing. The key is consistency: even small, regular contributions to retirement or emergency funds compound over time.
Q: How does divorce or separation affect avarage net worth by age?
A: Divorce can halve or eliminate net worth for many, especially if assets like a home are split. The avarage net worth by age for divorced individuals in their 40s is often 30–50% lower than for married peers, due to legal costs, reduced income, and the need to rebuild from scratch. This is one reason why financial advisors emphasize prenuptial agreements and asset protection for high-net-worth individuals.
Q: Are there any avarage net worth by age figures I should ignore entirely?
A: Yes. Celebrity net worth lists, influencer benchmarks, and "millionaire by X age" claims are often misleading. Focus instead on peer-group comparisons (e.g., net worth within your income bracket and location) and long-term trends rather than snapshots. The most useful figures are those adjusted for inflation, debt, and geographic cost of living.
Q: What’s the biggest misconception about avarage net worth by age?
A: The belief that it’s a fixed milestone rather than a dynamic metric. Your net worth at 30, 40, or 50 should be judged in the context of your career stage, health, and external factors—not against a one-size-fits-all average. The real question isn’t "Am I ahead?" but "Am I on a sustainable path?"
