The Complete Overview of What Is the Net Worth of All Americans
The net worth of all Americans represents the sum total of all assets—real estate, stocks, bonds, business equity, retirement accounts—minus liabilities like mortgages, student loans, and credit card debt. It’s a measure of financial health at a national scale, compiled primarily through the Federal Reserve’s Survey of Consumer Finances (SCF), which samples households every three years. The most recent full snapshot (2022 data) estimates the aggregate net worth at $148.7 trillion, though partial updates suggest it may have crossed $150 trillion by mid-2024. This figure isn’t just about the ultra-rich; it includes the $200,000 home of a middle-class family in Ohio, the $50,000 in a teacher’s pension fund, and the $10,000 in a young adult’s HSA. Even negative net worth—common among younger generations drowning in student debt—is factored in. What makes this number volatile is its dependence on three forces: asset prices, debt levels, and demographics. A rising stock market inflates the wealth of retirees with 401(k)s, while a housing boom benefits homeowners. But when the S&P 500 plunges or mortgage rates spike, the collective net worth can shrink by trillions in months. The Federal Reserve’s data also reveals a long-term trend: the total net worth of all Americans has grown 10-fold since 1989, adjusted for inflation. Yet this growth hasn’t been evenly distributed. The median net worth—a better indicator of typical households—lags far behind, sitting at $188,200 in 2022, up from $93,100 in 1989. The gap between the median and the mean (average) highlights how a handful of billionaires skew the total upward.Historical Background and Evolution
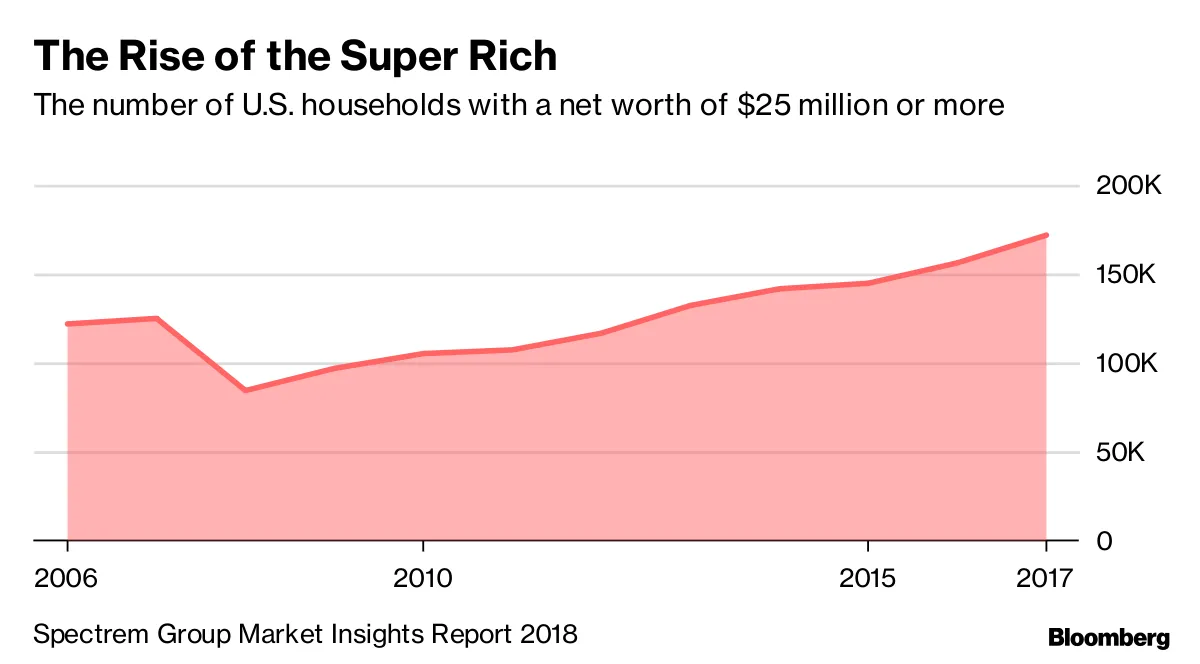
The concept of measuring national wealth isn’t new, but the modern approach to calculating what is the net worth of all Americans emerged in the mid-20th century. Before the 1950s, economists relied on patchwork data—census records, bank deposits, and spotty corporate filings. The Federal Reserve’s SCF, launched in 1962, became the gold standard, though its methodology has evolved. Early surveys focused on liquid assets; today, they account for illiquid ones like primary residences and small business equity. The 1980s marked a turning point. Deregulation, the rise of index funds, and the tech boom of the late 1990s accelerated wealth accumulation, particularly among older, asset-rich cohorts. By 2000, the total net worth of all Americans peaked at $52 trillion—until the 2008 financial crisis wiped out $16 trillion in two years. The recovery from 2008 was uneven. While the top 1% saw their wealth rebound quickly, the bottom 90% remained stagnant for a decade. The pandemic years (2020–2022) broke the mold. Stimulus checks, remote work boosting home values, and a stock market rally propelled the total net worth to $148 trillion by 2022—an increase of $30 trillion in just two years. But this wealth wasn’t distributed. The bottom 50% of households saw their net worth rise by only $1.5 trillion, while the top 10% gained $25 trillion. The data underscores a fundamental question: Is the total net worth of all Americans a measure of prosperity, or merely a reflection of who owns what—and who doesn’t?Core Mechanisms: How It Works
The calculation of the net worth of all Americans isn’t a simple addition of bank balances. It’s a three-step process: 1. Asset Aggregation: The Federal Reserve categorizes assets into financial (stocks, bonds, retirement accounts) and non-financial (homes, cars, businesses). Real estate alone accounts for 30% of total net worth, while financial assets make up 40%. 2. Liability Deduction: Debt—mortgages, student loans, credit cards—is subtracted. In 2022, total household debt hit $16.9 trillion, with student loans alone at $1.7 trillion. 3. Extrapolation: The SCF samples about 6,000 households but uses demographic weighting to estimate the national total. This method assumes that trends in the sample reflect broader patterns, though critics argue it undercounts wealth held by the ultra-rich in offshore accounts or private trusts. The result is a net worth per capita figure, which in 2022 stood at $443,000—but this masks extreme disparity. A single billionaire’s portfolio can swing the national average by billions. For example, if Jeff Bezos’s net worth fluctuates by $10 billion, the total net worth of all Americans moves by 0.006%. Yet for the median household, a $10 billion shift in Bezos’s wealth means nothing. The system is designed to capture trends, not equity.Key Benefits and Crucial Impact
Understanding what the net worth of all Americans amounts to isn’t just about crunching numbers—it’s about grasping the economic DNA of the country. Policymakers use this data to design tax brackets, housing subsidies, and retirement programs. Economists track it to predict recessions or recoveries. Even central bankers at the Fed monitor it to gauge consumer spending power. When the total net worth surges, as it did post-pandemic, it signals confidence in the economy. When it stagnates, as it did post-2008, it warns of a fragile recovery. The number also serves as a barometer for social mobility. If the median net worth grows faster than the mean, it suggests broader prosperity. If not, it confirms wealth concentration. The implications ripple beyond economics. Political campaigns hinge on promises to "grow the pie" or "redistribute wealth." Corporations lobby to lower capital gains taxes, arguing it will boost the total net worth of all Americans. Activists demand wealth taxes, citing the fact that the top 0.1% hold 20% of national wealth. Even cultural trends—like the rise of FIRE (Financial Independence, Retire Early) movements—are shaped by perceptions of collective wealth. The data isn’t neutral; it’s a battleground for ideology. > "Wealth isn’t just money—it’s power. And the net worth of all Americans is the ledger that shows who holds that power." > — *Thomas Piketty, economist and author of Capital in the Twenty-First CenturyMajor Advantages
- Policy Guidance: Governments use aggregate net worth to set fiscal policy. For example, if total assets shrink, stimulus checks or infrastructure spending may be justified.
- Market Signals: A rising net worth often precedes increased consumer spending, which drives GDP growth. Investors watch these trends to anticipate economic cycles.
- Inequality Tracking: By comparing median vs. mean net worth, economists identify wealth gaps. This informs debates on inheritance taxes or minimum wage hikes.
- Historical Benchmarking: Tracking the total net worth over decades reveals long-term trends, such as the shift from manufacturing to financial wealth.
- Global Comparisons: The U.S. leads in total net worth per capita, but lagging median figures highlight why other nations invest more in social welfare.
- Crisis Early Warnings : Sudden drops in net worth (e.g., 2008, 2020) often precede recessions, giving policymakers time to intervene.
Comparative Analysis
| Metric | United States (2024 Est.) | Germany (2024 Est.) |
|---|---|---|
| Total Net Worth of All Citizens | $150 trillion | €12 trillion (~$13 trillion) |
| Net Worth per Capita | $443,000 | €140,000 (~$150,000) |
| Median Net Worth | $188,200 | €60,000 (~$65,000) |
Future Trends and Innovations
The next decade will test whether the net worth of all Americans continues its upward trajectory or faces new headwinds. Demographic shifts—an aging population with high home equity but stagnant wages—could slow growth. Meanwhile, climate change may devalue coastal properties, erasing trillions in wealth overnight. Technological disruption, from AI-driven job losses to crypto volatility, adds uncertainty. One certainty: wealth concentration will remain a political flashpoint. Proposals for wealth taxes, universal basic assets, or even negative-interest rates on savings could reshape the ledger. Innovations in data collection may also change how we measure what is the net worth of all Americans. Blockchain could make tracking cryptocurrency wealth more precise, while AI might analyze spending patterns to estimate net worth in real time. But the biggest variable remains policy. If Congress enacts student debt relief or expands the child tax credit, the total net worth could rise by hundreds of billions. If not, the gap between the haves and have-nots will widen further. The question isn’t whether the number will change—it’s whether it will reflect a fairer economy.
Conclusion
The net worth of all Americans is more than a statistic—it’s a living document of the nation’s economic soul. It tells us who owns what, who benefits from growth, and who gets left behind. The current figure, north of $150 trillion, is a testament to decades of innovation, speculation, and policy decisions. But it’s also a warning: wealth isn’t distributed evenly, and the system that produces it favors those who already have. For policymakers, investors, and citizens alike, the number isn’t just about dollars. It’s about opportunity, security, and the kind of country we’re building. The challenge ahead isn’t just tracking the total net worth—it’s ensuring that future growth lifts more boats. Whether through education reform, progressive taxation, or new models of ownership, the debate over what the net worth of all Americans should be will define the next era. The ledger is open. The question is who gets to write the next chapter.Comprehensive FAQs
Q: How often is the net worth of all Americans updated?
The Federal Reserve’s Survey of Consumer Finances (SCF) is conducted every three years, with partial updates in between. The most recent full report (2022) covers data through that year, but the Fed releases quarterly updates on household balance sheets via its Financial Accounts of the United States (Z.1 report). For real-time tracking, economists rely on proxy data like stock market indices, housing price trends, and consumer debt reports.
Q: Does the total net worth include offshore accounts and hidden wealth?
No, not comprehensively. The SCF relies on self-reported data, and many ultra-high-net-worth individuals hold assets in offshore trusts, private foundations, or unlisted entities. The IRS estimates that $10 trillion to $30 trillion in global wealth is hidden from tax authorities, though the U.S. share is unclear. For the total net worth of all Americans, the Fed’s data likely undercounts wealth held in opaque structures, particularly among the top 0.1%.
Q: How does student debt affect the overall net worth?
Student debt is the largest liability dragging down the net worth of younger Americans. In 2022, $1.7 trillion in student loans reduced the total net worth by that amount. For households under 35, negative net worth is common—meaning their liabilities exceed assets. The Fed’s data shows that wiping out student debt could boost the median net worth by 10–15%, though the impact on the aggregate total would be smaller due to debt concentration among younger cohorts.
Q: Why is the median net worth lower than the average?
The median (middle point) is always lower than the mean (average) in wealth distributions because of skewness—a small number of ultra-rich individuals pull the average up. For example, if 90% of Americans have $100,000 in net worth and 10% have $1 billion, the median is $100,000 but the average is $110 million. This gap highlights wealth inequality. In the U.S., the top 1% holds 35% of total net worth, skewing the average far above the median.
Q: Can the total net worth of all Americans ever go negative?
Technically, yes—but it’s highly unlikely. A scenario where total liabilities exceed assets would require a catastrophic collapse in asset values (e.g., a 50% drop in stocks and housing) combined with a surge in debt (e.g., credit card defaults, mortgage crises). The closest the U.S. came was 2008–2009, when total net worth fell by $16 trillion, but it never turned negative. Even in hyperinflationary crises (like Weimar Germany), net worth can shrink to near-zero for individuals, but the aggregate total rarely does due to the diversity of assets.
Q: How does the net worth of all Americans compare to GDP?
The total net worth of all Americans (~$150 trillion) is roughly 5x larger than U.S. GDP (~$28 trillion in 2024). This makes sense because GDP measures annual economic activity (income, spending), while net worth is a stock (accumulated assets minus debts). The ratio highlights how wealth is concentrated over time. For context, if GDP were a river, net worth would be the ocean it flows into—growing slowly but retaining most of its value across generations.
Q: What happens to the total net worth during a recession?
During recessions, the total net worth typically declines sharply due to:
- Stock market crashes (financial assets drop).
- Falling home prices (30% of net worth).
- Increased defaults (credit card, auto, mortgage debt rises).
