
Common Myths About the Country With Least Debt
The first misconception is that the country with least debt is synonymous with economic invincibility. Investors and policymakers often assume that low debt equates to low risk, ignoring the fact that debt is just one variable in a complex system. Take Estonia, frequently cited as a poster child for fiscal responsibility with debt under 20% of GDP. Yet its recovery from the 2008 crisis required harsh austerity, and its low debt is partly an artifact of a tiny population and EU structural funds. The reality is that no country achieves low debt without trade-offs—whether it’s slower growth, reduced social spending, or exposure to external shocks. Another persistent myth is that small, resource-rich nations automatically qualify as the least indebted. Brunei’s debt-to-GDP ratio hovers near zero, but this is less a testament to policy and more a result of its oil wealth, which funds government operations without borrowing. The moment oil prices collapse—or if the fund is depleted—the illusion of debt-free stability vanishes. Similarly, Singapore’s low debt is propped up by its sovereign wealth fund, which acts as a fiscal buffer but also insulates the government from accountability. These economies are not "debt-free"; they are debt-avoidant, and the distinction matters when assessing long-term sustainability. The third myth is that the country with least debt must have a strong currency or high credit ratings. Switzerland’s debt is minimal, and its franc is a global reserve currency, but this is partly due to its status as a financial hub where capital flows in rather than out. Meanwhile, Norway’s low debt is underpinned by its oil fund, but its krone has faced volatility when commodity prices shift. The assumption that low debt guarantees monetary stability overlooks the role of geography, history, and global confidence. A nation’s debt profile is only as strong as the trust placed in its ability to manage it—and trust is not a function of balance sheets alone.Myth 1: The country with least debt is always the safest investment
The logic here is straightforward: if a government owes little, it can’t default, so its bonds are risk-free. But debt levels tell only part of the story. Consider Greece in the 2010s, which had higher debt than many peers but was deemed riskier due to political instability and weak institutions. Conversely, Japan’s debt is vast, yet its 10-year bond yields hover near zero because investors trust the Bank of Japan’s ability to monetize debt if needed. The safest investments aren’t always tied to the country with least debt; they’re tied to perceived solvency, which depends on factors like central bank independence, political cohesion, and external liquidity. Even among low-debt nations, risks emerge. Hong Kong’s debt is minimal, but its economy is tightly linked to China’s cycles, making it vulnerable to geopolitical shifts. Estonia’s low debt is a double-edged sword: while it weathered the 2008 crisis better than peers, its austerity measures stifled growth for years. The lesson is clear: low debt does not equal low risk. What matters more is whether the economy can absorb shocks without relying on borrowing—a trait more common in nations that have mastered debt management than those that have simply avoided it.Myth 2: The country with least debt has the highest standard of living
This correlation is intuitive: if a government spends less on debt servicing, it can invest more in infrastructure, healthcare, or education. Yet Singapore—often praised for its low debt and high living standards—achieves the latter through high taxes and state-directed capital controls, not fiscal austerity. Meanwhile, Brunei’s low debt has funded lavish public services, but its citizens enjoy wealth not because of prudent borrowing but because of oil revenues. The country with least debt isn’t necessarily the one where people thrive; it’s the one where debt doesn’t strangle growth. Conversely, Japan’s high debt has coexisted with a high quality of life, thanks to strong social safety nets and an aging population that saves aggressively. The relationship between debt and living standards is indirect. A nation can have low debt but stagnant wages (as in Germany), or high debt but universal healthcare (as in Japan). The key variable is how debt is deployed—whether it funds productive investments or becomes a drag on future generations.Myth 3: The country with least debt will never face a crisis
This is the most dangerous assumption. Estonia’s low debt allowed it to avoid the Eurozone’s bailout drama, but it also meant it had no fiscal firepower to stimulate its economy during the pandemic. Switzerland’s low debt is a result of its wealth, not its resilience; a banking crisis or sudden capital flight could expose vulnerabilities. Even Japan, with its massive debt, has faced periodic crises—not from default risk, but from deflationary pressures that debt alone cannot cure. The country with least debt is not immune to crises; it’s simply less likely to face a debt-driven crisis. The real threats come from external shocks (e.g., commodity price collapses) or structural weaknesses (e.g., aging populations, low productivity). Debt is a symptom, not the disease. The nations that survive are those that adapt their debt strategies to their unique challenges, not those that blindly pursue low debt as an end in itself.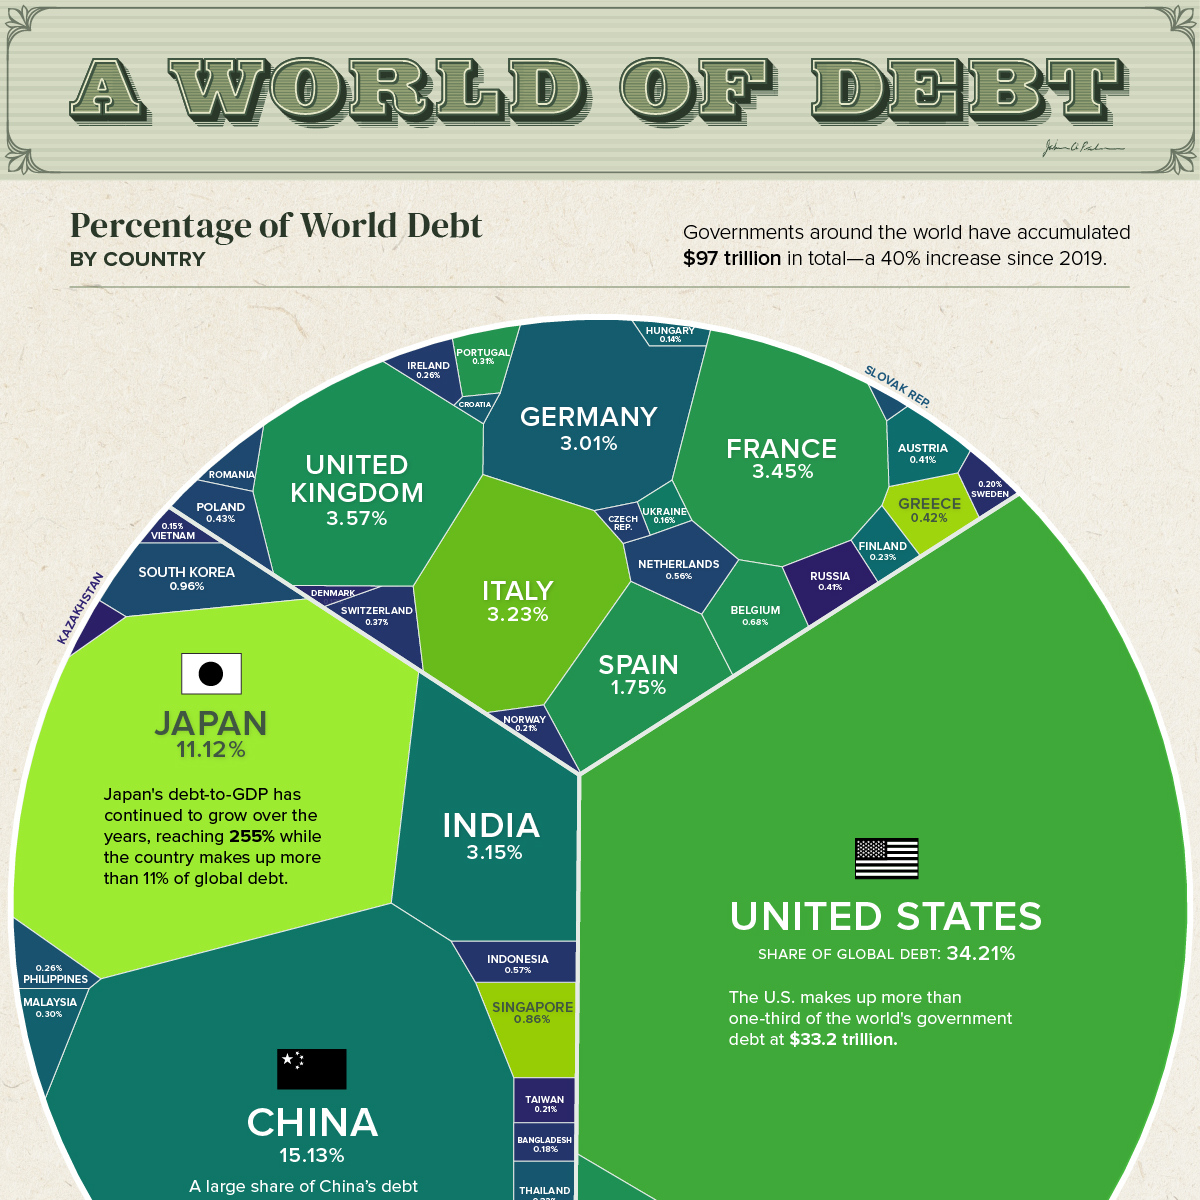
What Holds Up to Scrutiny
When stripping away myths, three factors consistently distinguish the country with least debt from those that merely appear debt-free: 1. Monetary sovereignty: The ability to print currency or control interest rates (e.g., Japan, Switzerland). 2. Fiscal buffers: Sovereign wealth funds or reserves that offset borrowing needs (e.g., Norway, Singapore). 3. Demographic tailwinds: An aging population that saves heavily, reducing the need for government debt (e.g., Japan, South Korea). These elements explain why Japan’s debt doesn’t trigger panic: its central bank can buy its own bonds indefinitely, its citizens hold most of the debt domestically, and its low inflation means debt servicing costs are manageable. Meanwhile, Switzerland’s low debt is a result of its status as a global financial center, where capital inflows reduce the need for domestic borrowing. The country with least debt isn’t the one with the smallest balance sheet; it’s the one where debt is least likely to become a constraint."Debt is not the enemy; mismanagement is. A country with high debt but disciplined monetary policy can outperform one with low debt but weak institutions." — Mohamed El-Erian, former CEO of PIMCO
| Common Belief | What the Evidence Says |
|---|---|
| The country with least debt is the safest. | Safety depends on monetary tools, not debt levels. Japan’s debt is high, but its bonds are among the safest in the world. |
| Low debt means high growth. | Growth depends on investment, not debt avoidance. Germany has low debt but sluggish growth; Singapore has low debt and high growth due to other factors. |
| The country with least debt will never default. | Default risk is about solvency, not debt size. Even low-debt nations can face crises (e.g., Estonia’s austerity backlash). |
Why the Confusion Persists
The persistence of myths around the country with least debt stems from two sources. First, media narratives simplify complex economics. Headlines about "debt-free paradises" ignore the structural conditions that make debt sustainable. Second, investors and policymakers focus on the wrong metrics. Debt-to-GDP ratios are easy to compare, but they don’t account for a nation’s ability to service debt, its currency’s role in global trade, or its political stability. There’s also a psychological bias: humans prefer clear narratives. The idea that "low debt = safety" is easier to grasp than the reality that debt is a tool, not a curse. Nations like Japan prove that debt can be a feature, not a bug—if managed correctly. Yet this nuance is often lost in the rush to label a country as the least indebted without examining how it got there or what it sacrifices in the process.
Conclusion
The search for the country with least debt reveals more about our assumptions than about economics. Japan’s high debt doesn’t make it a failure; it makes it a laboratory for how debt can coexist with stability when paired with the right policies. Meanwhile, nations with minimal debt—like Brunei or Singapore—demonstrate that wealth, not prudence, is often the driver of low borrowing. The real lesson is that debt is a means, not an end. What matters is how a nation uses debt to fuel growth, protect its citizens, and navigate crises. The next time someone asks, "Which country has the least debt?" the answer should be: It depends on what you value. If you prioritize absolute debt figures, the answer might be Estonia or Switzerland. But if you care about resilience, the answer is Japan—a nation that has turned debt into a non-issue by making its economy immune to the usual rules. The country with least debt isn’t the one with the cleanest balance sheet; it’s the one that has redefined what debt means.Comprehensive FAQs
Q: Is Japan really the country with least debt if its debt-to-GDP ratio is over 260%?
A: Not in absolute terms, but Japan’s debt is effectively risk-free due to its monetary policy tools, domestic ownership of its debt, and low inflation. The ratio is high, but the cost of servicing that debt is minimal, making it less of a liability than a statistical artifact. Other "low-debt" nations often rely on external factors (like oil wealth or capital inflows) that Japan’s model doesn’t.
Q: Can a country with high debt ever be considered the "country with least debt"?
A: Only if its debt is so large that it becomes irrelevant. Japan’s case is extreme: its debt is so entrenched that markets treat it as a baseline, not a risk. For most nations, high debt is a warning sign, but Japan’s combination of monetary sovereignty, demographic savings, and political stability has neutralized that risk. No other high-debt nation has replicated this.
Q: Why do some low-debt countries struggle economically despite their fiscal discipline?
A: Low debt alone doesn’t guarantee growth. Estonia’s austerity, for example, reduced debt but also suppressed demand during its recovery. Germany’s low debt has coincided with slow wage growth and export dependency. The country with least debt may avoid crises, but it can still face structural stagnation if its economy lacks dynamism. Debt is a symptom of broader economic health, not a cure.
Q: Are there any truly debt-free countries?
A: No. Even the smallest debt figures hide off-balance-sheet liabilities (e.g., pension obligations, contingent debts). Brunei’s near-zero debt is possible only because its sovereign wealth fund covers most expenses, but this is a temporary state dependent on oil revenues. True debt freedom is a myth; debt management is the reality.
Q: How does the country with least debt compare to those with moderate debt?
A: Moderate-debt nations (e.g., Canada, Australia) often have more flexibility to stimulate economies during downturns, whereas ultra-low-debt nations (e.g., Estonia) may lack fiscal firepower. The country with least debt can avoid crises but may also miss opportunities to invest in growth. The sweet spot is usually moderate, well-managed debt—not the extremes.
Q: Can a country deliberately reduce its debt to zero?
A: Theoretically, but the trade-offs are severe. Switzerland maintains low debt through high savings and capital inflows, but this requires restricting domestic consumption. Japan could run surpluses, but its aging population reduces tax revenues. The country with least debt isn’t usually one that chooses to eliminate debt; it’s one where debt becomes irrelevant due to other advantages (wealth, demographics, or monetary control).
