Common Myths About Car Percentage of Net Worth
The idea that car ownership is a neutral expense persists even among those who track net worth religiously. One persistent myth is that a car’s value doesn’t matter as long as it’s paid off. In reality, a £30,000 car that’s fully owned still represents a significant chunk of net worth—especially if the owner’s total assets are £80,000. The depreciation hit isn’t just about monthly payments; it’s about how that asset’s shrinking value affects overall liquidity. A car that’s 30% of net worth isn’t just an expense—it’s a liability that limits flexibility. Financial planners often overlook this because traditional metrics focus on income streams, not asset allocation. Another misconception is that luxury cars are the only problem. The truth is far more insidious: a £20,000 used SUV can be just as damaging to net worth if it’s 40% of a young professional’s total assets. The car percentage of net worth doesn’t discriminate by price point—it exposes how any vehicle’s cost interacts with an individual’s broader financial picture. Even a modest car can become a wealth anchor if it’s not balanced against savings, investments, or other liquid assets. The damage isn’t in the car itself, but in how it reshapes financial priorities.Myth 1: "If I own my car outright, it doesn’t count against net worth"
Ownership status doesn’t change the math. A £40,000 car owned free and clear still occupies a portion of net worth—whether it’s listed as an asset or not. The issue isn’t the balance sheet entry; it’s the opportunity cost of tying up capital in a depreciating asset. If that £40,000 could have been invested at a 7% annual return, it would grow to £42,800 in a year. Instead, the car loses value, insurance costs rise, and maintenance drains cash flow. The car percentage of net worth isn’t just about the purchase price—it’s about how that asset’s lifecycle impacts long-term growth. What’s often ignored is that car ownership isn’t static. A vehicle’s value erodes while its upkeep costs (insurance, repairs, fuel) increase. For someone with a £150,000 net worth, a £35,000 car might seem manageable—until the annual £3,000 in combined costs suddenly represents 2% of their total assets. The car percentage of net worth becomes a moving target, one that worsens over time unless actively managed.Myth 2: "Leasing keeps the car percentage of net worth low"
Leasing can feel like a financial hack because monthly payments seem lower than a loan. But the car percentage of net worth doesn’t drop—it shifts. A £60,000 leased car might require £800/month, but that’s still £9,600 annually. For someone with a £200,000 net worth, that’s nearly 5% of their assets tied to a vehicle they don’t own. The real kicker? Leasing often comes with mileage restrictions and early-termination penalties, adding hidden costs that inflate the true car percentage of net worth over time. The bigger problem is that leasing doesn’t build equity. Every payment is rent for an asset you’ll never possess. For a young professional with limited savings, a leased car can become a wealth black hole—a monthly obligation that doesn’t contribute to net worth while draining cash flow. The car percentage of net worth in a lease scenario isn’t just about the vehicle; it’s about the lost opportunity to invest that £800/month elsewhere.Myth 3: "A car is just a tool—it doesn’t affect net worth"
This is the most dangerous myth of all. A car isn’t just a tool; it’s a financial multiplier. For a freelancer with a £120,000 net worth, a £25,000 car might seem reasonable—until tax deductions, depreciation, and repair costs turn it into a net liability. The car percentage of net worth isn’t just about the purchase; it’s about how that asset interacts with tax brackets, insurance rates, and emergency buffers. A car that’s 20% of net worth can limit options during downturns, forcing tough choices between repairs and savings. The reality is that cars are wealth accelerators or decelerators. A well-chosen used car with low insurance costs can free up cash for investments. A poorly timed luxury purchase can lock someone into a cycle of debt and depreciation. The car percentage of net worth isn’t a static number—it’s a dynamic factor that shifts with market conditions, personal finances, and even geographic location.
What Holds Up to Scrutiny
The car percentage of net worth isn’t just about avoiding mistakes—it’s about strategic allocation. The most resilient financial plans treat cars like any other asset: they assess liquidity, depreciation, and opportunity cost. For someone with a £1 million net worth, a £100,000 car might be negligible. For a teacher with £80,000 in savings, the same car could be a wealth anchor. The key isn’t to eliminate car ownership but to ensure it aligns with broader financial goals. What’s verifiable is that cars are the second-most depreciating asset after electronics. Unlike stocks or real estate, they offer no upside beyond utility. The car percentage of net worth becomes critical when it exceeds 10-15% of total assets for most households. Beyond that threshold, the trade-offs—lost investment potential, higher insurance premiums, and reduced financial flexibility—often outweigh the benefits of ownership."A car is the one asset where the rich and poor make the same mistake: they buy based on emotion, not arithmetic. The difference is that the wealthy know how to offset the cost with other assets." — A certified financial planner specializing in high-net-worth individuals
| Common Belief | What the Evidence Says |
|---|---|
| A car’s value doesn’t matter if it’s paid off. | Depreciation and upkeep costs still erode net worth over time. |
| Leasing reduces the car percentage of net worth. | Monthly payments still represent a fixed allocation of assets, often with hidden penalties. |
| Luxury cars are the only concern. | Even modest cars can distort net worth if they exceed 15% of total assets. |
| Car ownership is neutral if it’s a necessity. | Opportunity cost (lost investment potential) turns it into a wealth drain. |
| Older cars are always cheaper. | Repair costs and insurance spikes can offset initial savings. |
Why the Confusion Persists
Financial education rarely addresses the car percentage of net worth because it’s seen as a "lifestyle" issue. Advisors focus on stocks, bonds, and retirement accounts—assets that grow over time. A car, by contrast, is a liability in disguise, one that most people don’t quantify until it’s too late. The lack of standardized tracking makes it easy to ignore. Unlike a mortgage or student loan, a car’s financial impact isn’t tied to a clear amortization schedule. Cultural narratives also play a role. Car commercials, celebrity endorsements, and even workplace norms glorify ownership without discussing the hidden costs. The message is often: "You deserve this." What’s missing is the follow-up: "Can you afford it without sabotaging your net worth?" The result is a generation of buyers who treat cars as status symbols rather than financial instruments.
Conclusion
The car percentage of net worth isn’t about deprivation—it’s about intentionality. The goal isn’t to avoid cars entirely but to ensure they serve a purpose without undermining financial security. For someone with a £500,000 portfolio, a £80,000 car might be a rounding error. For a young professional with £60,000 in savings, the same car could delay retirement by years. The difference isn’t the car; it’s the context. The solution lies in treating cars like any other asset: assess the purchase against net worth, depreciation curves, and alternative uses for capital. A well-chosen vehicle can enhance mobility and quality of life. A poorly timed purchase can become a wealth anchor. The car percentage of net worth isn’t just a number—it’s a reflection of how aligned your spending is with your long-term goals.Comprehensive FAQs
Q: What’s a healthy car percentage of net worth?
A general rule of thumb is keeping the car’s value under 10-15% of total net worth. For someone with £200,000 in assets, that means aiming for a car valued at £20,000–£30,000. Beyond that, the opportunity cost of lost investment potential often outweighs the benefits of ownership.
Q: Does leasing ever make sense for net worth?
Leasing can be useful in specific cases—such as for business owners who can deduct lease payments as expenses. However, for most individuals, leasing doesn’t improve the car percentage of net worth; it simply shifts the financial burden from asset ownership to monthly obligations. The key is ensuring the lease terms don’t exceed what you’d spend on a lower-value alternative.
Q: How does a car’s depreciation affect net worth?
Depreciation directly reduces net worth because the car’s market value drops while its upkeep costs (insurance, repairs, fuel) remain. For example, a £50,000 car might be worth £35,000 after three years, while annual costs could total £6,000. Over time, this turns the car into a net liability rather than an asset.
Q: Should I sell my car if it’s pushing my net worth limit?
It depends on your financial goals. If the car is a drain (high maintenance, poor resale value) and its cost exceeds 15% of your net worth, downsizing or switching to a more economical model could free up capital for investments. However, if the car is reliable and its cost is manageable, the trade-off might be worth it for lifestyle reasons.
Q: How can I reduce my car’s impact on net worth?
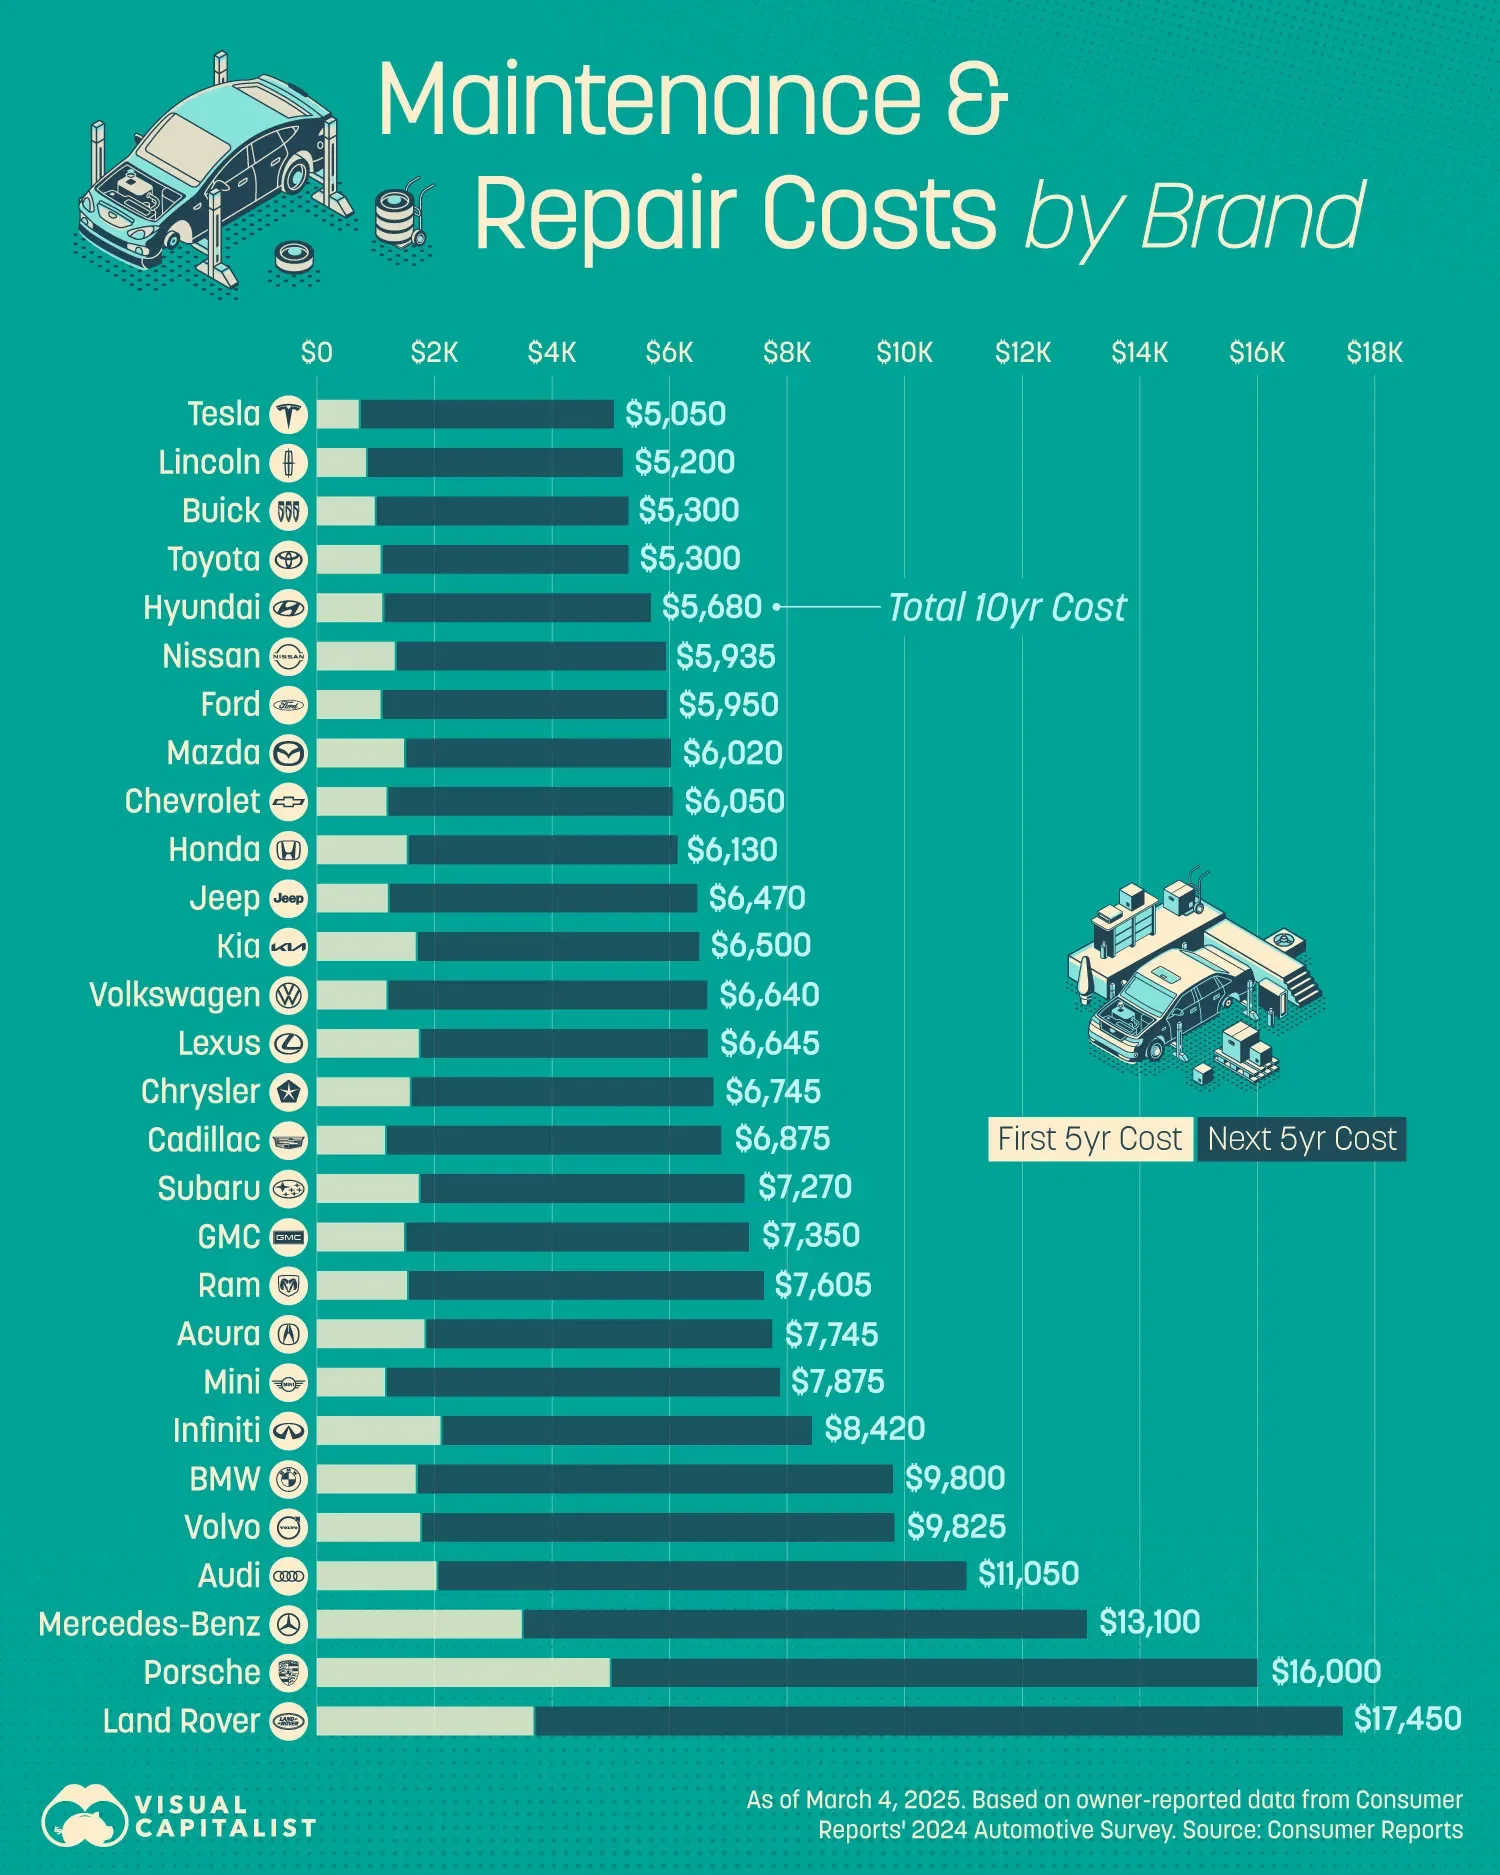
Start by choosing a vehicle with strong resale value and low depreciation (e.g., Toyota, Honda, or certified pre-owned models). Avoid luxury brands unless you can afford the long-term costs. Consider longer loan terms (if financing) to lower monthly payments, but ensure the total interest doesn’t inflate the car percentage of net worth. Finally, allocate savings from reduced car costs toward higher-yield investments.
Q: Does the type of car (electric, hybrid, gas) affect net worth?
Yes, but not just in fuel savings. Electric vehicles (EVs) often have higher upfront costs but lower maintenance and fuel expenses. Over time, this can improve net worth by reducing ongoing expenses. However, the car percentage of net worth still depends on the purchase price—so a £70,000 EV might not be sustainable for someone with a £150,000 net worth, even with lower running costs.
Q: What’s the biggest mistake people make with car percentage of net worth?
The biggest mistake is ignoring the opportunity cost. Many focus on monthly payments or sticker prices without calculating how the car’s total cost (depreciation + upkeep) affects their broader financial picture. For example, a £40,000 car might seem affordable at £600/month, but if it’s 30% of your net worth, the lost investment potential could cost you tens of thousands over a decade.
