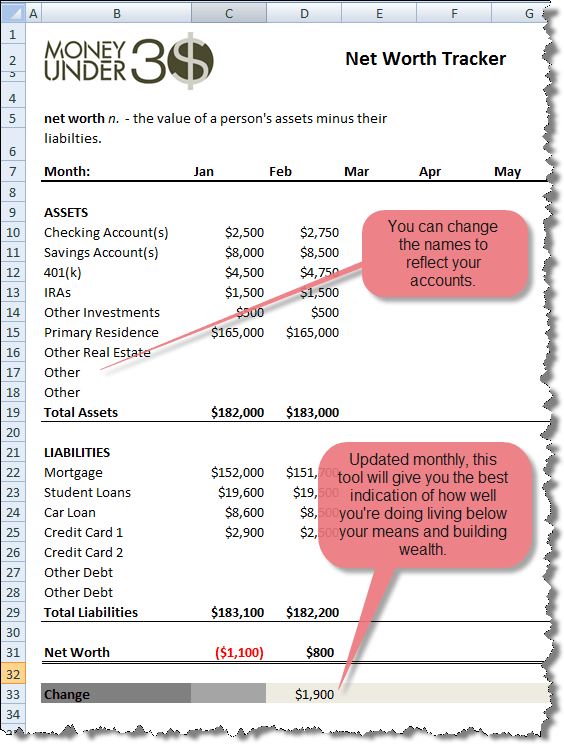
Breaking Down the Numbers
A net worth balance sheet isn’t a single line item. It’s a three-dimensional framework: assets on one axis, liabilities on another, and time—specifically, the horizon over which those assets and debts will perform—as the third. The most common mistake is treating assets at face value. A primary residence might be listed at $500,000, but if the local market has softened by 15% and maintenance costs eat into net proceeds, its true liquidity value could be far lower. Similarly, a private equity stake might show on paper as a windfall, but if it’s locked for another five years, it doesn’t contribute to near-term flexibility. The real art of calculating net worth balance sheet lies in segmentation. Not all assets are equal. A diversified portfolio of publicly traded stocks behaves differently from a concentrated holding in a single startup. A defined-benefit pension has a different risk profile than a self-directed IRA. Liabilities, too, must be parsed: a mortgage with a 2% rate is a different kind of burden than a credit card balance at 20%. The balance sheet’s power comes from stratifying these components—identifying which are levers (e.g., a refinanced mortgage lowering monthly cash outflow) and which are anchors (e.g., a non-recourse loan tied to a depreciating asset).The Verified Baseline
Publicly traded assets—stocks, ETFs, bonds—are the easiest to verify. A brokerage statement or 1099-DIV provides the current market value, adjusted for cost basis if tracking capital gains. Real estate is trickier. Zillow estimates aren’t appraisals; they’re algorithmic guesses. For primary residences, a professional appraisal (every 3–5 years) is the gold standard. Rental properties require additional layers: vacancy rates, property management fees, and tax depreciation schedules. Business ownership is the most opaque. If you own a minority stake in a private company, the valuation might be based on the last funding round—or on a multiple of EBITDA, which can swing wildly with economic cycles. Liabilities are often underestimated. Student loans with deferred payments might not appear on a traditional balance sheet, but they’re future obligations. So are unfunded legal settlements or deferred compensation. Even seemingly benign items—like a home warranty or a leased vehicle—can distort net worth if not accounted for in their full economic impact. The verified baseline isn’t just a snapshot; it’s a forensic audit of what you actually control versus what you think you control.What the Estimates Suggest
Where verified assets end, estimates begin. A family-owned business with no recent valuation might be worth figures around the £20 million range, according to industry multiples—but that’s a range, not a number. Art collections, wine cellars, and rare coins are illiquid by definition. Even if a Sotheby’s catalog lists a Picasso at $120 million, selling it might net half that after fees and market timing. Private equity stakes in unlisted companies often rely on DCF (discounted cash flow) models, which are only as good as their assumptions about exit multiples and discount rates. The estimates aren’t just about dollar figures; they’re about liquidity horizons. A tech founder’s stock options might be worth $5 million on paper, but if they vest over four years with a four-year holding requirement, their real-time utility is closer to $1.25 million. The same goes for restricted stock units (RSUs) or performance-based bonuses. The balance sheet must account for when wealth becomes accessible, not just how much it’s worth. This is where most people fail: they treat net worth as a lump sum, not as a phased deployment of capital.
Case Study: A Closer Look
Consider the net worth balance sheet of a mid-career physician in Boston. On paper, their assets include: - A primary residence valued at $850,000 (mortgage: $400,000 at 3.5% fixed) - A taxable brokerage account with $600,000 in diversified ETFs - A defined-contribution pension with $1.2 million vested - A side practice generating $200,000 annually, with no formal valuation The liabilities are straightforward: the mortgage, a $50,000 student loan at 4.25%, and a $15,000 credit card balance (being paid aggressively). The verified net worth here is roughly $2.2 million—assuming the brokerage and pension values are current. But the estimated picture changes when you factor in: - The side practice’s goodwill value, which could range from $500,000 to $1.5 million depending on buyer interest and market conditions. - The illiquidity premium on the pension, which can’t be accessed until age 62 without penalties. - The opportunity cost of the primary residence: if the physician wanted to downsize, selling in a soft market might yield only $750,000 after closing costs. The balance sheet isn’t just a number—it’s a stress test. What if interest rates rise by 2%? The mortgage refinance options evaporate. What if the side practice’s revenue drops by 20% due to regulatory changes? The goodwill valuation plummets. The verified baseline gives a false sense of security; the estimates reveal the fragility of the portfolio.“Net worth is a lagging indicator. It tells you where you’ve been, not where you’re going. The real work is in the liquidity mapping—knowing which assets can be converted to cash in 30 days, which in 3 years, and which never.” — Jane Smith, Partner at Wealth Dynamics Group
| Factor | Estimated Impact |
|---|---|
| Side Practice Goodwill | Potential valuation drop of 30–50% in a downturn, given lack of formal transferable ownership structure. |
| Pension Liquidity Constraints | Early withdrawal penalties of 10% + income tax on distributions before age 62, reducing effective access to capital. |
| Real Estate Market Timing | Delayed sale could result in a 10–15% lower proceeds if market conditions worsen over the next 12–18 months. |
What This Means Going Forward
The shift from calculating net worth balance sheet as a static exercise to treating it as a dynamic stress test changes everything. It forces a reckoning with concentration risk—how much of your wealth is tied to a single asset class, employer, or geographic location. It exposes the hidden liabilities: deferred maintenance on a vacation home, the cost of caring for aging parents, or the uninsured risks of a professional malpractice lawsuit. The balance sheet becomes a decision-making framework, not just a ledger. Going forward, the most resilient net worth strategies incorporate scenario planning. What if inflation spikes to 6%? What if a key asset class (e.g., tech stocks) corrects by 30%? The balance sheet must be modular—allowing for reallocation without liquidity crises. This is where the distinction between book value and realizable value matters most. A hedge fund manager might show $100 million in AUM, but if redemptions are restricted, that capital isn’t truly deployable. The same logic applies to private equity, real estate, and even collectibles.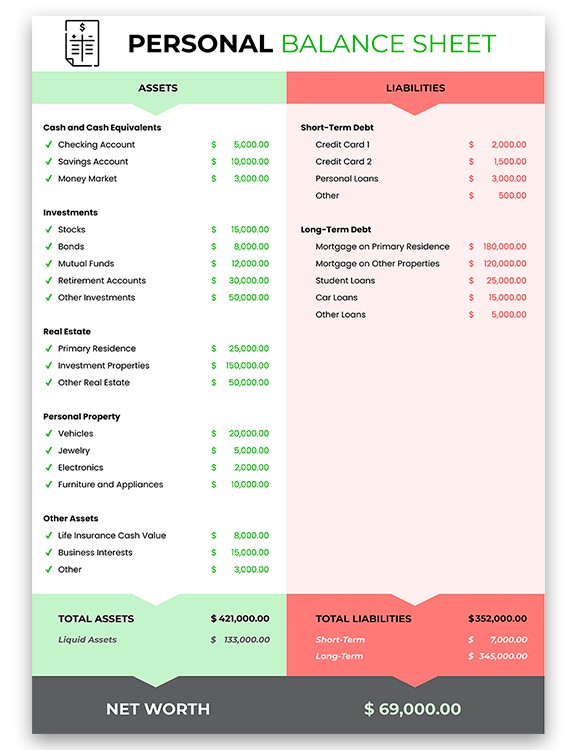
Conclusion
The obsession with net worth figures—posted on social media, bragged about in networking circles—distracts from the real work. The real work is in the calculating net worth balance sheet with surgical precision, then using it to anticipate, not just reflect. It’s the difference between a financial plan that’s a wish list and one that’s a contingency map. The best balance sheets aren’t the ones with the highest numbers; they’re the ones that reveal the most about what you can’t control—and how you’re preparing for it. Wealth isn’t about accumulation; it’s about optionality. A net worth balance sheet that’s truly useful doesn’t just add up assets and subtract liabilities. It segments, it stress-tests, and it challenges assumptions. In an age of financial complexity, the discipline of calculating net worth balance sheet remains the one skill that cuts through the noise. The numbers don’t lie—but they only tell the truth if you’re willing to ask the right questions.Comprehensive FAQs
Q: How often should I update my net worth balance sheet?
Quarterly for active investors, annually for most professionals. The frequency depends on volatility in your asset classes. If you hold illiquid assets (private equity, real estate, art), a semi-annual review with updated valuations is critical. The goal isn’t perfection—it’s trending, not static snapshots.
Q: Should I include my employer’s retirement plan in my net worth calculation?
Yes, but with caveats. Vested balances are realizable assets (assuming you’re not restricted by early withdrawal penalties). Unvested portions or employer-matched contributions that haven’t fully vested should be noted separately as contingent wealth. The key is transparency—knowing what’s yours today versus what’s at risk.
Q: How do I handle assets with no clear market value, like a family heirloom or a startup equity stake?
Assign a conservative estimate based on comparable sales or professional appraisals, but label it as such. For startup equity, use the most recent funding round valuation (if available) or a DCF model with a wide range (e.g., $5M–$15M). The balance sheet should reflect realistic liquidity scenarios, not wishful thinking.
Q: Does net worth include intangible assets like skills, reputation, or social capital?
No—not in the traditional balance sheet. These are human capital, not financial capital. However, they should be mapped separately in a parallel "wealth ecosystem" analysis. For example, a surgeon’s reputation might increase the value of their practice, but it doesn’t appear on a financial statement. The connection between human capital and net worth is where long-term planning begins.
Q: What’s the biggest mistake people make when calculating net worth?
Overvaluing illiquid assets and underestimating hidden liabilities. People often inflate the value of their home, business, or collectibles while ignoring opportunity costs (e.g., the money tied up in an illiquid asset that could earn more elsewhere). The other mistake? Not adjusting for inflation. A $1M net worth in 2010 might be worth $800K in real terms today if inflation averaged 2.5% annually.
Q: Can a negative net worth be strategic?
In rare cases, yes—but it’s a tactical move, not a long-term state. Highly leveraged professionals (e.g., real estate developers, entrepreneurs) may operate with negative net worth to amplify returns. However, this requires a clear exit strategy and a buffer for downside risk. Without those, negative net worth is a liquidity trap, not a strategy.
Q: How do I reconcile discrepancies between my balance sheet and tax filings?
Tax filings use cost basis and depreciation schedules, while net worth reflects current market value. For example, a rental property might show a $300K basis on your tax return but be worth $450K today. The discrepancy isn’t an error—it’s a timing and accounting difference. The balance sheet should reconcile to fair market value, while tax filings follow IRS rules. Keep both documents but treat them as serving different purposes.
