
Where It All Began
The origins of world balance net worth as a measurable concept trace back to the post-WWII reconstruction era, when economists first attempted to quantify the global asset gap. The Bretton Woods system wasn’t just about currency exchange rates; it was an experiment in forcing nations to account for their financial positions relative to one another. The Marshall Plan’s success hinged on one critical insight: a country’s net worth—its tangible assets minus debts—directly influenced its ability to borrow, trade, and project power. For the first time, wealth became a geopolitical currency. The early signs of this thinking emerged in the 1960s, when the World Bank began publishing International Financial Statistics, a dataset that, for the first time, cross-referenced national debt with private-sector wealth. The gap between what governments owed and what their citizens owned was staggering. In the U.S., corporate net worth outstripped GDP by nearly 30%. In Europe, family fortunes in Switzerland and Luxembourg dwarfed the combined assets of entire Eastern Bloc economies. The problem? No one was tracking how these private ledgers interacted with public ones. The world balance net worth wasn’t just a number—it was a fractal, where local imbalances amplified into global crises.The Early Signs
The first red flags appeared in the 1970s, when oil shocks revealed how vulnerable the system was to asset concentration. The 1973 embargo didn’t just spike gas prices; it triggered a chain reaction where OPEC nations’ sudden wealth surpluses distorted the global ledger. Saudi Arabia’s net worth ballooned overnight, while Western economies faced a choice: inflate their currencies (and devalue assets) or accept a new order where energy-rich states held disproportionate leverage. The solution? A temporary fix: petrodollar recycling, where oil revenues were funneled back into Western banks, masking the underlying imbalance. By the 1980s, the cracks widened. The Latin American debt crisis proved that a single region’s net worth collapse could ripple across continents. Mexico’s default in 1982 wasn’t just about sovereign debt—it was about the hidden liabilities of multinational corporations and the private banks that had lent them money. The IMF’s bailouts weren’t charity; they were an attempt to stabilize the world balance net worth by socializing losses. The message was clear: when one part of the system failed, the entire ledger trembled.The Turning Point
The moment world balance net worth became a household term—if not in name, then in effect—was the 2008 financial crisis. The collapse wasn’t just about subprime mortgages or Lehman Brothers. It was the audit of a lie: the global economy had been running on borrowed time, with private wealth inflated by debt, derivatives, and the assumption that assets would always appreciate. When the music stopped, the true world balance net worth was exposed. Trillions in paper wealth vanished. Pensions, home equity, and corporate balance sheets all took hits. The crisis wasn’t a correction—it was a reset. The turning point wasn’t the bailouts themselves, but the realization that wealth inequality wasn’t just a moral failing—it was a structural risk. The top 1% had seen their net worth grow by 60% in the decade leading up to 2008, while the bottom 90% stagnated. When the crash hit, the wealthy had diversified their assets into offshore accounts, gold, and real estate; the middle class had bet everything on housing. The imbalance wasn’t just economic—it was existential."Wealth isn’t distributed. It’s allocated—and the rules of allocation are written by those who already have it." — James Galbraith, economist, 2010
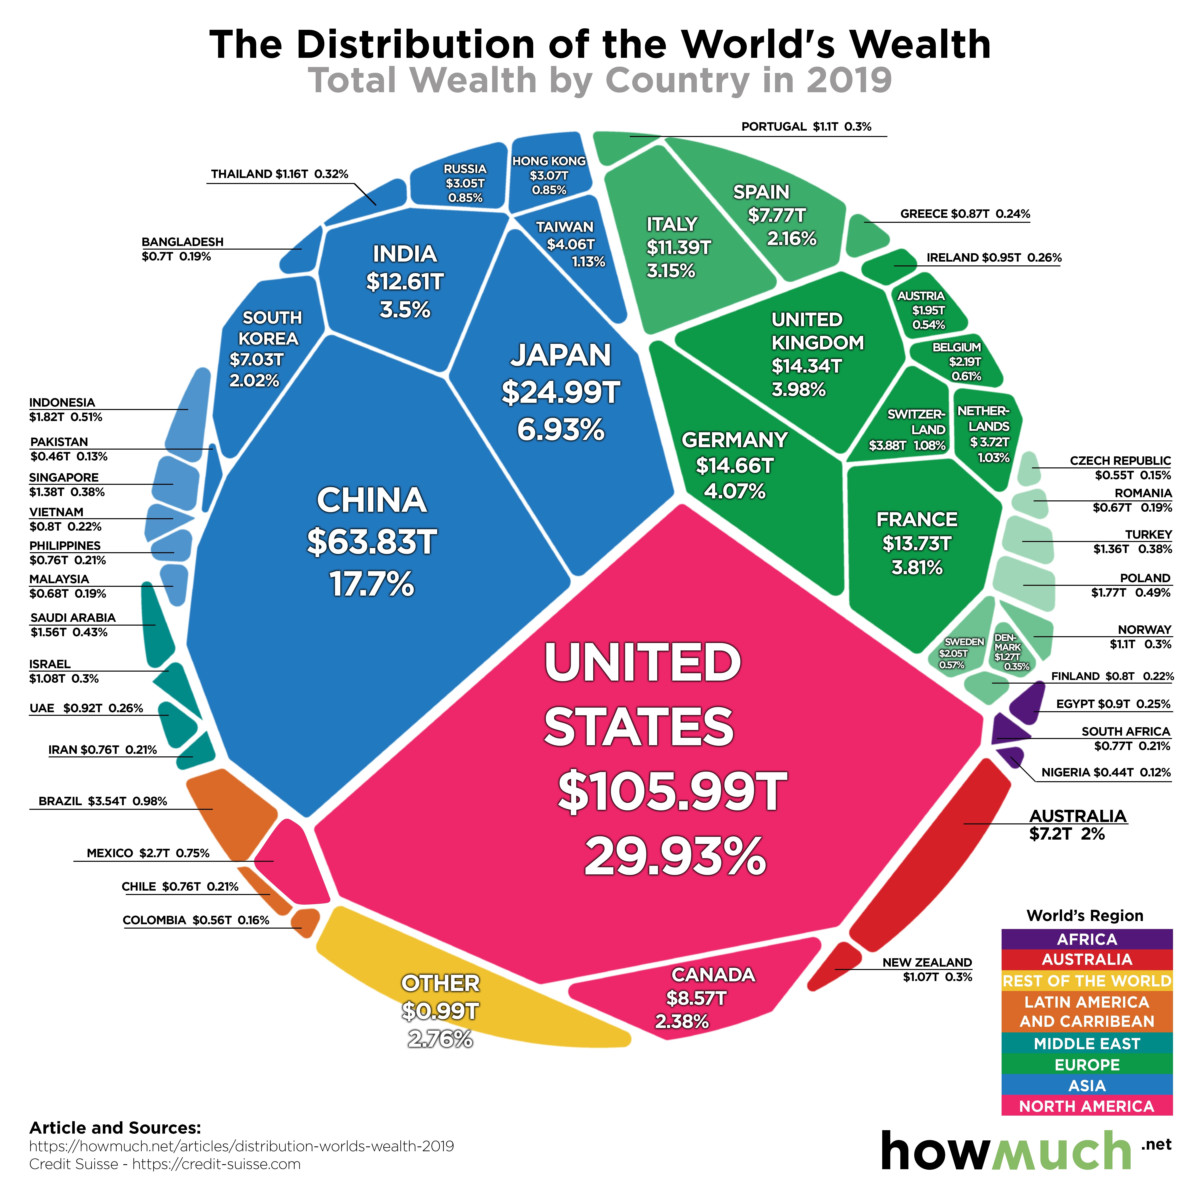
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1990s | Emergence of "global wealth management" firms (e.g., UBS, Credit Suisse) that helped ultra-high-net-worth individuals diversify across borders, exacerbating the world balance net worth gap. The rise of hedge funds and private equity further concentrated capital. |
| 2000s | Post-dot-com bubble, the world balance net worth became more opaque as wealth flowed into illiquid assets (private equity, real estate). The 2008 crisis revealed that national net worth figures were misleading—private debt was often hidden from public ledgers. |
| 2010s–Present | Tax havens and cryptocurrencies further fragmented the world balance net worth, making it harder to track. The COVID-19 pandemic accelerated wealth polarization: billionaires gained $4.1 trillion in 2020, while global poverty rose by 150 million. |
Lessons From the Journey
- Wealth isn’t neutral. The world balance net worth reflects power structures—who controls capital, who can access it, and who is excluded.
- Debt is the great equalizer—until it isn’t. When private debt outpaces economic growth, the system becomes unstable.
- Offshore accounts aren’t just tax avoidance—they’re wealth insulation. The ultra-rich protect their net worth from systemic shocks.
- Crisis reveals the truth. The 2008 crash and COVID-19 showed that when the world balance net worth is skewed, recessions hit the vulnerable first and hardest.
- The ledger is political. Every tax law, every bailout, and every central bank decision is a vote on how the world balance net worth is redistributed.
Where Things Stand Today
Today, the world balance net worth is a moving target. The pandemic accelerated trends that were already in motion: the rich got richer, the poor got poorer, and the middle class shrank. According to Credit Suisse’s 2023 Global Wealth Report, the top 1% now hold 43% of global wealth, up from 33% in 2000. Meanwhile, the bottom 50% own just 1.1%. The numbers aren’t just statistics—they’re a warning. The challenge isn’t measuring the imbalance. It’s addressing it without triggering a backlash. Governments have tried wealth taxes, inheritance reforms, and capital controls, but each solution faces the same obstacle: the world balance net worth is a global system, not a national one. A tax on billionaires in France won’t stop them from moving their assets to Singapore or the Cayman Islands. The only way to reshape the ledger is to rewrite the rules of the game—transparency, global cooperation, and a acknowledgment that wealth isn’t just a personal achievement. It’s a shared responsibility.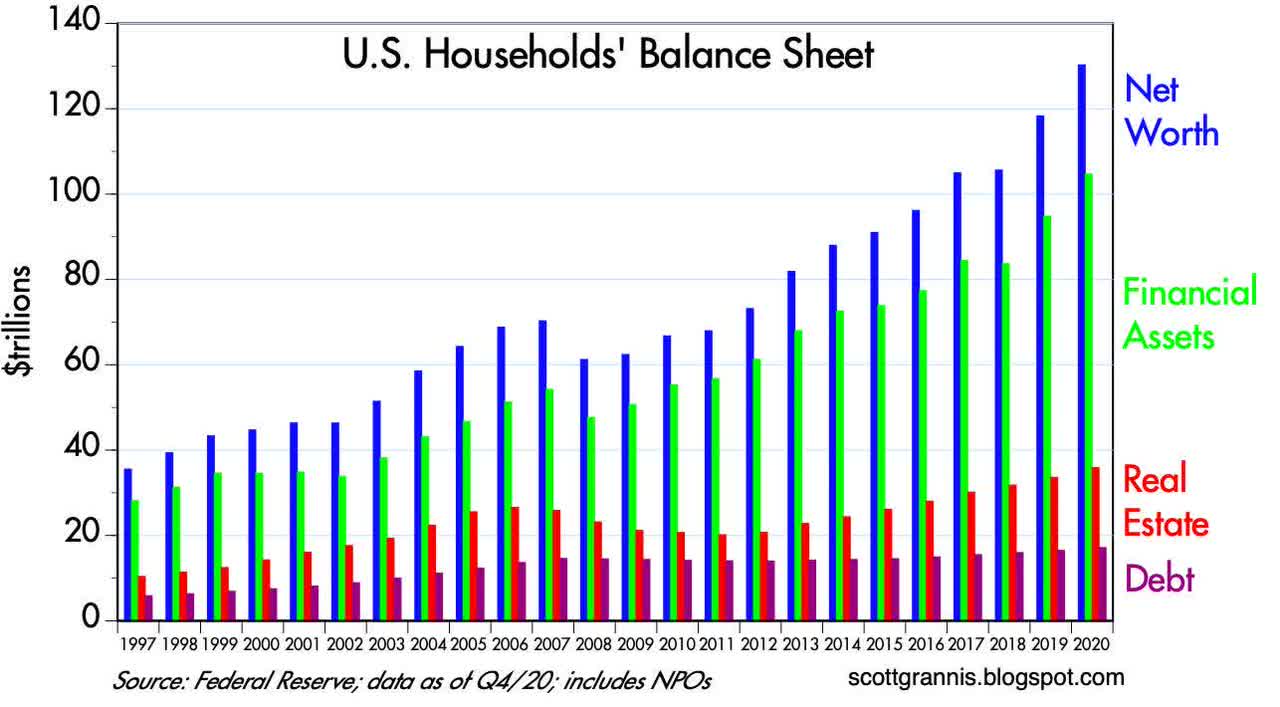
Conclusion
The story of world balance net worth is the story of modern capitalism: a system that rewards efficiency, innovation, and risk-taking—but only if you’re already at the top. The numbers don’t lie. The imbalance is real. And the question isn’t whether the system can be fixed. It’s whether the people who benefit from it will ever agree to change the rules. The alternative is simpler. Do nothing. Let the ledger keep tipping. Watch as wealth concentrates in fewer hands, as political power follows capital, and as the world balance net worth becomes less a measure of prosperity and more a divide between those who own the future and those who don’t.Comprehensive FAQs
Q: What exactly is world balance net worth?
The world balance net worth refers to the aggregate net worth of all individuals, corporations, and nations globally—calculated as total assets minus total liabilities. It’s a macroeconomic concept that highlights how wealth is distributed across borders, sectors, and social classes, often revealing hidden imbalances that traditional GDP measurements miss.
Q: How is world balance net worth different from GDP?
GDP measures economic output (goods and services produced), while world balance net worth measures net assets (what is owned minus what is owed). GDP can grow while net worth stagnates or decline—especially if debt rises faster than asset appreciation. For example, a country’s GDP might rise due to borrowing, but its world balance net worth could shrink if assets depreciate.
Q: Which countries have the highest world balance net worth per capita?
Switzerland, the U.S., and Luxembourg consistently rank at the top due to high private wealth, strong financial sectors, and favorable tax structures. However, per capita world balance net worth is often skewed by offshore wealth—many ultra-high-net-worth individuals hold assets in multiple jurisdictions, making precise rankings difficult.
Q: Can world balance net worth be negative?
Yes. A nation or individual can have a negative world balance net worth if liabilities exceed assets. This is common in highly indebted countries or during financial crises (e.g., Greece post-2010, or households with mortgages exceeding home values). Globally, negative net worth at the individual level contributes to systemic risk.
Q: How do tax havens affect world balance net worth?
Tax havens distort the world balance net worth by allowing wealth to be hidden from public ledgers. Estimates suggest $8–10 trillion in private wealth is held offshore, much of it by the top 0.01%. This capital isn’t "lost"—it’s reallocated, reducing tax revenues in high-tax nations while concentrating wealth in jurisdictions with lax regulations.
Q: Are there efforts to measure world balance net worth globally?
Yes, but inconsistently. The World Inequality Database, Credit Suisse’s Global Wealth Report, and Forbes’ billionaire lists provide partial snapshots. However, no single authority tracks the world balance net worth comprehensively due to data gaps, offshore secrecy, and the dynamic nature of wealth (e.g., cryptocurrencies, private equity). The IMF and OECD have proposed frameworks, but implementation lags.
Q: What would happen if the world balance net worth became more equal?
The effects would be profound. Economic studies suggest greater wealth equality could reduce inequality, boost consumer spending, and stabilize financial systems. However, redistribution risks backlash from wealth holders, capital flight, and political resistance. Historical examples (e.g., post-WWII Europe, Nordic models) show it’s possible—but requires strong institutions and global cooperation.
Q: Is world balance net worth a useful tool for policymakers?
Yes, but with limitations. It exposes structural imbalances that GDP ignores, such as debt bubbles, asset concentration, and wealth hoarding. Policymakers use it to design targeted interventions (e.g., wealth taxes, inheritance reforms). The challenge is political will—most governments prioritize growth over balance, even when the latter is more sustainable.
