
5 Things Worth Knowing About How Do You Know Your Net Worth
The process of determining your net worth isn’t linear. It’s a mix of arithmetic, psychology, and market reality. Here are five critical truths that separate the number from the noise.1. Net Worth Isn’t Just Assets Minus Debt—It’s a Time-Sensitive Equation
Most people learn the basic formula in high school: net worth = assets – liabilities. But that’s like saying a photograph captures a person’s entire life. The real question—how do you know your net worth—demands context. A $500,000 home might be an asset, but if it’s underwater on a mortgage and local property values are declining, its true value could be closer to $350,000. Similarly, a $200,000 retirement account balance looks impressive until you realize it’s in a fund that’s underperformed the S&P 500 by 3% annually for the past decade. The time dimension matters because assets aren’t static. A vintage wine collection might appreciate, but only if you hold it for 20 years. A rental property’s cash flow could dry up if tenants vanish during a recession. Even cash isn’t what it seems—$100,000 in a savings account today might buy less in five years due to inflation. The answer to how do you know your net worth isn’t a single snapshot; it’s a range of possibilities, weighted by probability. That’s why seasoned investors don’t just track net worth—they model scenarios. A tech founder might calculate net worth at three levels: worst-case (market crash), base-case (steady growth), and best-case (acquisition).2. Your "Assets" Section Is Probably Missing Critical Items (And Some You Shouldn’t Include)
People often overlook assets that don’t fit the "cash or easily sellable" mold. A freelance designer’s net worth might skyrocket if they include the value of their client list, but how do you quantify that? Industry estimates suggest a freelancer’s "goodwill" could add 20–50% to their net worth, but without a clear market for it, most exclude it entirely. Similarly, a stay-at-home parent’s net worth might be undervalued if they don’t account for the present value of childcare they provide—estimated at $180,000 per child over 18 years, according to a 2022 study by Salary.com. On the flip side, some "assets" should never appear on a net worth statement. Your timeshare? A liability in disguise, even if you paid it off. That collectible car you’ve owned for 15 years? Unless it’s a rare model with a verifiable market, its value is speculative. The IRS has strict rules on what counts as an asset for tax purposes, but personal finance isn’t tax law. The key is practicality: how do you know your net worth hinges on whether you could realistically sell an item today for its listed value. If the answer is "maybe, but it’ll take six months and cost me $5,000 in fees," it’s not a true asset.3. Liabilities Aren’t Just Loans—They’re Hidden Drain Pipes on Your Wealth
Debt is the obvious culprit, but liabilities extend beyond credit cards and mortgages. A lease agreement on a commercial space counts as a liability, even if you’re not technically "in debt." So does a legal settlement you’re obligated to pay, or a co-signed loan for a relative. The trickiest liabilities are the ones you don’t realize you have. For example, a joint account with a spouse or partner means your net worth is intertwined—even if you’re legally separate. Divorce statistics show that 40% of couples with joint accounts experience disputes over asset allocation, often because one partner underreported their share. Then there are opportunity costs—the financial equivalent of a black hole. The money you spent on a degree that didn’t lead to higher earnings? The salary you left on the table by quitting a job for a "better culture"? These aren’t liabilities in the traditional sense, but they erode your potential net worth. Calculating them requires looking backward: What could you have earned if you’d made different choices? For many, this exercise is more revealing than the raw numbers.4. Market Valuation Is a Moving Target—and Most People Guess Wrong
The biggest variable in how do you know your net worth is how you value your assets. A publicly traded stock? Easy—just check the ticker. A privately held company? Not so much. The valuation of a startup can swing by millions based on whether the next funding round succeeds. Real estate is even trickier: Zillow’s "Zestimate" is notoriously inaccurate, often off by 5–10% or more. In high-end markets, the gap can exceed 20%. The problem worsens with illiquid assets. A family-owned business might have a book value of $2 million, but if no one in the family wants to buy it, its real value could be $500,000. Art collectors face similar issues—how much is that Picasso worth if you need to sell it tomorrow? Auction houses provide estimates, but they’re often inflated to attract bidders. The answer to how do you know your net worth in these cases isn’t a number; it’s a range—and acknowledging that range is half the battle.5. Your Net Worth Statement Is a Lie Unless You Update It (And Most People Don’t)
A net worth statement is only useful if it’s current. Yet most people update theirs once a year—or never. Market fluctuations, new debts, and unexpected windfalls (or losses) can shift your net worth by 10% or more in a single quarter. A 2023 survey by the Financial Industry Regulatory Authority (FINRA) found that only 32% of Americans review their net worth annually, and just 12% do it quarterly. That’s like driving a car while looking in the rearview mirror every six months. The consequences are severe. Someone who stops tracking their net worth after a divorce might realize too late that their ex-spouse has been siphoning off assets. An investor who ignores a sudden dip in their 401(k) balance could miss the window to rebalance their portfolio. Even small inaccuracies compound. If you overestimate your home’s value by $50,000 and underestimate your credit card debt by $10,000, your net worth could be off by $60,000—a significant error if you’re applying for a loan or planning retirement.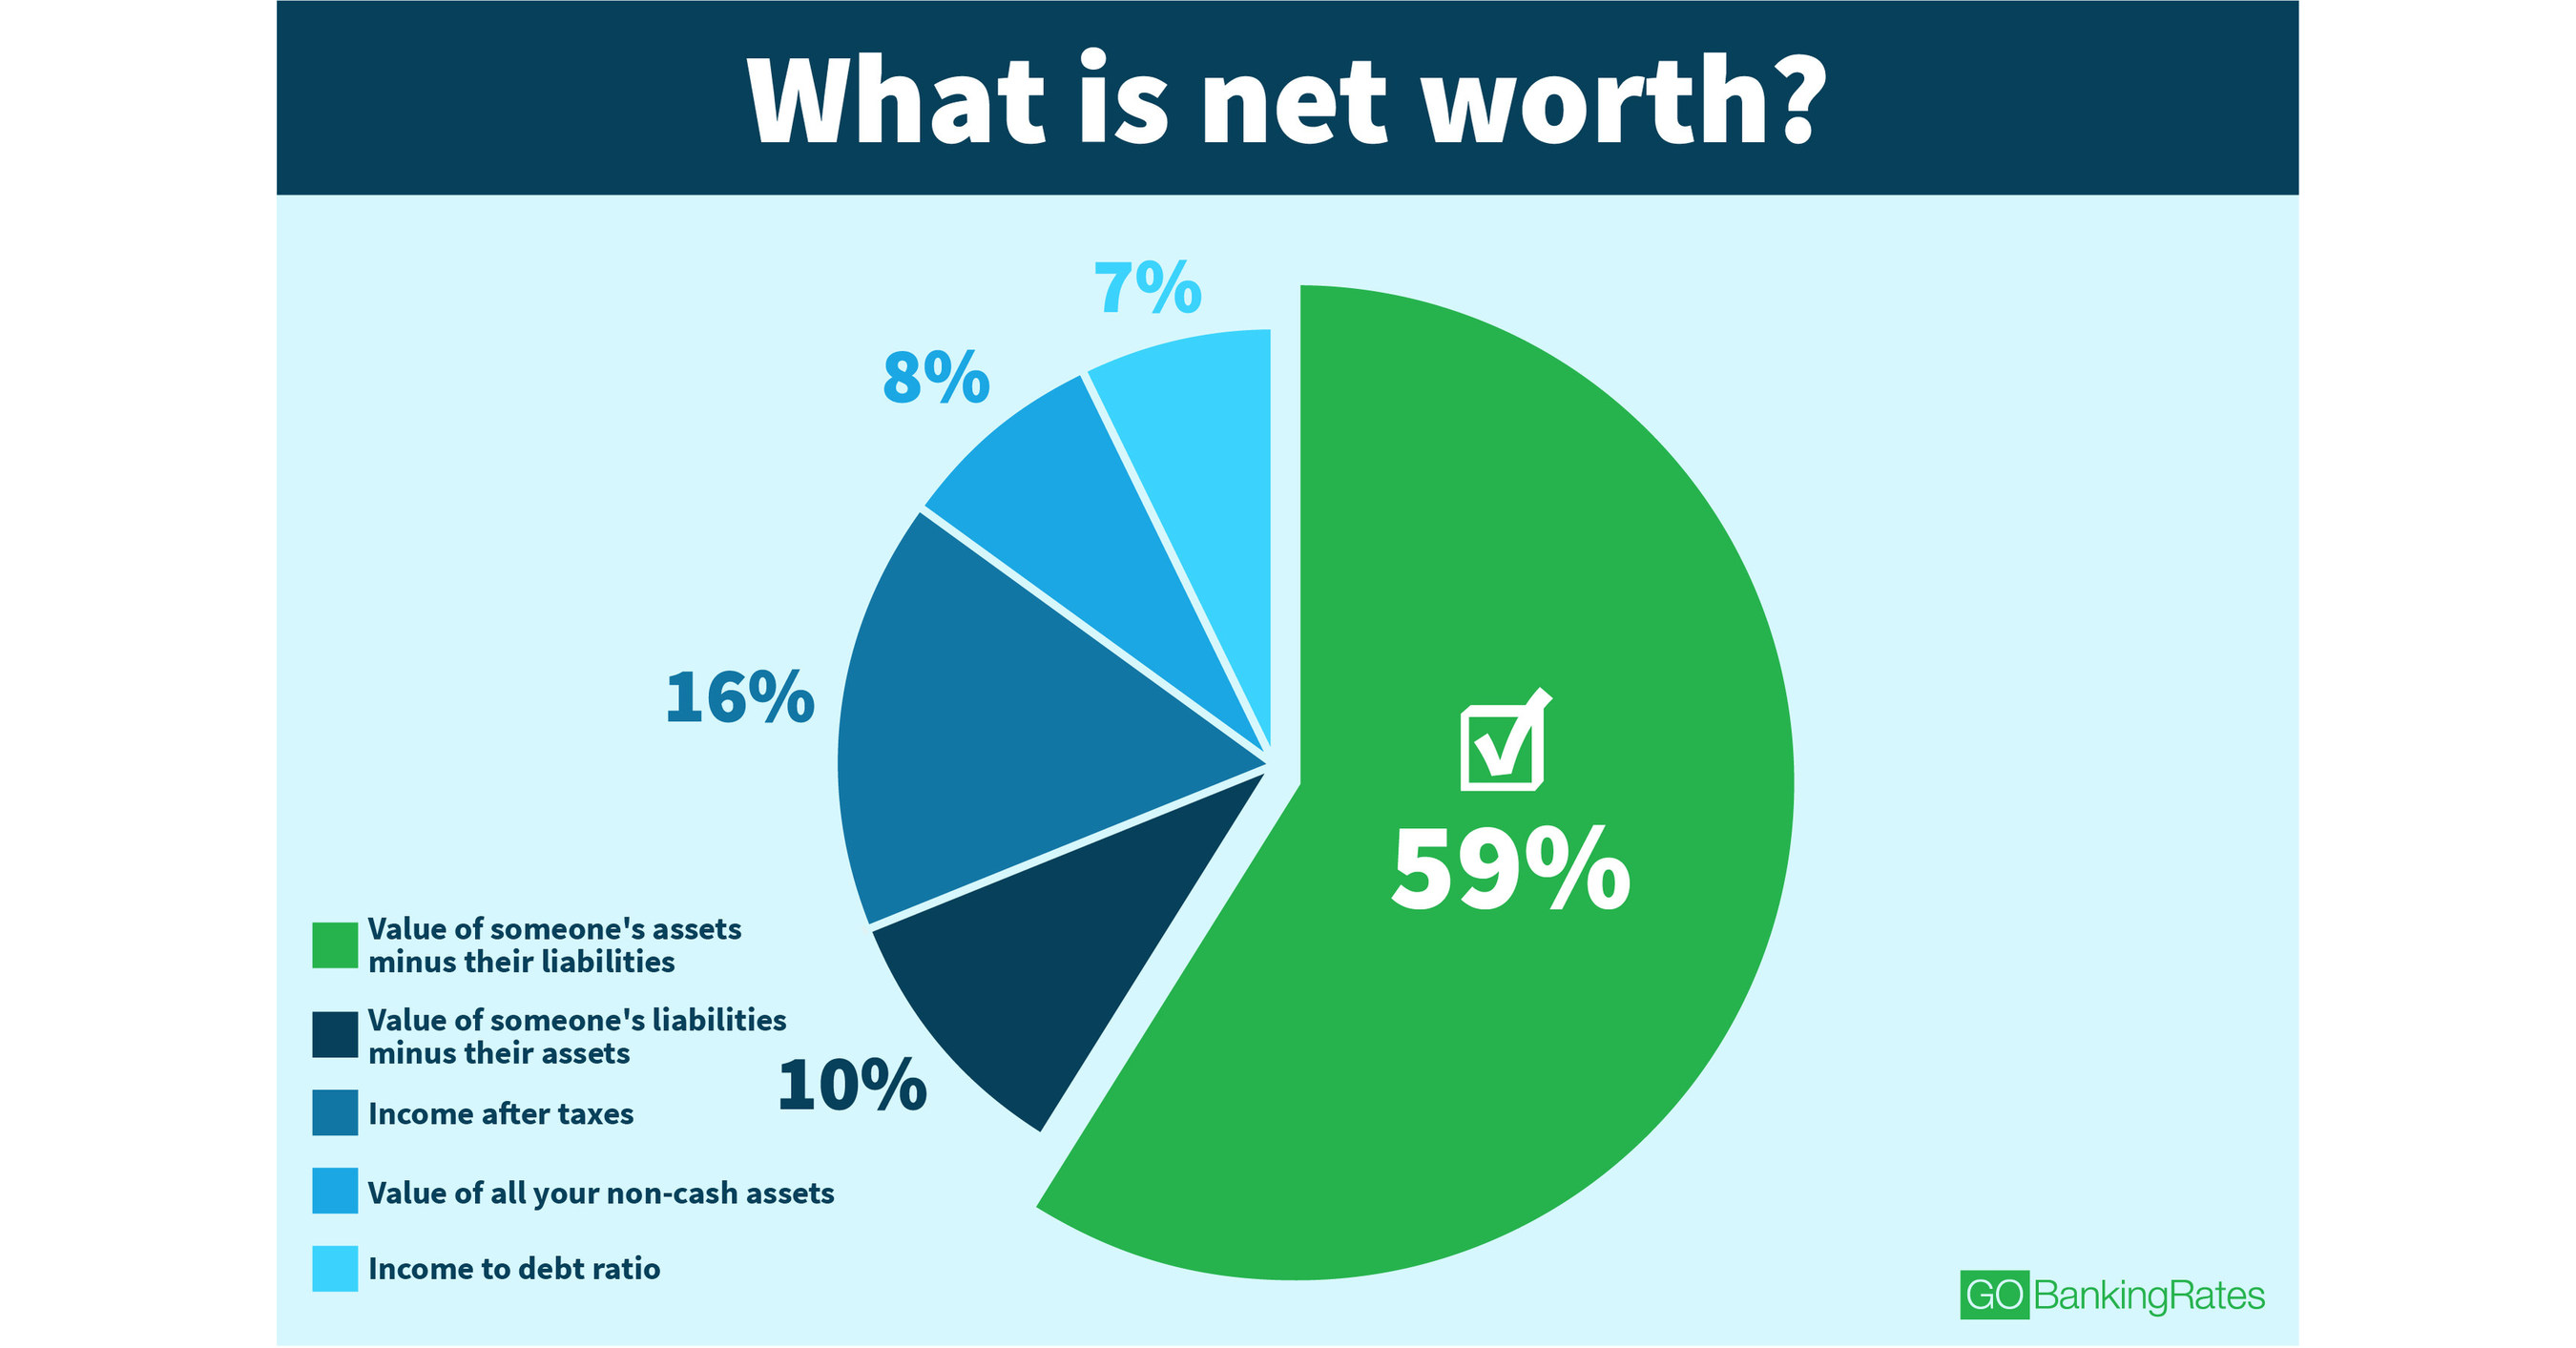
How These Facts Connect
The five truths above don’t exist in isolation. They’re threads in a single, messy tapestry that defines how do you know your net worth. The first truth—net worth as a time-sensitive equation—sets the stage for the others. If you don’t account for time, you’ll misjudge the value of assets and underestimate the drag of liabilities. The second and third truths reveal that the assets and debts you see are just the tip of the iceberg; the real work is in the hidden layers. The fourth truth forces you to confront uncertainty, while the fifth underscores that net worth isn’t a static target but a living, breathing metric. Together, they expose a harsh reality: knowing your net worth isn’t about crunching numbers—it’s about managing perception, risk, and behavior. A lawyer with a $3 million home might have a net worth of $1.2 million if their mortgage is $1.8 million. A small-business owner with $500,000 in equipment could be insolvent if their accounts receivable are uncollectible. The answer to how do you know your net worth isn’t a formula; it’s a process of continuous recalibration, where every life decision—from taking a pay cut for a better job to refinancing a loan—ripples through the equation.| Key Fact | What It Reveals | Common Mistake | How to Fix It |
|---|---|---|---|
| Net worth is time-sensitive | Assets and debts change value over time | Using static values (e.g., buying a house in 2010 and still valuing it at purchase price) | Reassess major assets annually; use inflation-adjusted benchmarks |
| Assets often go uncounted | Freelance goodwill, human capital, and illiquid assets add hidden value | Ignoring non-traditional assets (e.g., a loyal client base) | Consult industry-specific valuation guides (e.g., for freelancers, use revenue multiples) |
| Liabilities extend beyond debt | Opportunity costs and legal obligations erode wealth | Overlooking co-signed loans or joint accounts | Audit personal contracts; calculate forgone earnings |
| Market valuation is speculative | Private assets and real estate are often mispriced | Using Zillow estimates or emotional attachment values | Get professional appraisals for high-value items; use comparable sales data |
| Net worth statements become obsolete fast | Without updates, decisions are made with stale data | Reviewing net worth only during major life events | Set quarterly reminders; automate tracking with tools like Personal Capital |

Conclusion
The question how do you know your net worth isn’t just about addition and subtraction. It’s about confronting the gaps in your financial story—the assets you’ve never bothered to value, the debts you’ve buried in your mind, and the market realities you’d rather ignore. The process forces you to ask uncomfortable questions: Are you really as wealthy as you think? What would happen if your biggest asset suddenly lost half its value? Could you sell your home tomorrow without losing money? The answers matter more than the number itself. A precise net worth statement won’t prevent a recession, but it will help you weather one. It won’t guarantee success, but it will reveal where your blind spots lie. And in a world where financial stability is increasingly tied to adaptability, knowing your net worth isn’t just smart—it’s survival. The irony? The people who need to know their net worth most are often the ones who avoid calculating it. The freelancer drowning in irregular income. The homeowner who’s been paying a mortgage for 20 years but never checked their equity. The recent graduate with student loans and no clear path to asset growth. For them, the question how do you know your net worth isn’t academic—it’s a call to action. And the first step isn’t more spreadsheets. It’s the willingness to look closely at the numbers, even when they hurt.Comprehensive FAQs
Q: Do I need to include my car in my net worth calculation?
A: Only if it’s a high-value or classic vehicle with a verifiable market price. Most personal cars depreciate rapidly, and their resale value is often far below what you’d expect. For example, a 2018 Toyota Camry might have a book value of $15,000, but if you could only sell it for $8,000 after fees, its true net worth contribution is closer to $8,000. For everyday vehicles, many financial experts recommend excluding them unless they’re a significant portion of your total assets.
Q: How often should I update my net worth statement?
A: At a minimum, annually—but ideally, quarterly if your financial situation is volatile (e.g., you’re a freelancer, investor, or small-business owner). Market fluctuations, new debts, and unexpected income (like bonuses or tax refunds) can shift your net worth by thousands in a short time. Tools like Mint, YNAB, or Personal Capital can automate this process by syncing with your accounts, but even manual updates every three months will give you a clearer picture than an annual review.
Q: Should I count my retirement accounts (like a 401(k) or IRA) at their current balance or their potential future value?
A: Almost always at their current balance. While a 401(k) might grow to $2 million in retirement, its current value is what matters for your net worth today. The future value is speculative and depends on market returns, your contribution rate, and how long you hold the account—factors that can change dramatically. That said, if you’re close to retirement, you might adjust for expected growth rates (e.g., assuming 5% annual returns) to get a more realistic projection of your liquidity in the next 5–10 years.
Q: What if I don’t know the exact value of an asset, like a family heirloom or a small business I own?
A: Assign a conservative estimate based on comparable sales or professional appraisals. For a family heirloom, check auction records for similar items (e.g., on eBay or Sotheby’s) and deduct 20–30% for selling costs. For a small business, common valuation methods include revenue multiples (e.g., 2–4x annual profit) or asset-based valuation (adding up tangible assets like equipment and inventory). If you’re unsure, err on the side of underestimating—overvaluing assets can lead to poor financial decisions, like taking on more debt than you can handle.
Q: Does my net worth change if I take on a new loan, like a student loan or mortgage?
A: Yes, but not always in the way you’d expect. A new loan increases your liabilities, which directly reduces your net worth. However, if the loan funds an asset that appreciates (like a home or a degree that boosts your earning potential), the long-term impact on your net worth could be positive. For example, a $300,000 mortgage might lower your net worth today, but if the home appreciates by 3% annually and you build equity, your net worth could rise over time. The key is tracking both the immediate hit to your net worth and the potential future benefits.
Q: Can my net worth be negative? What does that mean?
A: Absolutely. A negative net worth means your liabilities exceed your assets. This is common for young adults with student loans, recent graduates with credit card debt, or business owners with high overhead. While a negative net worth isn’t ideal, it’s not necessarily a crisis—many people build wealth from this position by increasing income, reducing debt, or investing wisely. The danger comes when liabilities grow faster than assets, trapping you in a cycle of debt. For example, someone with $50,000 in assets and $100,000 in debt has a net worth of -$50,000, but if they can pay down debt and increase savings by $10,000 annually, they could flip to positive within five years.
Q: How does inflation affect my net worth over time?
A: Inflation erodes the purchasing power of your assets, especially cash and fixed-income investments like bonds. If your net worth statement shows $500,000 today, that same amount might only buy $400,000 worth of goods in five years at a 3% inflation rate. To adjust for inflation, some financial planners recommend tracking your net worth in "real" (inflation-adjusted) terms. For example, if your net worth grows by 5% annually but inflation is 3%, your real growth is only 2%. This is why diversifying into assets that historically outpace inflation—like stocks, real estate, or commodities—is critical for preserving long-term net worth.
Q: Should I share my net worth with anyone, like a partner or financial advisor?
A: Sharing your net worth depends on your goals and trust levels. With a partner, transparency is key—especially if you’re married or have joint finances. Disputes over hidden assets are a leading cause of divorce, so aligning on your net worth (and how you’ll grow it) can prevent conflicts. With a financial advisor, sharing your net worth helps them tailor advice, but be cautious—some advisors may push products that benefit them more than you. Always ask how they’ll use the information and whether they have a fiduciary duty to act in your best interest. For most people, starting with a broad overview (e.g., "My net worth is in the $200K–$300K range") is safer than revealing exact figures.
