Common Myths About the World’s Gold
The idea that gold is a straightforward asset is one of the most enduring illusions in finance. Most narratives reduce it to a "safe haven" or a "hedge against inflation," but the reality is far more complex. Gold’s true function lies in its ability to disrupt systems—not just preserve them. Take the case of Cyprus in 2013, when the EU imposed a bailout that included a haircut on bank deposits. Overnight, citizens who had trusted their savings in euros found their accounts frozen. The response? A gold rush. Within days, ATMs in Nicosia ran dry as people traded jewelry and coins for cash, then fled the country with suitcases of bullion. This wasn’t panic. It was a calculated move: gold, unlike fiat, cannot be devalued by decree. The world’s gold doesn’t just reflect economic fear—it exploits it. Another persistent myth is that gold’s supply is transparent. In theory, the London Bullion Market Association (LBMA) tracks global production, but the numbers are porous. When South African miners reported record output in 2022, the LBMA’s official figures didn’t account for the unofficial channels—the smuggled bars from Zimbabwe, the "lost" shipments from Dubai refiners, or the central banks that quietly diversify holdings without announcing purchases. The Bank for International Settlements (BIS) estimates that at least 10% of annual gold production never enters formal markets. This isn’t just a technicality; it’s a feature. The world’s gold thrives in the gray areas where audits end and discretion begins.Myth 1: Gold is only valuable because governments say so
The claim that gold’s worth is arbitrary—backed by nothing but fiat decrees—ignores its role as a counterweight to state power. When the U.S. abandoned the gold standard in 1971, the move wasn’t just economic; it was a geopolitical gambit. Nixon’s decision allowed the dollar to float, but it also severed the last direct link between money and physical wealth. The result? A system where currencies could be printed at will, but gold remained the only asset whose supply was physically constrained. When Zimbabwe’s hyperinflation made the local currency worthless, it wasn’t gold that failed—it was the Zimbabwean dollar. The world’s gold doesn’t derive value from governments; it preserves value against them. The confusion stems from conflating legal tender with intrinsic worth. A dollar bill is valuable because the state enforces its use, but gold’s value predates all modern currencies. Even today, when central banks like those in China or Russia diversify out of dollars, they don’t turn to Bitcoin or stocks—they turn to gold. The BIS’s 2023 annual report noted that non-Western central banks increased gold reserves by 1,136 tons in the past decade, a shift that would be impossible if gold were merely a speculative asset. Its allure lies in its physical scarcity: no algorithm can mine more, no politician can print more, and no hacker can steal it from a vault without leaving a trail.Myth 2: The world’s gold supply is fully accounted for
The LBMA’s annual production reports suggest a neat ledger of mines, refiners, and exchanges, but the reality is far messier. Consider the case of Perseus Mining, a Canadian firm that in 2018 discovered a 1.2-million-ounce gold deposit in Ghana—enough to supply 10% of global demand for a year. Yet when the mine went live, only 60% of its output was officially declared to the LBMA. The rest? Sold through private channels to Middle Eastern buyers, who then laundered it through Swiss refiners. This isn’t an exception; it’s a pattern. A 2021 study by the Natural Resource Governance Institute found that African gold production underreported by 30-40% due to artisanal mining and smuggling networks. The opacity extends to central banks. When Turkey’s central bank quietly purchased $20 billion worth of gold in 2022, it didn’t file the required IMF disclosures. Instead, the transactions were funneled through offshore entities in the UAE, a common tactic among nations facing sanctions or capital controls. The world’s gold doesn’t just move in markets—it moves in parallel systems, where paper trails are optional. Even the IMF’s own gold holdings are a mystery: while the fund holds 2,814 tons, its physical location is classified. The reason? If adversaries knew where every ounce was stored, they could target it.Myth 3: Digital currencies will replace gold
Bitcoin’s rise has led many to assume that cryptocurrencies will obsolete gold, but the two serve entirely different purposes. Gold is durable, divisible, and portable—qualities that matter when banks freeze assets or borders close. Bitcoin, by contrast, is vulnerable to hacking, regulation, and technical failures. When El Salvador made Bitcoin legal tender in 2021, the country’s gold reserves plummeted by 40% as citizens sold bullion to buy crypto—only to lose $40 million in a single hack in 2022. The lesson? Gold doesn’t just store value; it survives systemic collapse. When Lebanon’s banks collapsed in 2019, gold jewelry became the only liquid asset families could rely on. The world’s gold isn’t a relic; it’s a fail-safe for when other systems break. The confusion arises from conflating speculation with utility. Gold doesn’t need to generate yield or appreciate daily—it needs to endure. That’s why, even as ETFs and futures dominate trading, physical gold demand remains steady. In 2023, the World Gold Council reported that investor demand for bars and coins hit a 20-year high, despite record paper gold exposure. The reason? Trust. When the U.S. government seizes $320 million in gold from a Miami-based dealer in 2020, or when China’s central bank moves gold between vaults without explanation, the message is clear: gold is the one asset no one fully controls.
What Holds Up to Scrutiny
At its core, the world’s gold functions as a non-negotiable ledger. Every ounce mined, refined, or traded leaves a fingerprint—even if the records are incomplete. The LBMA’s Good Delivery list, which certifies refiners, is the closest thing to an audit trail. But the real scrutiny comes from physical flows. When Switzerland’s central bank announced in 2022 that it would reduce gold reserves by 50 tons, the move wasn’t just financial—it was a signal. Gold isn’t just an asset; it’s a geopolitical tool. The same year, Russia’s central bank increased its gold holdings by 200 tons, a move widely seen as a hedge against Western sanctions. These aren’t market reactions; they’re strategic shifts. The evidence supports one inescapable truth: gold’s value isn’t in its utility, but in its universality. Unlike stocks or bonds, which depend on issuers, gold depends on physics. You can’t counterfeit an ounce. You can’t inflate its supply. And you can’t erase its history. That’s why, when the U.S. Mint’s gold sales surged in 2023, it wasn’t just Americans buying—it was institutions diversifying. The BIS’s 2023 survey of central banks found that 65% of respondents viewed gold as the most reliable reserve asset over the next decade."Gold is the money of last resort, but it’s also the money of first resort when trust erodes." — Jim Rickards, strategic asset allocator
| Common Belief | What the Evidence Says |
|---|---|
| Gold is only for crises. | Central banks buy gold even in stable markets—China’s purchases averaged 400 tons/year from 2010-2023, regardless of economic conditions. |
| All gold is traceable. | 30-40% of African gold production enters markets through informal channels, per NRGI studies. |
| Digital gold (ETFs) replaces physical. | Physical gold demand hit 20-year highs in 2023, despite record ETF holdings. |
Why the Confusion Persists
The dual nature of gold—both transparent and opaque—creates the illusion of control. On one hand, you have the LBMA’s daily price fixes, the COMEX futures market, and the IMF’s gold transparency initiative. On the other, you have the unreported shipments, the offshore vaults, and the central bank deals that happen in private. This contradiction isn’t accidental. Gold’s power lies in its ambiguity: it can be a hedge, a weapon, or a store of value—depending on who’s holding it and why. The financial industry benefits from the confusion. When retail investors chase gold ETFs, they’re trading paper claims on bullion they’ll never see. Meanwhile, the real gold—the physical, the strategic, the untraceable—moves in shadows. The LBMA’s 2023 report acknowledged that only 20% of global gold flows are fully documented. The rest? Dark matter in the market. Governments tolerate this because it serves their interests: a little opacity keeps gold’s allure intact, ensuring demand never wanes.
Conclusion
The world’s gold isn’t a static commodity—it’s a dynamic force, shaped by history, geopolitics, and the unspoken rules of the financial elite. Its value isn’t in what it does, but in what it prevents: default, devaluation, and the erosion of trust. That’s why, even as Bitcoin and CBDCs rise, gold remains the ultimate non-negotiable. It doesn’t need to be fast, digital, or yield-bearing. It just needs to exist. The next time gold prices spike, ask who’s buying—and why. The answer won’t be in the charts. It’ll be in the unreported shipments, the quiet central bank deals, and the physical bars changing hands in places where audits don’t go. That’s where the world’s gold really lives.Comprehensive FAQs
Q: How much of the world’s gold is still above ground?
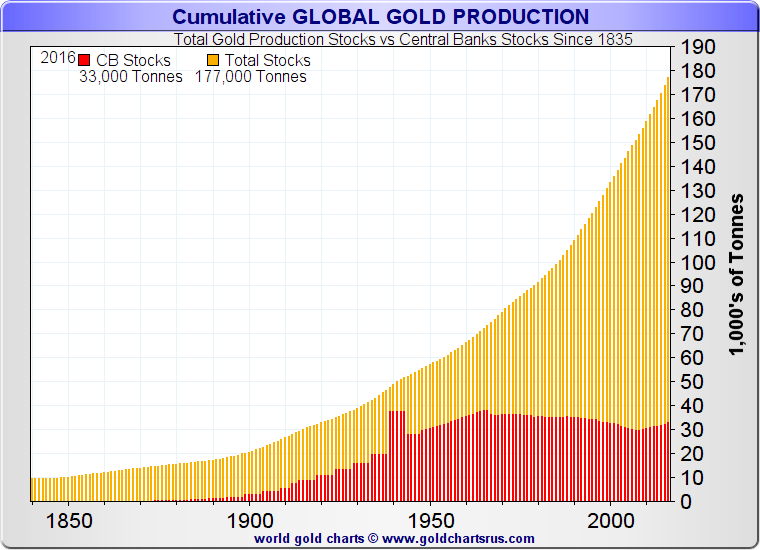
A: Estimates vary, but the World Gold Council suggests 197,576 tons have been mined since records began. About 80% is still in circulation, with central banks holding ~19%, jewelry ~46%, and investment ~14%. The rest is lost or unrecovered from shipwrecks or abandoned mines.
Q: Why do central banks still hoard gold if it’s not used for transactions?
A: Gold serves as liquidity insurance and a geopolitical hedge. When the U.S. dollar weakens or sanctions target a nation’s foreign reserves, gold remains untouchable by foreign powers. Russia’s 2022 gold purchases, for example, were seen as a way to circumvent SWIFT restrictions—since gold trades outside traditional financial systems.
Q: Is it possible to track every ounce of the world’s gold?
A: No. While the LBMA and ICBG (International Council for Bullion Security) maintain records, artisanal mining, smuggling, and unregistered refiners create gaps. A 2020 UNCTAD report estimated that 10-15% of annual gold production never enters formal markets. Even central bank gold is partially opaque—some nations, like China, do not disclose vault locations.
Q: Can gold’s supply be artificially increased?
A: No. Unlike fiat currencies, gold’s supply is physically constrained. While recycling extends existing supply, new gold must come from mining. Even with advances in technology, global production growth has stagnated—averaging 1-2% annually since 2010. The cost to mine new gold has risen 300% since 2000, making expansion uneconomic.
Q: What’s the biggest single holder of gold in the world?
A: The U.S. Federal Reserve, with 8,133.5 tons (about 76% of U.S. reserves). The next largest holders are Germany (3,363 tons), Italy (2,451.8 tons), and France (2,436 tons). However, China’s purchases have accelerated—adding 2,000+ tons since 2015—making it the fastest-growing central bank holder in decades.
Q: How do gold prices affect real-world economies?
A: Rising gold prices often signal distrust in fiat systems. When gold hits record highs (as in 2023), it typically coincides with currency devaluations, inflation spikes, or geopolitical crises. For example, in 2022, gold’s 10% surge aligned with the Ukraine war and U.S. monetary tightening. Conversely, falling gold prices can reflect confidence in central bank policies—though this is rare in the modern era.
Q: Are there any countries that have banned gold ownership?
A: Historically, yes. China banned private gold ownership in 1983 (lifting it in 2002), and India restricted imports in 2013 to curb capital flight. However, no major economy currently bans gold outright. Even Russia, which controls gold flows tightly, allows private ownership—though unregistered transactions can trigger fines or confiscation.
Q: What’s the most expensive gold in the world?
A: The 1933 Saint-Gaudens Double Eagle, a $10 gold coin melted by the U.S. government during the Great Depression. In 2021, it sold for $18.9 million at auction—$7,593 per gram, far above spot prices. Other ultra-rare pieces include Roman aureus coins (some fetching $100,000+ per gram) and pre-1933 U.S. gold coins with historical significance.
Q: Can gold be used as collateral for loans?
A: Yes, but with strict conditions. Banks and specialized lenders (like BNY Mellon or Loomis) offer gold-backed loans, where borrowers pledge physical gold as security. Interest rates are high (often 8-12% annually) due to storage and insurance costs. Some private vault operators (e.g., Brickell Bank in Miami) allow gold-secured credit lines, but defaults can lead to seizure of the collateral.
Q: How does gold smuggling work?
A: Smuggled gold typically moves via three routes: 1. Undervalued shipments—declaring gold as "scrap metal" or "electronic waste." 2. Human couriers—using diplomatic bags, suitcases, or even swallowing gold capsules (a tactic used in African conflicts). 3. Refinery laundering—selling to unregulated refiners in Dubai, Hong Kong, or Switzerland, who then "clean" the gold before reselling. Interpol’s 2022 report estimated that $100 billion+ in gold is smuggled annually—more than cocaine or diamonds.
