Where It All Began
The origins of tracking total US net worth as a share of GDP can be traced to the post-WWII era, when the Federal Reserve and Commerce Department began compiling comprehensive balance sheets. Before 1952, wealth data was patchy—relying on spotty tax records and incomplete corporate filings. The first systematic estimates came from the Survey of Current Business, a Commerce Department publication that later evolved into the Flow of Funds. These early reports showed that net worth was roughly 400% of GDP in the 1950s, a ratio that seemed stable until the 1980s. The turning point arrived with deregulation. When the Glass-Steagall Act was repealed in 1999 and the Commodity Futures Modernization Act followed in 2000, financial assets became more volatile—and more valuable. The Federal Reserve’s Financial Accounts of the United States (the successor to Flow of Funds) began tracking this shift in real time. By the early 2000s, the total US net worth as percentage of GDP federal reserve department of commerce had climbed to 550%, driven by a housing bubble and a stock market rally. Economists like Edward N. Wolff later noted that this wasn’t just growth—it was a structural change. Wealth was no longer concentrated in tangible assets like farms or factories; it was tied to paper claims: mortgages, derivatives, and equities.The Early Signs
The first red flags appeared in the late 1990s, when the Federal Reserve’s Financial Accounts showed that household debt was rising faster than incomes. By 2000, the total US net worth as percentage of GDP had hit a peak of 600% before the dot-com crash. The Commerce Department’s revised national accounts later confirmed that much of this wealth was illusory—based on inflated stock valuations. Yet the ratio didn’t collapse. Instead, it stabilized, as Americans leveraged their homes to rebuild portfolios. The real inflection came with the 2008 crisis. When Lehman Brothers failed, the total US net worth as percentage of GDP dropped by nearly 20 percentage points in a year. The Federal Reserve’s emergency lending programs and the Commerce Department’s stimulus adjustments prevented a total meltdown, but the damage was done. The ratio didn’t recover to pre-crisis levels until 2013, and even then, the composition had changed. Corporate net worth surged, while household wealth remained depressed—until the 2010s bull market in stocks and real estate restored confidence.The Turning Point
The moment the total US net worth as percentage of GDP federal reserve department of commerce became a household term was 2017. That’s when the Federal Reserve’s Z.1 report showed the ratio had surpassed 600% for the first time since the dot-com era. The Commerce Department’s National Income and Product Accounts later confirmed that this wasn’t a fluke—it was the result of a decade-long wealth effect. Low interest rates, corporate buybacks, and a rising stock market had collectively inflated asset values beyond GDP growth. What made this different was the speed. In the past, such spikes took generations; now, they happened in decades. The Federal Reserve’s Financial Accounts revealed that by 2019, the top 1% of households held nearly 35% of all US financial assets, while the bottom 50% held just 2.6%. The total US net worth as percentage of GDP wasn’t just growing—it was concentrating."Wealth inequality isn’t a bug of capitalism; it’s a feature. And the Federal Reserve’s data confirms that the rich aren’t just getting richer—they’re getting richer faster than the economy itself." —Edward N. Wolff, New York University economistThe pandemic accelerated this trend. When COVID-19 hit, the Federal Reserve’s balance sheet expanded by $7 trillion in months, injecting liquidity into markets. The Commerce Department’s revised GDP estimates later showed that while output shrank in 2020, net worth didn’t just recover—it soared. By mid-2021, the total US net worth as percentage of GDP had hit 700%, a level not seen since the 1920s.

The Build-Up, Year by Year
| Period | Key Event |
|---|---|
| 1980s–1990s | Deregulation and financial innovation boosted asset valuations. The Federal Reserve’s Flow of Funds first highlighted the rising total US net worth as percentage of GDP. |
| 2000–2007 | The housing bubble and stock market rally pushed the ratio to 600%. The Commerce Department’s national accounts later showed much of this growth was debt-fueled. |
| 2008–2012 | The financial crisis caused a 20% drop in the ratio. The Federal Reserve’s emergency measures stabilized markets, but recovery was uneven. |
| 2013–2021 | Corporate buybacks, low rates, and asset inflation drove the ratio to 700%. The Commerce Department’s revised GDP figures confirmed this was the highest level in a century. |
Lessons From the Journey
- The ratio isn’t just about growth—it’s about distribution. When the total US net worth as percentage of GDP federal reserve department of commerce rises, it often reflects asset bubbles more than real economic expansion.
- Debt distortions matter. The 2008 crash proved that leveraged wealth can evaporate quickly, even if GDP remains resilient.
- Policy responses shape the ratio. The Federal Reserve’s QE programs and the Commerce Department’s stimulus adjustments directly influenced post-crisis recovery.
- Global shocks amplify inequality. The pandemic’s wealth surge showed that crises can widen gaps faster than they lift all boats.
Where Things Stand Today
As of 2024, the total US net worth as percentage of GDP hovers around 750%, according to the latest Federal Reserve Z.1 report. The Commerce Department’s National Income and Product Accounts confirm that this isn’t a temporary spike—it’s a new baseline. Corporate net worth now accounts for nearly 40% of the total, while household wealth has stabilized but remains concentrated among the top 10%. The question isn’t whether the ratio will keep rising—it’s whether it reflects sustainable growth or another bubble. The Federal Reserve’s balance sheet remains bloated, and the Commerce Department’s GDP revisions suggest that much of the recent increase in net worth is tied to financial assets, not productivity. If interest rates stay elevated, the ratio could contract. But if another asset boom emerges, it could climb further—leaving inequality as the only constant.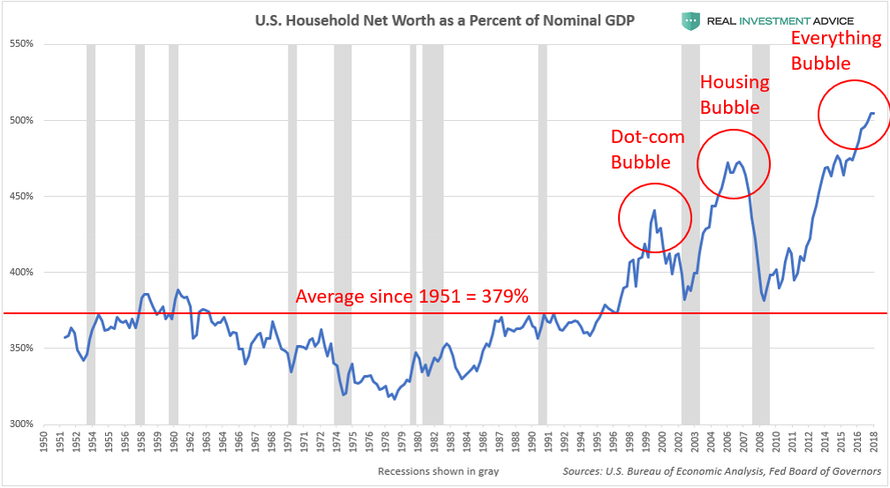
Conclusion
The total US net worth as percentage of GDP federal reserve department of commerce is more than a statistic—it’s a narrative of how wealth is created, destroyed, and redistributed. From the deregulation of the 1980s to the pandemic-era stimulus, each phase has reshaped this ratio, often in ways that benefit a small slice of the population. The Federal Reserve and Commerce Department’s data provide the raw numbers, but the story behind them—of bubbles, bailouts, and booms—is what matters most. For policymakers, the lesson is clear: tracking this ratio isn’t just about measuring economic health—it’s about anticipating the next crisis. For ordinary Americans, it’s a reminder that prosperity isn’t evenly distributed. The total US net worth as percentage of GDP may be at record highs, but without structural changes, the divide between those who own assets and those who don’t will only widen.Comprehensive FAQs
Q: Why does the Federal Reserve track net worth as a percentage of GDP?
The total US net worth as percentage of GDP federal reserve department of commerce helps assess financial stability. A high ratio can signal asset bubbles, while a sharp drop may indicate distress. The Fed uses this metric to gauge systemic risk, especially in leveraged markets.
Q: How does the Commerce Department’s GDP data affect these calculations?
The Commerce Department’s National Income and Product Accounts provide the denominator (GDP) for the ratio. Revisions to GDP—such as adjustments for inflation or productivity—directly impact how the total US net worth as percentage of GDP is interpreted. For example, if GDP growth is revised upward, the ratio may appear lower than initially reported.
Q: Can this ratio ever drop below 500%?
Historically, the ratio has rarely fallen below 500% since the 1950s. Even during the Great Depression, it stayed above 450%. A sustained drop would require a severe asset crash or a prolonged recession, neither of which has occurred in modern history.
Q: Who benefits most when the ratio rises?
The total US net worth as percentage of GDP rising primarily benefits asset holders—particularly those in the top 10%. Stock and real estate owners see their wealth grow faster than GDP, while wage earners often see minimal gains. The Federal Reserve’s data shows that inequality tends to widen during periods of high net worth growth.
Q: How does this compare to other developed nations?
The US total US net worth as percentage of GDP federal reserve department of commerce is higher than most peers, partly due to its larger financial sector. Japan’s ratio is similar but more volatile, while Europe’s is lower, reflecting less asset concentration. The Federal Reserve’s global comparisons show the US leads in wealth-to-GDP ratios, though not always in economic stability.
