Common Myths About Disney Studios’ Net Worth
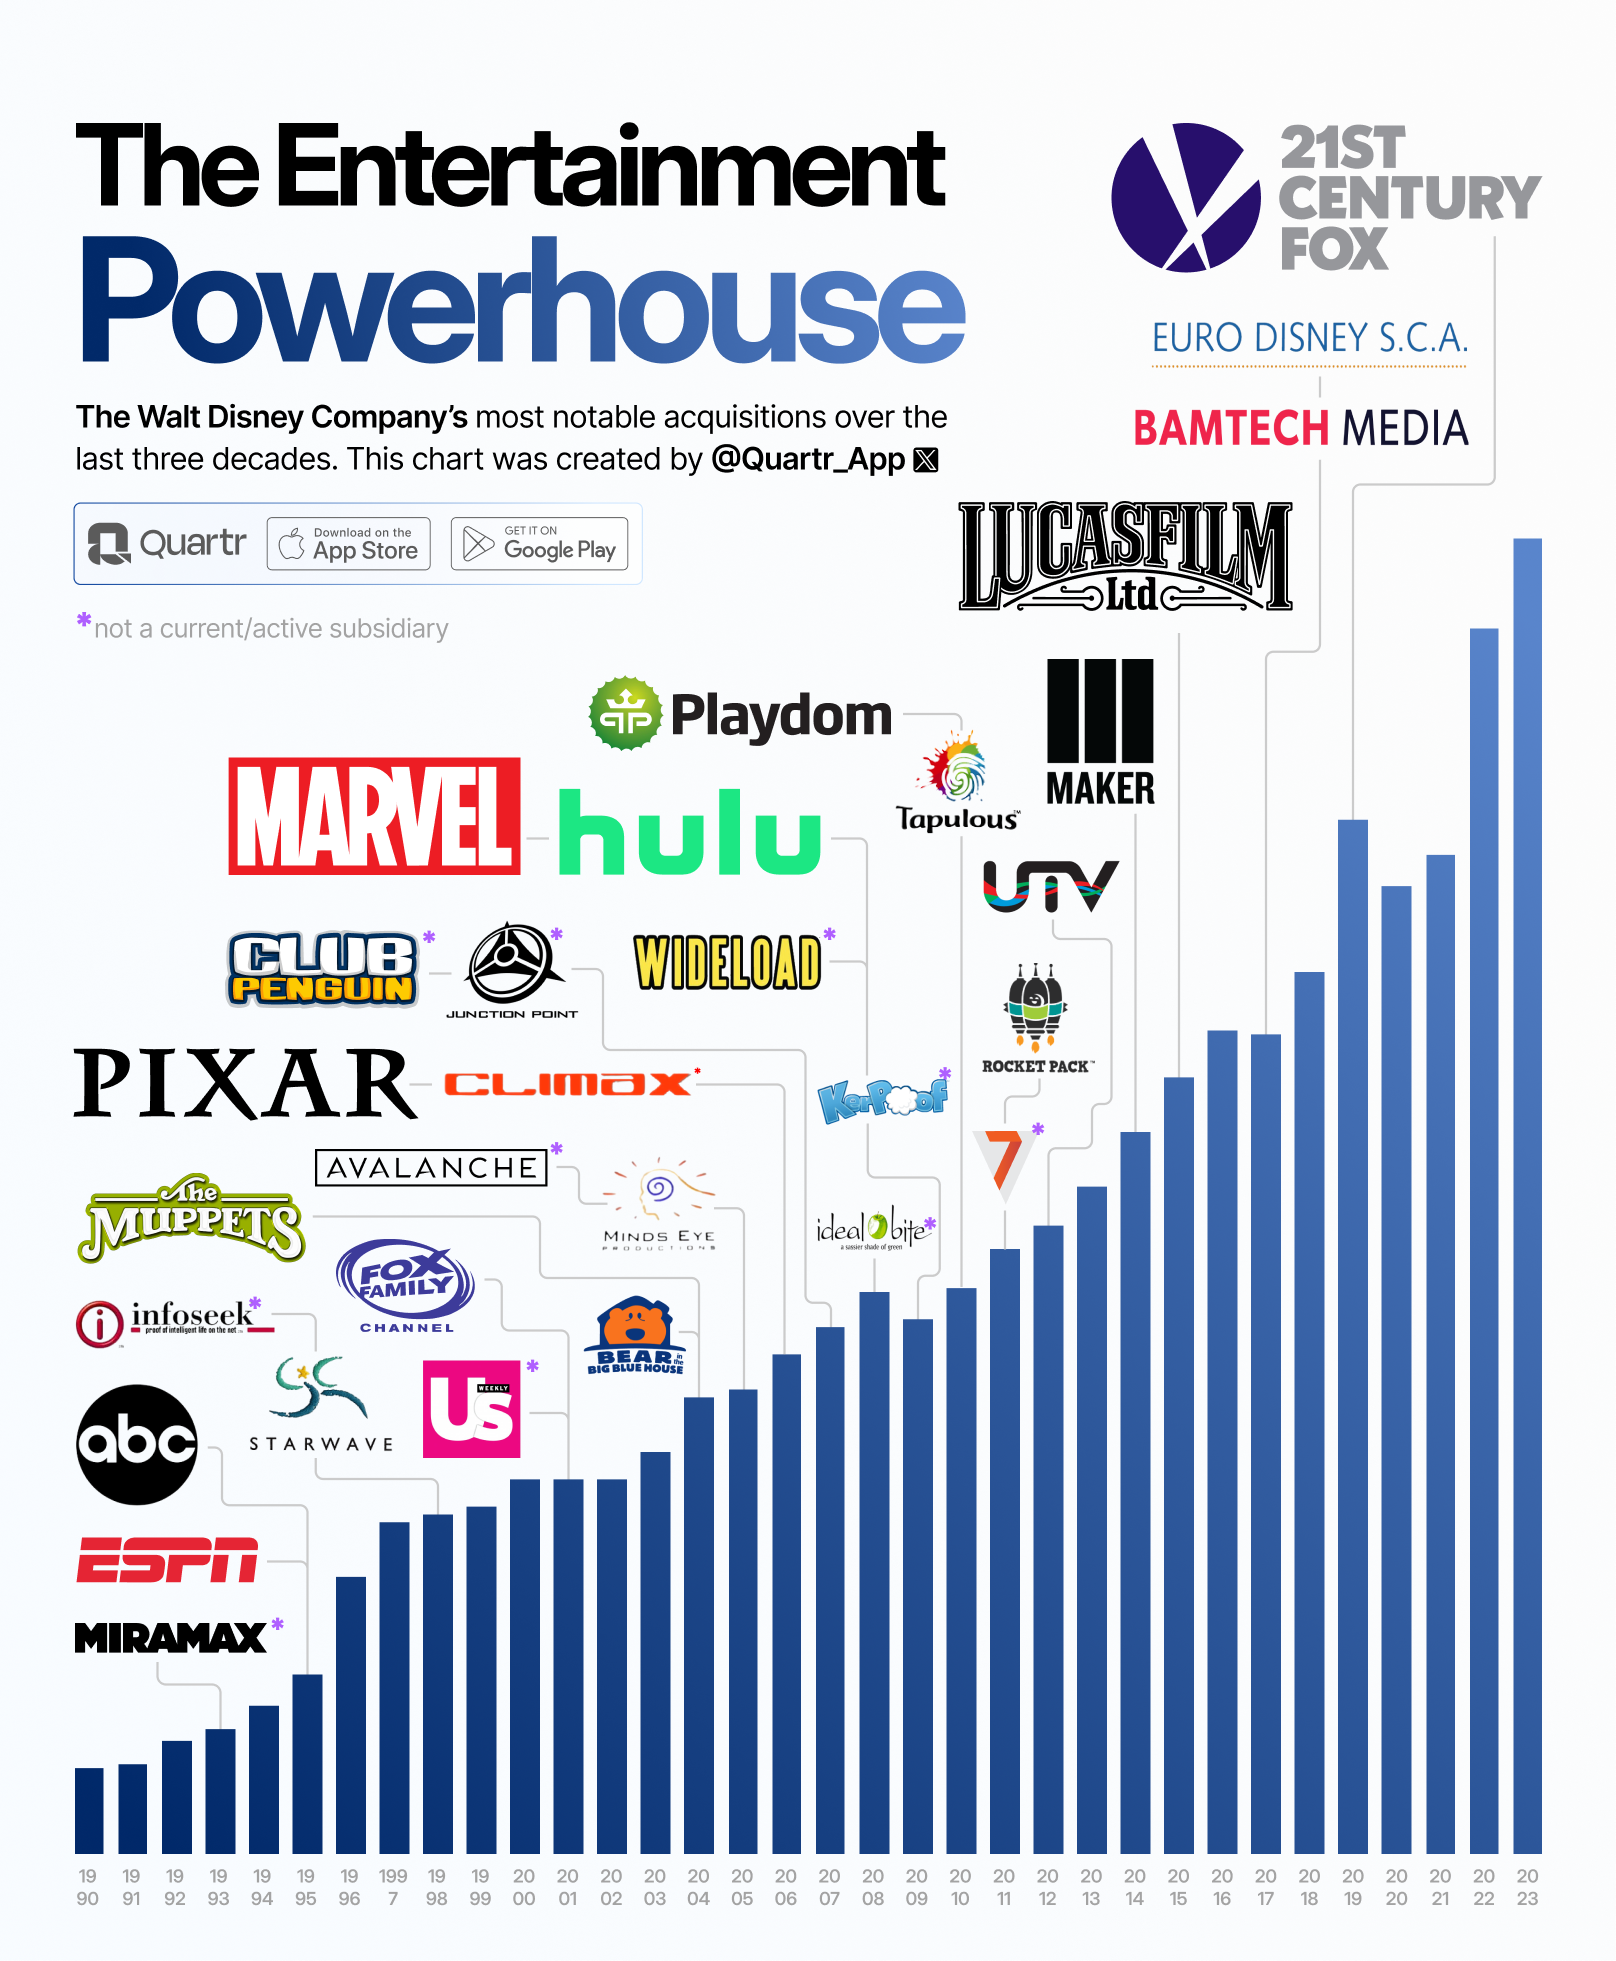
The first misconception treats Disney Studios’ net worth as synonymous with Disney’s overall market valuation. While the company’s stock price—peaking near $200 billion in 2021—reflects investor confidence, it includes theme parks, consumer products, and international operations. The studio division alone accounts for roughly 20–25% of Disney’s total revenue, but its profitability is tied to a mix of theatrical releases, home entertainment, and ancillary rights. Separating the studio’s financials requires parsing segment reports, which Disney only began disclosing in detail after 2019. Before that, analysts had to reverse-engineer figures from broader disclosures, leading to wild estimates. Another persistent myth frames Disney Studios as a "money-printing machine" due to its franchise dominance. While Marvel, Star Wars, and Pixar generate billions, their success is offset by the cost of developing new IP, marketing campaigns, and the rising salaries of talent amid industry-wide labor shortages. The studio’s reported net income for fiscal 2023 was around $1.5 billion, but that figure includes losses from underperforming films like The Little Mermaid (2023) and the write-downs from its struggling streaming division, Disney+. The studio’s net worth isn’t just about box-office gross—it’s about the balance between blockbusters and the hidden costs of maintaining a global content factory.Myth 1: Disney Studios’ net worth is purely tied to box-office revenue
The assumption that Disney Studios’ net worth rises or falls with ticket sales ignores the division’s diversified revenue streams. Theatrical releases account for roughly 40% of the studio’s income, but the remaining 60% comes from home entertainment (streaming, DVDs, digital sales), merchandising, licensing, and international distribution deals. For example, Frozen (2013) earned over $1.2 billion at the box office but generated an estimated $10 billion+ in total revenue across all channels by 2023—including theme park rides, consumer products, and global licensing. The studio’s net worth is thus a function of its ability to monetize IP across platforms, not just opening-weekend hauls. Moreover, box-office performance doesn’t always correlate with profitability. A film like The Lion King (2019) recouped its production costs quickly but faced competition from Disney’s own Frozen II, diluting its market share. Meanwhile, mid-budget films like Encanto (2021) became cultural phenomena with minimal marketing spend, proving that Disney Studios’ net worth is as much about efficiency as it is about gross earnings. Analysts at Coalition Green note that the studio’s true value lies in its "franchise flywheel"—where each successful film fuels the next, from sequels to spin-offs.Myth 2: The studio’s net worth is declining because of streaming losses
Disney’s foray into streaming—particularly Disney+—has dominated headlines, but the narrative that it’s dragging down Disney Studios’ net worth oversimplifies the studio’s financial strategy. While Disney+ reported a net loss of over $3 billion in 2022, the platform is viewed as a long-term investment to retain subscribers and justify higher licensing fees for studio content. The studio’s film division, however, remains profitable: in fiscal 2023, Disney Studios reported a net income of $1.5 billion, with theatrical and home entertainment revenue reaching $11.3 billion. The key distinction is that streaming losses are often offset by increased demand for Disney’s IP, which the studio then monetizes through traditional channels. Critics argue that Disney’s aggressive content spending on streaming—such as the $1 billion+ investment in The Mandalorian and Star Wars exclusives—could strain the studio’s net worth in the short term. However, industry reports from MoffettNathanson suggest that Disney’s streaming strategy is designed to enhance the value of its existing franchises, not replace them. For instance, Marvel films on Disney+ (like WandaVision) drive interest in theatrical releases, creating a virtuous cycle. The studio’s net worth isn’t eroded by streaming; it’s being redefined by it.Myth 3: Disney Studios’ net worth is opaque because the company hides its numbers
While Disney’s financial disclosures are more transparent than in past decades, the company’s segment reporting still blends studio performance with other divisions. For example, Disney’s "Media Networks" segment includes ESPN and ABC, while "Studio Entertainment" encompasses film, television, and streaming. This bundling makes it difficult to isolate Disney Studios’ net worth without additional analysis. However, the opacity isn’t intentional malfeasance—it’s a byproduct of how Disney’s business model operates. The studio’s revenue is intertwined with its theme parks (e.g., Star Wars: Galaxy’s Edge boosts Star Wars film sales) and consumer products (e.g., Toy Story merchandise drives toy sales). To mitigate this, financial researchers like Evercore ISI use proxy metrics, such as the studio’s operating income margin (reported at ~20% in recent years) and its share of Disney’s total cash flow. While not a perfect measure of Disney Studios’ net worth, these figures provide a clearer picture than headline-grabbing losses from Disney+. The company’s 2023 10-K filing, for instance, revealed that the studio’s operating income was $2.1 billion, up from $1.8 billion in 2022—a sign of resilience despite industry-wide challenges.
What Holds Up to Scrutiny
At its core, Disney Studios’ net worth is underpinned by three verifiable pillars: its franchise portfolio, its global distribution infrastructure, and its ability to convert content into multiple revenue streams. The studio’s most valuable assets aren’t its buildings or equipment but its intellectual property—Marvel, Star Wars, Pixar, and Disney Animation—which generate recurring revenue through sequels, spin-offs, and merchandising. A 2022 report by Sanford C. Bernstein estimated that Marvel alone contributes over $10 billion annually to Disney’s revenue, with Star Wars adding another $5 billion. These franchises aren’t just cash cows; they’re financial moats that protect the studio’s net worth from competitive threats. The second pillar is Disney’s vertical integration. Unlike independent studios that rely on third-party distributors, Disney controls its own theaters (via Disney Theatrical Group), streaming platforms (Disney+, Hulu), and international subsidiaries. This integration allows the studio to maximize profits from a single film across multiple channels. For example, Avatar: The Way of Water (2022) earned $2.3 billion at the box office but generated an additional $1 billion+ from home entertainment and ancillary rights. The studio’s net worth is thus a reflection of its ability to extract value from every phase of a film’s lifecycle."Disney’s studio division is less about individual films and more about the ecosystem they support. The net worth of Disney Studios isn’t measured in a single quarter’s earnings but in the longevity of its franchises and their ability to adapt to changing consumer habits." — James McQuivey, Principal Analyst at Forrester Research
| Common Belief | What the Evidence Says |
|---|---|
| Disney Studios’ net worth is shrinking due to streaming losses. | The studio’s theatrical and home entertainment revenue grew 5% YoY in 2023, while streaming losses are offset by higher subscriber retention and licensing fees. |
| The studio’s value is solely tied to box-office performance. | Only ~40% of Disney Studios’ revenue comes from theaters; the rest is derived from licensing, merchandising, and international distribution. |
| Disney hides its studio finances to obscure poor performance. | While segment reporting blends divisions, the studio’s operating income has remained stable (~$2 billion annually) despite industry-wide challenges. |
Why the Confusion Persists
The primary source of confusion around Disney Studios’ net worth is the company’s dual role as both a content creator and a media conglomerate. Disney’s studio division doesn’t operate in isolation; it’s part of a larger machine that includes theme parks, broadcasting, and retail. This interconnectedness makes it difficult to attribute financial outcomes solely to the studio. For instance, a hit film like Black Panther (2018) benefits not only the studio but also Disney’s consumer products division (e.g., Black Panther merchandise) and its international subsidiaries (e.g., higher licensing fees in Africa). Additionally, the rise of streaming has blurred the lines between what was once a clear revenue model. Traditional metrics like box-office gross no longer tell the full story, as films like The Mandalorian generate value primarily through streaming subscriptions rather than ticket sales. This shift has forced analysts to adopt new frameworks for evaluating Disney Studios’ net worth, such as "content valuation multiples" (CVM), which assess the long-term value of IP rather than short-term earnings. The transition isn’t seamless, and missteps—like overestimating Disney+’s subscriber growth—have contributed to the noise around the studio’s financial health.
Conclusion
The reality of Disney Studios’ net worth is more complex than the headlines suggest. While the studio faces challenges—rising production costs, labor disputes, and the pressures of maintaining franchise dominance—its financial foundation remains robust. The key to understanding its value lies in recognizing that Disney Studios isn’t just a film producer; it’s a global entertainment ecosystem where every dollar spent on a Star Wars film or Marvel series ripples across multiple revenue streams. The studio’s net worth isn’t a static number but a dynamic interplay of IP, distribution, and consumer behavior. For investors, the takeaway is clear: Disney’s studio division is a high-risk, high-reward venture, but its long-term resilience is tied to its ability to innovate within its existing franchises. The company’s 2024 strategy—focused on expanding Marvel and Star Wars while integrating streaming and theme parks—suggests a deliberate effort to future-proof its net worth. Whether that strategy succeeds will depend on execution, but the studio’s track record offers reason for cautious optimism.Comprehensive FAQs
Q: How is Disney Studios’ net worth different from Disney’s total net worth?
The studio division represents roughly 20–25% of Disney’s total revenue but is only one segment of the company’s broader operations. Disney’s net worth includes theme parks, broadcasting (ESPN, ABC), and consumer products, while the studio’s net worth is specifically tied to film, television, and streaming content. For example, Disney’s market cap fluctuates with stock performance, whereas the studio’s value is assessed through operating income and IP valuation.
Q: Does Disney Studios report its net worth separately from the rest of Disney?
No, Disney does not disclose a standalone net worth for its studio division. The company reports segment revenue and operating income in its annual filings, but the studio’s net worth (assets minus liabilities) is not broken out separately. Analysts estimate the studio’s value by examining its cash flow, franchise valuations, and segment performance relative to Disney’s total financials.
Q: How do streaming losses affect Disney Studios’ net worth?
Streaming losses (e.g., Disney+’s net losses) are not directly subtracted from the studio’s net worth but are factored into Disney’s overall financial health. The studio benefits from streaming in two ways: first, by retaining subscribers who consume its content (reducing piracy and boosting ancillary revenue), and second, by using streaming as a marketing tool for theatrical releases. While Disney+ reported losses in 2022–2023, the platform is expected to turn profitable by 2024, which would positively impact the studio’s long-term net worth.
Q: What are the biggest revenue drivers for Disney Studios’ net worth?
The studio’s net worth is primarily driven by:
- Franchise IP (Marvel, Star Wars, Pixar, Disney Animation) – these generate recurring revenue through sequels, spin-offs, and merchandising.
- Home entertainment (streaming, DVDs, digital sales) – accounting for ~30% of studio revenue.
- International distribution – Disney’s global subsidiaries (e.g., Disney Studios India, Walt Disney Studios Motion Pictures) capture a significant share of non-U.S. revenue.
- Licensing and partnerships – deals with retailers, theme parks, and tech companies (e.g., Disney+ integrations with Apple TV) add billions annually.
Q: Has Disney Studios’ net worth declined in recent years?
Not in absolute terms, but the perception of decline stems from two factors: (1) increased transparency around streaming losses (which are often conflated with studio performance), and (2) the high costs of developing new IP amid inflation and labor shortages. However, the studio’s operating income has remained stable (~$2 billion annually), and its franchise valuations continue to grow. The real challenge is maintaining profitability amid rising production budgets (e.g., Avatar 3 reportedly cost $350–400 million) and the shift toward higher streaming investments.
Q: Can Disney Studios’ net worth be accurately estimated?
While exact figures aren’t publicly available, industry analysts use several methods to estimate Disney Studios’ net worth:
- Segment operating income – Disney reports the studio’s net income (e.g., $1.5 billion in 2023) as part of its "Studio Entertainment" segment.
- IP valuation models – Firms like Brand Finance estimate the value of Disney’s top franchises (e.g., Marvel at $30+ billion) and attribute a portion to the studio.
- Cash flow analysis – By examining the studio’s free cash flow (reported at ~$3 billion in 2023), analysts can infer its liquidity and long-term sustainability.
Q: How do labor strikes (e.g., SAG-AFTRA) impact Disney Studios’ net worth?
Labor disputes directly threaten the studio’s net worth by disrupting production schedules, increasing costs (e.g., higher wages for remaining talent), and delaying releases. The 2023 SAG-AFTRA strike, for example, led Disney to pause filming on projects like The Mandalorian and Star Wars sequels, costing an estimated $200–300 million in lost production time. Additionally, strikes can erode investor confidence, as seen in Disney’s stock drop during the 2023 negotiations. However, the studio’s deep IP reserves and vertical integration help mitigate long-term damage, as it can repurpose existing content (e.g., releasing The Little Mermaid on Disney+ during the strike).
