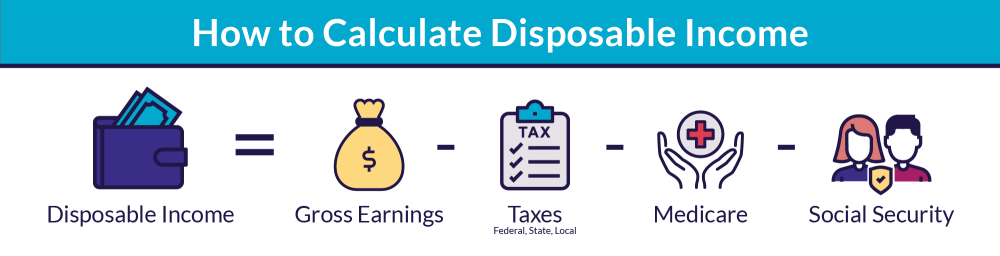
Common Myths About the difference between disposable income and household net worth
The most persistent myth is that a high disposable income automatically translates to strong net worth. This assumption ignores the fact that disposable income reflects spending power in the present, while net worth is a snapshot of accumulated assets minus liabilities. Someone earning £80,000 annually might have £3,000 left each month after expenses—but if they’ve spent decades on consumer debt and renting, their net worth could be negligible. Conversely, a retiree living on £25,000 a year might have a net worth of £500,000 thanks to decades of homeownership and savings. The two metrics move on different timelines, and conflating them leads to poor financial strategies. Another widespread misconception is that net worth is the better indicator of financial health for everyone. While net worth is undeniably important for long-term security, it’s meaningless if your disposable income can’t cover basic living costs. A young professional with a six-figure net worth from inherited property but no job might face foreclosure if they can’t afford the mortgage payments. Meanwhile, a service worker with modest net worth but stable disposable income can weather emergencies without dipping into savings. The difference between disposable income and household net worth becomes especially stark during economic downturns, when one metric might plummet while the other remains resilient—or vice versa.Myth 1: "If my disposable income is high, my net worth must be growing"
This is the financial equivalent of assuming that because you’re spending freely now, your future self will be wealthy. Disposable income is the fuel for today’s lifestyle; net worth is the result of how that fuel has been allocated over time. A high disposable income can fund lavish spending, frequent travel, or even aggressive debt repayment—but it doesn’t guarantee asset accumulation. In fact, studies show that households with the highest disposable incomes often have the lowest net worth growth when those funds are directed toward non-appreciating expenses like luxury goods or status symbols. The reverse isn’t always true either. Someone with modest disposable income might still build significant net worth by prioritizing investments, homeownership, or low-debt living. The key variable isn’t income alone but how disposable income is deployed—whether toward assets (stocks, real estate, retirement accounts) or liabilities (consumer debt, depreciating purchases). The myth persists because disposable income is the metric most people can grasp immediately, while net worth requires tracking assets and debts over years or decades.Myth 2: "Net worth is only important for the wealthy"
This overlooks the fact that net worth is a cumulative measure—meaning even small, consistent contributions can compound over time. A young adult with £5,000 in savings and £20,000 in student loans has a negative net worth, but that doesn’t make the concept irrelevant. For them, tracking net worth becomes a roadmap to financial independence, showing how every debt repayment or savings deposit improves their position. Meanwhile, someone with a £1 million net worth but no disposable income faces liquidity crises if they can’t cover living expenses. The difference between disposable income and household net worth becomes a matter of survival for middle-class households. A family earning £60,000 might have a net worth of £150,000—enough to weather a job loss—but if their disposable income is stretched thin by childcare costs, that buffer means little. Net worth isn’t a luxury; it’s a safety net that matters at every income level, even if its growth appears slow in the early stages.Myth 3: "Disposable income is the same as savings"
Disposable income is what remains after fixed obligations; savings is what you choose to do with that remainder. Someone with £2,000 in disposable income might save £500 or spend it all. The two terms are frequently used synonymously in headlines, but the distinction is critical. Disposable income is a flow—money coming in and out each month—while savings is a stock, the accumulated result of past decisions. Relying on disposable income for long-term planning is like using a paycheck to predict retirement security; it ignores the compounding power of consistent saving and investing. The confusion arises because savings rates are often calculated using disposable income as the denominator. A household saving 15% of their disposable income might still have zero net worth if they’re not investing those savings wisely. The difference between disposable income and household net worth highlights why tracking both is essential: one tells you how much you can spend today; the other tells you whether you’re building wealth for tomorrow.
What Holds Up to Scrutiny
At its core, the difference between disposable income and household net worth boils down to two economic principles: liquidity and asset accumulation. Disposable income measures your ability to meet current needs and wants without dipping into long-term resources. It’s the cash flow that funds your daily life, and its stability is what allows you to plan for short-term goals like vacations or home repairs. Net worth, by contrast, is a measure of your total financial position—what you own minus what you owe. It’s the sum of all your assets (cash, investments, property) minus liabilities (mortgages, loans, credit card debt). The two metrics serve different purposes in financial planning. Disposable income is the lens through which you assess month-to-month financial health, while net worth is the metric that determines your long-term financial resilience. A household might have ample disposable income but negative net worth if they’ve taken on high-interest debt or invested poorly. Conversely, someone with modest disposable income could have a growing net worth through disciplined saving and asset appreciation. The difference between disposable income and household net worth isn’t just theoretical—it dictates whether you can afford a new car today or retire comfortably in 20 years. What’s often overlooked is that these metrics interact in complex ways. For example, increasing disposable income through a raise might lead to higher spending, which could reduce net worth growth if those funds aren’t allocated toward assets. Similarly, a one-time windfall (like a bonus) that boosts disposable income could temporarily inflate net worth—but if it’s spent on depreciating items, the long-term impact is negligible. The relationship between the two isn’t static; it evolves with life stages, economic conditions, and personal financial habits."Disposable income is the oxygen of daily life, but net worth is the foundation of your financial future. You can’t have one without the other—but you can certainly have one without the other." — Andrew Hallam, author of The Millionaire Fastlane
| Common Belief | What the Evidence Says |
|---|---|
| "A high disposable income means I’m building wealth." | Not necessarily. Disposable income reflects spending power, not asset accumulation. Wealth growth depends on how those funds are used. |
| "Net worth is only for the rich." | Net worth matters at every income level. Even small, consistent increases in assets (like home equity or retirement accounts) compound over time. |
| "If my net worth is growing, I don’t need to track disposable income." | Net worth growth doesn’t guarantee liquidity. A household with a high net worth but no disposable income may struggle with immediate expenses. |
Why the Confusion Persists
The primary reason for the confusion lies in how these terms are used in public discourse. Media outlets often report on disposable income trends because they’re easier to measure and relate to immediate living standards. Politicians highlight disposable income growth to signal economic progress, while net worth figures are buried in long-term economic reports. The result is a cultural emphasis on what you earn and spend now over what you own and owe later. Financial literacy programs also contribute to the mix-up. Many resources focus on budgeting—teaching how to manage disposable income—while neglecting the nuances of net worth calculation. Even personal finance gurus sometimes oversimplify, framing wealth building as a matter of saving more from disposable income without addressing the role of asset appreciation, debt management, or market conditions. The difference between disposable income and household net worth becomes blurred when financial education treats them as interchangeable tools for the same goal. Another factor is the psychological disconnect between short-term and long-term thinking. Humans are wired to prioritize immediate needs over distant outcomes, which is why disposable income feels more tangible. Net worth, by contrast, is an abstract concept that requires tracking over years. The brain’s preference for present rewards over future gains—known as hyperbolic discounting—means people often focus on disposable income’s allure while ignoring net worth’s silent growth. This cognitive bias reinforces the myth that the two are linked when, in reality, they require entirely different strategies to optimize.
Conclusion
The difference between disposable income and household net worth isn’t just a matter of definitions—it’s a reflection of how money works in practice. One measures your ability to live comfortably today; the other measures your capacity to thrive in the future. Ignoring this distinction can lead to financial missteps, from overspending on depreciating assets to underestimating the power of compound growth. The key to financial health isn’t choosing between the two but balancing them—ensuring that disposable income funds your present while net worth secures your future. For most households, the challenge lies in aligning the two. A high disposable income without net worth growth is like driving fast with no brakes; a strong net worth without disposable income is like being stranded with no fuel. The optimal approach depends on life stage: young earners may prioritize disposable income to build savings, while older households might shift focus to preserving net worth. Understanding the difference between disposable income and household net worth isn’t about picking one over the other—it’s about recognizing that both are essential, and both require deliberate management.Comprehensive FAQs
Q: Can disposable income be negative?
A: Technically, no—disposable income is the amount left after taxes and essential expenses, so it’s always non-negative. However, if your expenses exceed your income after taxes (including deductions), you’re operating at a cash-flow deficit, which isn’t sustainable long-term. In this case, your "disposable income" is effectively zero, and you’re relying on savings or debt to cover gaps. This is why tracking both disposable income and net worth is critical: a negative cash flow can erode net worth rapidly.
Q: Does increasing disposable income always lead to higher net worth?
A: No. Disposable income is the raw material for net worth growth, but how you use it determines the outcome. For example, using a raise to pay down high-interest debt improves net worth, while spending it on non-essential items does not. Research from the Federal Reserve shows that households in the top 10% of income earners often have lower net worth growth rates than middle-income families because their disposable income is directed toward lifestyle expenses rather than assets. The difference between disposable income and household net worth lies in allocation: one is a resource; the other is the result of how that resource is managed.
Q: How often should I calculate my net worth?
A: Ideally, every six months—or annually if you’re in a stable financial situation. Net worth isn’t just a number; it’s a living indicator of your financial progress. Tracking it regularly helps you spot trends, such as whether your assets are growing faster than your liabilities or if debt repayment is improving your position. For those with volatile incomes (e.g., freelancers, commission-based earners), quarterly checks may be more appropriate. The goal isn’t perfection but awareness: recognizing the difference between disposable income and household net worth in real time allows you to adjust strategies before small imbalances become major issues.
Q: Can net worth be negative while disposable income is positive?
A: Absolutely. This is common among young adults with student loans, mortgages, or credit card debt who haven’t yet built significant assets. For example, a recent graduate with £30,000 in student loans and £5,000 in savings has a negative net worth (-£25,000) but may still have positive disposable income if their take-home pay covers living expenses. The difference between disposable income and household net worth in this case highlights a critical phase: while you can manage daily life with disposable income, negative net worth signals that wealth-building strategies (like aggressive debt repayment or saving) must take priority to avoid long-term financial strain.
Q: Why do some people with high disposable income have low net worth?
A: This typically happens when disposable income is spent on liabilities or non-appreciating assets. High earners in urban areas, for instance, may allocate disposable income to rent (which doesn’t build equity), luxury goods (which depreciate), or lifestyle inflation (e.g., dining out, subscriptions). Additionally, some high earners take on leverage—such as multiple mortgages or investment loans—that inflates their liabilities faster than their assets grow. The difference between disposable income and household net worth in these cases reveals a structural issue: income alone doesn’t guarantee wealth unless it’s directed toward assets that appreciate over time. Even six-figure earners can have modest net worth if their spending habits prioritize consumption over investment.
Q: How does inflation affect the difference between disposable income and household net worth?
A: Inflation erodes the purchasing power of disposable income over time, making it harder to maintain the same standard of living without salary growth. Meanwhile, net worth can be both helped and hurt by inflation: assets like real estate or stocks often appreciate during inflationary periods, boosting net worth, while cash savings lose value. The difference between disposable income and household net worth becomes more pronounced in high-inflation environments, where disposable income may shrink in real terms while net worth grows for those holding appreciating assets. This is why diversifying assets (e.g., mixing stocks, real estate, and inflation-protected bonds) is crucial—it ensures that net worth growth isn’t solely dependent on disposable income’s ability to cover rising costs.
