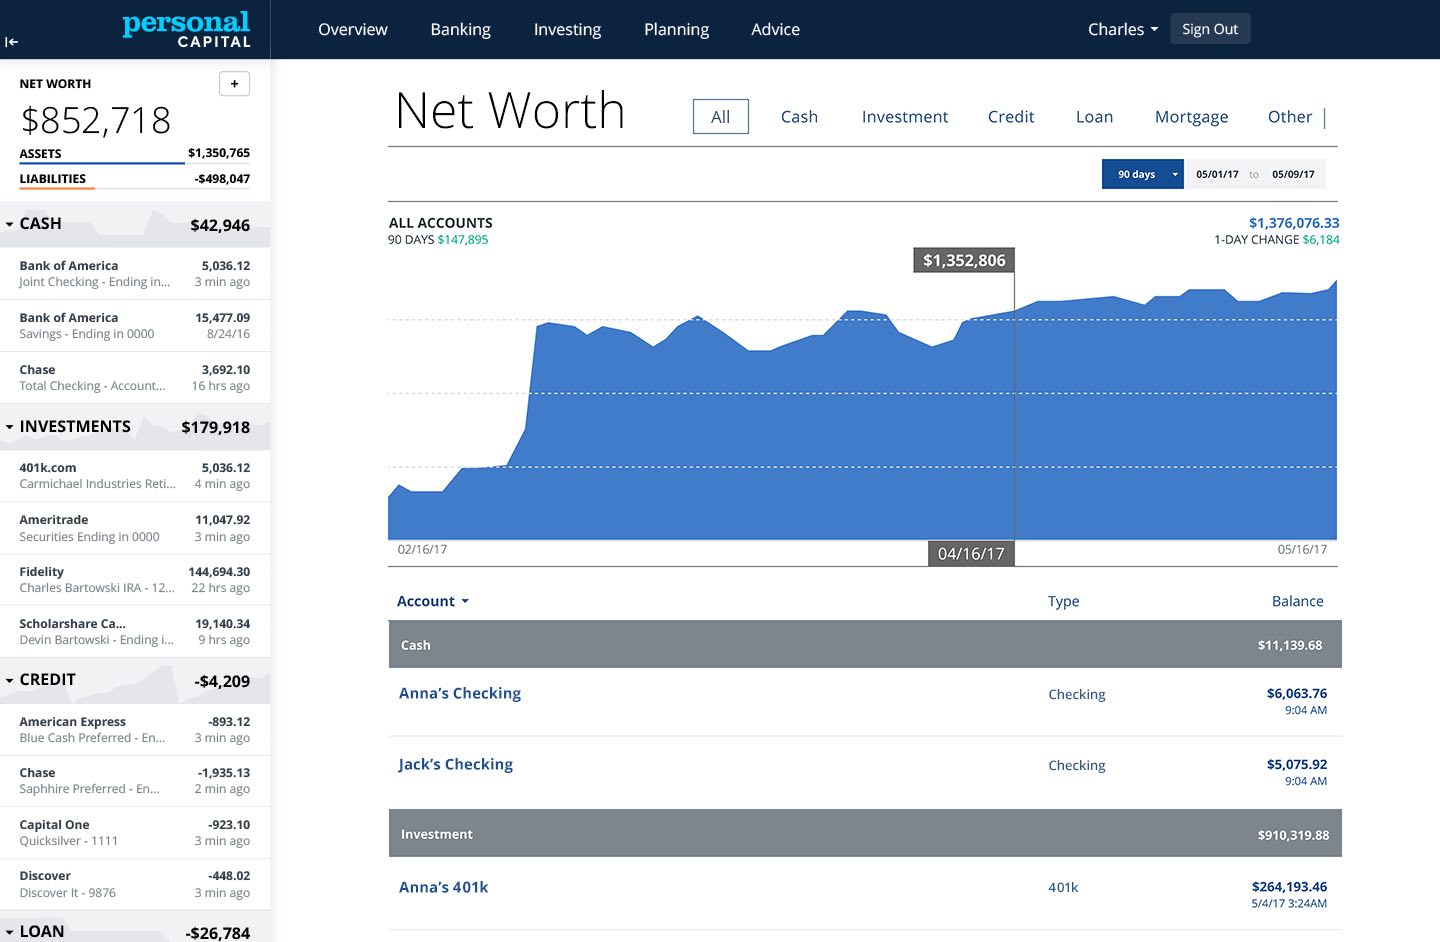
Common Myths About Retirement Net Worth Planning
The biggest obstacle to help me plan for retirement net worth isn’t a lack of tools—it’s the myths that distort priorities. Many people believe they can outrun inflation with aggressive stock picks or that a 401(k) alone will suffice. Others assume that once they hit a certain age, their savings will magically compound into security. The reality is far more nuanced. For instance, the "rule of thumb" that you need 70–80% of your pre-retirement income to retire comfortably is outdated. In 2024, that percentage varies wildly depending on where you live, your health, and whether you plan to work part-time. A couple in Florida might need 90% of their income to maintain their lifestyle, while a couple in a low-cost state could manage on 60%. The problem? Most people pick a target and never revisit it. Another persistent myth is that retirement planning is a solo endeavor. In truth, it’s a collaborative process that should account for spousal benefits, inheritance strategies, and even the impact of divorce or remarriage. Yet surveys show that 60% of Americans don’t discuss retirement plans with their partners, leaving gaps in coverage. For example, if one spouse retires five years earlier than the other, the household’s net worth must bridge that income gap—often through annuities or phased withdrawals. Ignoring these dynamics can turn a comfortable retirement into a financial tightrope.Myth 1: "I Just Need to Save 25% of My Income"
The idea that saving 25% of your income will automatically lead to a secure retirement is oversimplified. That percentage works for some—particularly those with low expenses, high earning potential, or access to employer matches—but it’s a one-size-fits-none approach. Consider two earners: one in their 30s with a $120,000 salary and another in their 50s with the same salary. The first might save 25% ($30,000/year) and see their net worth grow exponentially with time. The second, however, may need to save 40% to catch up, given compounding’s diminishing returns as retirement nears. The 25% rule also ignores debt, childcare costs, or unexpected medical expenses, which can derail even disciplined savers. The reality is that help me plan for retirement net worth requires a dynamic approach. A better framework is the "4% rule" (adjusted for inflation), which suggests you’ll need 25 times your annual expenses in savings to withdraw 4% annually without depleting your nest egg. But this assumes a 50/50 stock-bond allocation and doesn’t account for sequence-of-returns risk—the devastation a bad market year early in retirement can have on your portfolio. For example, if you retire in 2000 (just before the dot-com crash) versus 2009 (post-recession recovery), your withdrawal strategy would need to adjust by 20–30%. The solution? Stress-test your plan with different market scenarios and adjust your savings rate accordingly.Myth 2: "Real Estate Is the Safest Retirement Asset"
Homeownership is often touted as a retirement anchor, but it’s not without risks. A primary residence provides stability, but it’s illiquid, subject to maintenance costs, and doesn’t generate cash flow unless you rent it out or downsize. The problem? Many retirees treat their home as a piggy bank, tapping equity through reverse mortgages or home equity lines of credit (HELOCs). According to the Consumer Financial Protection Bureau, 60% of reverse mortgage borrowers use the funds for living expenses, not emergencies. This can backfire if housing values dip or medical costs rise unexpectedly. A home’s value isn’t guaranteed to appreciate—witness the 2008 crash, where some homeowners saw equity vanish overnight. The bigger issue is opportunity cost. Money tied up in a home isn’t invested in stocks, bonds, or other assets that historically outperform real estate over time. For example, the S&P 500 has averaged ~10% annual returns since 1926, while residential real estate returns hover around 3–4% (after inflation). If your help me plan for retirement net worth relies solely on home equity, you’re missing out on growth opportunities elsewhere. A balanced approach might involve keeping the home as a stable asset while allocating a portion of savings to diversified investments—especially if you’re not planning to downsize.Myth 3: "I Can Retire Early If I Save Enough"
Early retirement (FIRE—Financial Independence, Retire Early) is achievable, but it’s not as simple as hitting a savings target. The math is brutal: to retire at 40 with a $100,000 annual income, you’d need roughly $2.5–$3 million in net worth, assuming a 4% withdrawal rate. That’s because you’re stretching 30–40 years of savings over 40–50 years of retirement. The FIRE movement’s success stories often overlook critical variables: healthcare costs (which rise sharply before Medicare at 65), the loss of employer benefits like 401(k) matches, and the psychological toll of leaving the workforce decades early. A 2022 study in the Journal of Financial Planning found that 30% of early retirees return to work within five years, often due to boredom or financial miscalculations. The reality is that help me plan for retirement net worth for early retirement requires more than just savings—it demands a flexible lifestyle, tax-efficient withdrawals, and a contingency plan for unexpected expenses. For example, if you retire at 45 but live to 95, your savings must last 50 years. That means either saving aggressively (60–70% of your income) or accepting a lower standard of living. Most people can’t—or won’t—do both. The FIRE strategy works best for those with low expenses, high income, or a side hustle to supplement savings. For the average earner, a more gradual transition (semi-retirement or phased withdrawals) is often the pragmatic choice.
What Holds Up to Scrutiny
At its core, help me plan for retirement net worth hinges on three verifiable principles: diversification, liquidity, and tax efficiency. Diversification isn’t just about stocks vs. bonds—it’s about spreading risk across asset classes, geographies, and even alternative investments like TIPS (Treasury Inflation-Protected Securities) or dividend-paying stocks. A 2023 Vanguard study found that portfolios with 60% stocks and 40% bonds historically delivered steady growth with lower volatility than all-stock portfolios. The key is rebalancing annually to maintain your target allocation, especially as you age and risk tolerance shifts. Liquidity is often overlooked until it’s too late. Retirees need access to cash for emergencies, market downturns, or unexpected opportunities. Holding too much in illiquid assets (like real estate or private equity) can force forced sales at inopportune times. A rule of thumb: keep 1–2 years’ worth of expenses in liquid assets (cash, CDs, or short-term bonds). This buffer prevents panic selling during market downturns, which can erode your net worth faster than inflation. Tax efficiency is the wildcard most people ignore. For example, Roth IRAs and 401(k)s offer tax-free growth, but their contribution limits ($6,500 in 2024 for IRAs) may not be enough for high earners. Meanwhile, traditional IRAs and 401(k)s defer taxes until withdrawal, which can push retirees into higher tax brackets. A better strategy? Use a mix of taxable brokerage accounts, tax-advantaged accounts, and municipal bonds (for state tax-free income). The goal is to minimize tax drag on your net worth over time."Retirement planning isn’t about the money—it’s about the freedom to use it without fear. The best plans aren’t rigid; they’re adaptive, with room for life’s surprises." — Michael Kitces, CFP and retirement income expert
| Common Belief | What the Evidence Says |
|---|---|
| Social Security will cover 40% of my income. | Average benefit replaces ~33% of pre-retirement income, and benefits are taxable above certain thresholds. |
| A 401(k) is enough if my employer matches. | Employer matches are a bonus, but most people need additional savings (IRAs, HSAs, taxable accounts) to meet long-term goals. |
| Real estate always appreciates. | Home values can stagnate or decline (e.g., Rust Belt cities, rural areas). Maintenance and property taxes eat into returns. |
| I can retire early if I save 50% of my income. | Early retirement requires extreme frugality or high income. Most people need 70–80% savings rates to retire before 55. |
Why the Confusion Persists
The noise around help me plan for retirement net worth stems from two sources: conflicting advice and behavioral biases. Financial media often sensationalizes stories—whether it’s the "average millionaire" narrative or the "stocks will always go up" myth—without context. For example, the "average" millionaire includes people who inherited wealth or live in low-cost areas, skewing perceptions of what’s achievable. Meanwhile, advisors push products (annuities, whole life insurance) that may not align with a client’s actual needs, creating a conflict of interest. Behavioral biases play a bigger role. Loss aversion makes people overly cautious, leading to underinvestment in stocks or over-reliance on cash. Meanwhile, optimism bias causes some to assume they’ll outperform the market or live longer than average. The result? Some retirees run out of money early, while others leave heirs with more than they need. The solution isn’t to eliminate risk but to structure it intentionally—diversifying assets, setting withdrawal rules, and regularly stress-testing your plan against worst-case scenarios.
Conclusion
Retirement net worth isn’t a static number—it’s a dynamic system that requires ongoing management. The most successful planners don’t just save; they help me plan for retirement net worth by aligning their assets with their lifestyle, tax situation, and risk tolerance. This means moving beyond generic rules of thumb to a personalized strategy that accounts for your unique circumstances. For example, a couple in their 50s with a $200,000 net worth and $80,000 in annual expenses might need to save $1,500/month to retire at 65, but a single person with the same net worth and expenses might need $2,500/month to account for lost spousal benefits. The good news is that the tools exist to make this manageable. Automated investment platforms, robo-advisors, and financial planning software can simulate different scenarios, helping you see how changes in savings rates, market returns, or healthcare costs affect your outcome. The key is to start now—even small adjustments (like increasing your 401(k) contribution by 1%) can compound over time. The earlier you begin, the less aggressive you’ll need to be later. And remember: retirement isn’t an endpoint. It’s a new chapter, and the best plans are those that adapt as you do.Comprehensive FAQs
Q: How much net worth do I need to retire comfortably?
There’s no one-size-fits-all answer, but a common benchmark is 25–30 times your annual expenses (the "4% rule"). For example, if you spend $60,000/year, aim for $1.5–$1.8 million. However, this assumes a 50/50 stock-bond portfolio and doesn’t account for healthcare, taxes, or sequence-of-returns risk. Adjust for your location (cost of living varies) and whether you plan to work part-time.
Q: Should I pay off my mortgage before retiring?
Not necessarily. A mortgage can provide forced savings (discipline in housing costs) and tax deductions (if itemizing). However, if you’re in a low-interest-rate environment, paying it off early may not be the best use of funds. Instead, allocate extra payments to high-interest debt or investments. Run the numbers: compare the interest you’d save vs. the returns you’d earn elsewhere.
Q: How do I protect my net worth from inflation?
Inflation erodes purchasing power over time, so your portfolio must include assets that historically outpace it. Stocks (especially dividend-paying ones), TIPS, and real estate (if rented out) are good hedges. Avoid cash-heavy portfolios—even high-yield savings accounts may not keep up with 3–4% inflation. Rebalance annually to maintain your target allocation (e.g., 60% stocks/40% bonds at retirement).
Q: Can I rely on Social Security alone?
No. Social Security was designed to replace ~40% of pre-retirement income, but most people need more. The average benefit in 2024 is around $1,900/month, which covers basic living expenses but not discretionary spending. Delaying claiming (up to age 70) increases benefits by ~8%/year, but this isn’t feasible for everyone. Combine Social Security with savings, pensions (if available), and part-time work for a sustainable income stream.
Q: What’s the best age to start planning for retirement?
Now. Even in your 20s, small contributions to tax-advantaged accounts (like a Roth IRA) can grow significantly with compounding. For example, saving $500/month at 25 vs. 40 could mean an extra $500,000+ by retirement, assuming 7% annual returns. If you’re in your 30s or 40s, focus on maximizing employer matches, reducing high-interest debt, and increasing savings rates. The later you start, the more aggressive you’ll need to be.
Q: How do I adjust my plan if I retire early?
Early retirement requires a help me plan for retirement net worth that accounts for longer withdrawal periods and lost employer benefits. Start by calculating your "safe withdrawal rate" (likely 3–3.5% to extend savings). Diversify income sources: part-time work, rental income, or annuities can supplement savings. Monitor healthcare costs—Medicare doesn’t kick in until 65—and consider a Health Savings Account (HSA) for tax-free medical expenses. Finally, build flexibility into your budget for unexpected expenses.
Q: What’s the biggest mistake people make with retirement savings?
Assuming they’ve saved "enough" without testing their plan. Many people calculate their net worth but don’t simulate withdrawals, tax impacts, or market downturns. Use a retirement calculator (like Vanguard’s or Fidelity’s) to model different scenarios. Another mistake? Ignoring taxes—withdrawals from traditional accounts are taxable, and required minimum distributions (RMDs) start at 73. The solution? Diversify account types (Roth, traditional, taxable) and consult a tax-efficient withdrawal strategy.
