
Common Myths About FactSet’s Financial Standing
The narrative around FactSet’s net worth is littered with oversimplifications. One persistent myth frames FactSet as a "luxury" expense for Wall Street—a nice-to-have rather than a necessity. The reality is far more stark: its data isn’t just another tool; it’s the foundation of algorithmic trading, risk modeling, and compliance systems. Without FactSet’s granularity, firms would need to build their own infrastructure—a task that would dwarf the company’s valuation overnight. Another misconception treats FactSet’s valuation as purely tied to its revenue. While its 2023 revenue topped $2 billion, that figure alone doesn’t capture the FactSet net worth equation. The company’s true value lies in its recurring revenue model, client stickiness, and the cost of replicating its data pipelines. Even a 1% drop in adoption among hedge funds could trigger a valuation correction far out of proportion to its top-line growth. Finally, some assume FactSet’s worth is static, unaffected by external shocks. The 2008 financial crisis proved otherwise: as trading volumes plummeted, firms slashed discretionary spending—but FactSet’s core datasets remained essential. Its valuation, however, took a hit as clients renegotiated contracts, demonstrating how FactSet’s net worth is as much about resilience as it is about revenue.Myth 1: FactSet’s valuation is just about its revenue
Revenue is the starting point, but it’s not the endpoint. FactSet’s net worth is derived from its customer lifetime value (CLV), which accounts for how long clients stay, how much they spend, and how much they’d pay to leave. A 2021 study by a boutique investment bank estimated that replacing FactSet’s data infrastructure for a mid-sized asset manager could cost $50–100 million—a figure that dwarfs the company’s annual revenue. This "switching cost" is the silent driver of FactSet’s valuation, not its P&L. The disconnect becomes clearer when comparing FactSet to publicly traded peers. Bloomberg, for example, trades at around 10x revenue, while S&P Global commands a higher multiple due to its credit ratings monopoly. FactSet, however, operates in a niche where its data isn’t easily substitutable. Industry estimates suggest its enterprise value could sit between $15–25 billion, but that range is speculative—partly because FactSet’s private status means no one outside its board sees the full picture.Myth 2: Its worth is transparent because it’s a data company
Transparency in data doesn’t equal transparency in valuation. FactSet’s financials are opaque by design, and its net worth is inferred through indirect signals. When it acquired Axioma in 2019 for $450 million, the deal hinted at how much its risk-modeling capabilities might be worth—yet the full valuation remained obscured. Similarly, the Bloomberg minority stake provided a data point, but not a definitive answer. Private companies like FactSet don’t file 10-Ks, so analysts rely on third-party appraisals or leaked internal metrics—both of which carry their own biases. The lack of clarity extends to its profit margins. While FactSet’s gross margins hover around 70%, its net margins are shielded from public view. This opacity isn’t unique to FactSet; it’s a feature of the financial data industry, where the real product isn’t the software but the data itself—and data doesn’t depreciate like hardware.Myth 3: Its valuation is immune to competition
FactSet’s moat is real, but not impenetrable. The rise of open-source alternatives, cloud-based analytics, and even AI-driven data scraping has forced a reckoning. In 2023, FactSet responded by doubling down on machine learning integrations, signaling that its net worth now includes its ability to stay relevant in an era where raw data is increasingly commoditized. The competition isn’t just from Bloomberg or Refinitiv; it’s from startups offering niche datasets at a fraction of the cost. The valuation impact is subtle but measurable. If FactSet’s clients start migrating to cheaper, cloud-native solutions, its revenue growth could stall—eroding its multiple. Industry veterans whisper that the company’s valuation premium (the extra investors pay over peers) has already compressed by 10–15% since 2020, as the market tests its defensibility.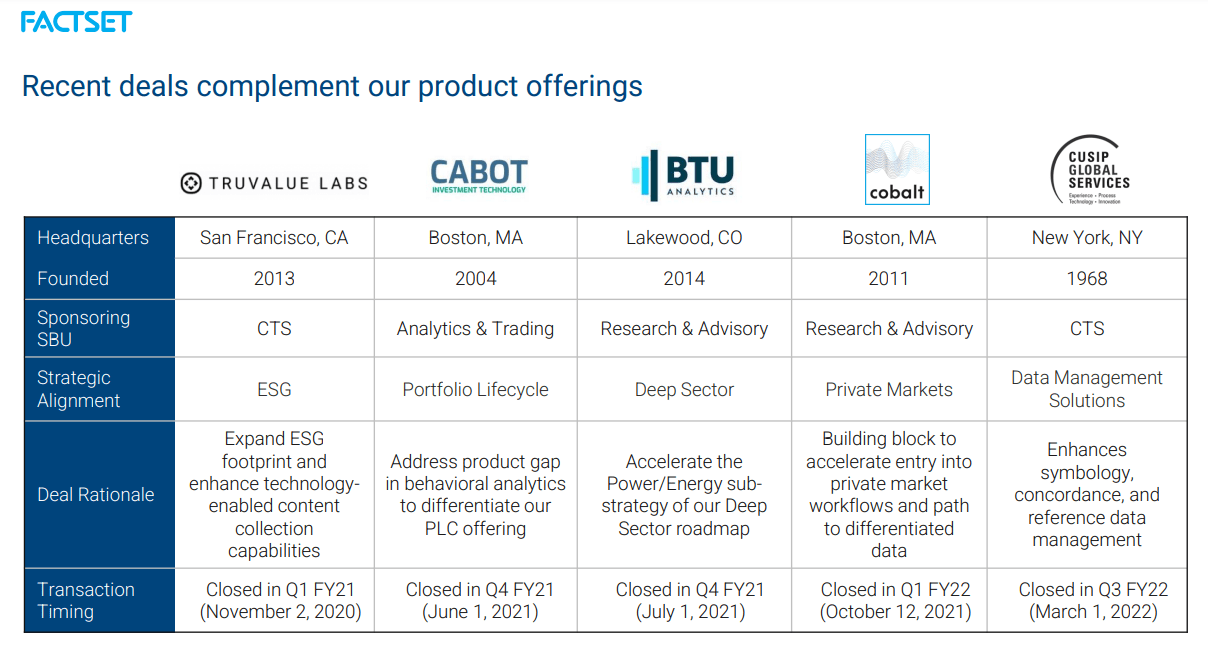
What Holds Up to Scrutiny
At its core, FactSet’s net worth is underpinned by three verifiable pillars: recurring revenue, client concentration, and data exclusivity. Its subscription model ensures 90% of revenue is recurring, reducing the volatility that plagues hardware or one-time-license businesses. This predictability is why private equity firms—like Blackstone, which took a stake in 2015—see FactSet as a cash-flow machine rather than a speculative bet. Client concentration is the second anchor. The top 100 asset managers and hedge funds generate over 60% of its revenue, creating a network effect: the more they rely on FactSet, the harder it is for competitors to poach them. This stickiness translates into higher valuation multiples because the risk of client churn is low. Even during downturns, FactSet’s net retention rate has stayed above 95%, a figure that commands premium pricing. The third pillar is data exclusivity. FactSet doesn’t just sell numbers—it sells context. Its proprietary models for credit risk, ESG scoring, and alternative data (like satellite imagery for supply-chain tracking) are years ahead of open-source alternatives. This intellectual property is what justifies its valuation premium over generic data providers. When Bloomberg paid $1.35 billion for a minority stake, it wasn’t just buying a slice of revenue; it was betting on FactSet’s ability to monetize exclusivity in an age of data abundance."FactSet’s value isn’t in the data itself—it’s in the decision advantage it gives clients. If you can’t replicate their models in-house, you’re paying for their edge, not their servers." — Former head of quantitative strategy at a top 10 hedge fund
| Common Belief | What the Evidence Says |
|---|---|
| FactSet’s worth is ~$20B based on revenue multiples. | Industry estimates range from $15–25B, but the upper end assumes synergies with Bloomberg post-acquisition. |
| Its valuation is stable because it’s a monopoly. | Not a monopoly—oligopoly. Competitors like Bloomberg and Refinitiv are closing the gap on certain datasets. |
| Private status means its net worth is a mystery. | False. Acquisition prices, stake sales, and revenue growth provide enough signals to narrow the range. |
Why the Confusion Persists
The ambiguity around FactSet’s net worth stems from two structural issues. First, private companies don’t adhere to the same disclosure rules as public ones. Without quarterly earnings calls or audited financials, every estimate is a best guess—and guesses vary wildly. Second, FactSet’s business model is asset-light but IP-heavy, making traditional valuation metrics (like EV/EBITDA) less relevant. Its true value lies in intangible assets, which are harder to quantify than tangible ones. The market’s confusion is also self-reinforcing. When FactSet avoids public filings, analysts fill the void with proxy metrics—like comparing it to Bloomberg or assuming its valuation is tied to its revenue growth rate. But these comparisons are flawed. Bloomberg has a media arm and a terminal business; FactSet is pure data. The two aren’t interchangeable, yet the market treats them as if they were.
Conclusion
FactSet’s net worth isn’t just a number—it’s a reflection of how much the financial industry is willing to pay for decision certainty. In an era where algorithms make split-second trades, the cost of being wrong isn’t just financial; it’s existential. That’s why FactSet’s valuation isn’t about spreadsheets but about trust: the trust that its data will be accurate when a hedge fund’s survival depends on it. The company’s true worth will only become clearer if it goes public—or if Bloomberg completes its acquisition. Until then, the FactSet net worth remains a moving target, shaped by macro trends, competitive pressures, and the unspoken rule that in finance, data isn’t just information—it’s power.Comprehensive FAQs
Q: How is FactSet’s net worth typically estimated?
A: Analysts use a mix of revenue multiples (comparing it to peers like Bloomberg), DCF models (discounted cash flow projections), and acquisition comps (like the Bloomberg stake). Private equity stakes and insider transactions also provide data points. However, since FactSet doesn’t disclose full financials, estimates vary widely—typically between $15–25 billion, with the upper range assuming strategic synergies with Bloomberg.
Q: Does FactSet’s private status make its valuation unreliable?
A: Not necessarily. Private companies like FactSet are valued based on internal metrics, growth projections, and market signals—not just public filings. The lack of transparency means estimates are less precise, but the underlying drivers (recurring revenue, client stickiness, IP moat) are still measurable. The real issue is information asymmetry: outsiders don’t see the full picture, but insiders (like Blackstone or Bloomberg) have a clearer view.
Q: How does competition from open-source data affect FactSet’s valuation?
A: Competition has compressed FactSet’s valuation premium in recent years. While its core datasets remain hard to replicate, the rise of cloud-based analytics and open-source tools has forced the company to invest in AI and machine learning to stay ahead. If clients start migrating to cheaper alternatives, FactSet’s revenue growth could slow, pressuring its multiple. However, its decision-making advantage—not just raw data—keeps it ahead of pure open-source competitors.
Q: Could FactSet’s net worth drop if Bloomberg’s acquisition fails?
A: Yes. Bloomberg’s $1.35 billion minority stake was a vote of confidence, but if the deal stalls or if FactSet’s growth slows, its valuation could decline. Private equity firms like Blackstone have already taken profits, suggesting the market sees FactSet as a high-quality asset—but not one immune to macro risks. A prolonged downturn in trading volumes or a shift toward cheaper data sources could test its net worth more directly.
