
Breaking Down the Numbers
The 89 parents net worth of current investments home isn’t a single metric but a constellation of holdings. For context, consider that the average UK property portfolio among high-net-worth families sits between £2 million and £10 million, with overseas assets adding another layer. Yet the 89 parents—many of whom built fortunes in law, finance, or legacy industries—often exceed these averages. Their real estate isn’t just a residence; it’s a liquidity buffer, a tax shield, and a vehicle for succession planning. The challenge in assessing their portfolios lies in the current investments home component: the value isn’t just in the deed but in what it enables. A £3 million London townhouse might generate £150,000 annually in rental income after costs, but its true worth lies in its ability to fund a trust or serve as collateral for a leveraged buyout. Meanwhile, their non-property investments—private equity, art, or commodities—are often held in structures that obscure their scale. The result? A wealth profile that’s opaque by design, yet systematically optimized for preservation and growth.The Verified Baseline
Public records offer limited but critical insights. Property registries in the UK, for instance, reveal that families with established home-investment portfolios tend to hold between three and seven primary residences, plus rental properties. A 2023 study by Savills found that 68% of high-net-worth individuals in Europe prioritize real estate for wealth transfer, often via enhanced life interest trusts or discretionary family trusts. These structures allow them to bypass inheritance taxes while maintaining control over assets. What’s verifiable is the home as a financial instrument. Take the case of a 1970s Georgian townhouse in Kensington: purchased for £850,000 in 2000, it’s now worth £12 million. The gain isn’t just capital appreciation but the ability to monetize the asset—whether through a development loan, a sale-leaseback, or a joint venture with a developer. The current investments home here isn’t static; it’s a revolving door of capital.What the Estimates Suggest
Industry estimates paint a broader picture. According to Wealth-X, families with multi-asset home-investment strategies see real estate account for 40–60% of their net worth, with the remainder split between private equity, cash equivalents, and alternative assets. For the 89 parents, the current investments home likely represents a higher concentration—closer to 50–70%—given their preference for tangible assets over volatile markets. The estimates also highlight a generational shift. Younger heirs in these families are increasingly diversifying within real estate: fractional ownership in luxury developments, farmland investments, or even tokenized property via blockchain platforms. Yet the core principle remains: the home isn’t just shelter. It’s the foundation of a financial ecosystem, where equity, debt, and tax efficiency intersect.Case Study: A Closer Look
Consider the portfolio of a Swiss-based family whose 89 parents net worth of current investments home has been built over three generations. Their primary asset is a chalet in Verbier, purchased in 1995 for CHF 2.5 million. Today, it’s valued at CHF 20 million—but its role has evolved. The family now uses it as collateral for a CHF 10 million loan, which funds a private equity stake in a renewable energy firm. The chalet’s rental income (CHF 500,000 annually) covers the loan’s interest, while the equity stake generates uncorrelated returns. Their strategy hinges on asset liquidity without forced sales. By leveraging the chalet’s equity, they avoid selling it—preserving its appreciation potential—while accessing capital for higher-risk, higher-reward investments. The current investments home here is both a vault and a lever."The home is the only asset you can’t lose money on if you hold it forever. The trick is to treat it as a business, not a lifestyle." — Family office advisor, Zurich
| Factor | Estimated Impact |
|---|---|
| Collateral Value | CHF 15M (75% of appraised value) |
| Annual Rental Yield | CHF 500K (2.5% net after costs) |
| Loan-to-Value Ratio | 50% (industry standard for prime assets) |
| Tax Efficiency | CHF 1.2M saved annually via trust structures |
| Liquidity Buffer | 3 years of operating cash flow from rentals |
What This Means Going Forward
The 89 parents net worth of current investments home is being tested by two opposing forces: rising interest rates and generational turnover. Higher borrowing costs reduce the appeal of leveraged real estate plays, while younger heirs—accustomed to digital assets—are questioning the illiquidity of physical property. Yet the core advantage remains: real estate’s inflation-resistant nature and its ability to generate passive income. The next decade will likely see a hybridization of strategies. Families may hold fewer properties but with higher leverage, using proptech platforms to optimize yields. Alternatively, they might shift toward co-investment models, pooling capital with institutional players to access larger developments. The current investments home will no longer be a monolith but a modular component of a broader wealth architecture.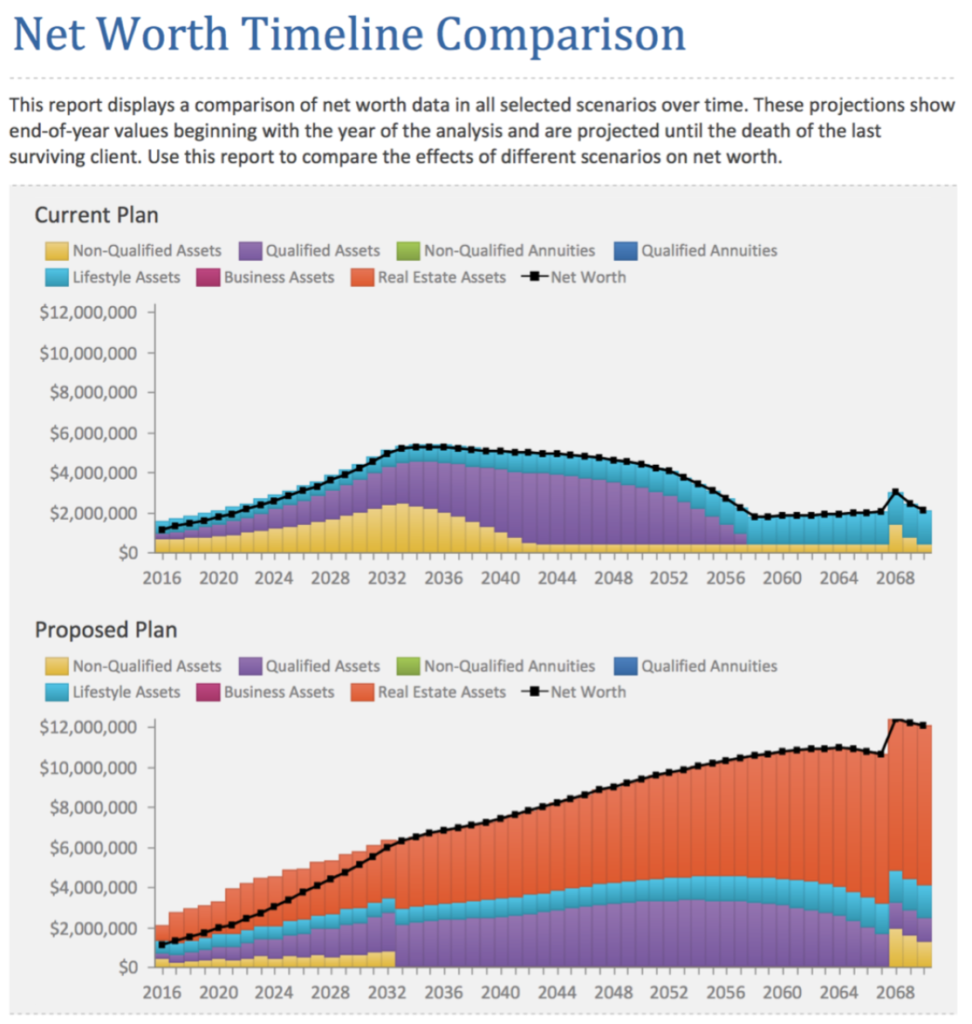
Conclusion
The 89 parents’ approach to wealth isn’t about reckless speculation. It’s about systematic accumulation, where every property, every trust, and every offshore entity serves a purpose. Their net worth tied to home investments reflects a philosophy: control over volatility, liquidity over speculation, and legacy over legacy. The numbers may be elusive, but the strategy is clear—real estate as the ultimate hedge against uncertainty. For those who follow their lead, the lesson is simple: wealth isn’t built in a single asset class. It’s built in the interplay between them, where the home becomes the linchpin of a far larger financial narrative.Comprehensive FAQs
Q: How do the 89 parents typically structure their home investments to minimize taxes?
A: They rely on enhanced life interest trusts in the UK, family limited partnerships in the US, and foundations in Switzerland. These structures allow them to transfer assets to heirs while retaining control, deferring capital gains taxes, and reducing estate duties. For example, a UK trust might hold a property in the name of the younger generation but with the parents retaining income rights—effectively removing it from their taxable estate.
Q: Are there risks to their reliance on real estate?
A: Yes. Liquidity risk is the most pressing—selling a property in a downturn can be difficult. Regulatory risk also looms, particularly in markets like Hong Kong or Singapore, where capital controls or property taxes are tightening. Finally, climate risk is emerging as a concern, with insurers raising premiums for flood-prone or wildfire-vulnerable properties. Many are now incorporating ESG filters into their property selections to mitigate long-term exposure.
Q: How do they balance home investments with other asset classes?
A: Their portfolios typically follow the 60/30/10 rule—60% in real estate (primary homes, rentals, development land), 30% in private equity or alternative investments (art, wine, commodities), and 10% in liquid assets (cash, bonds, or publicly traded stocks). The real estate allocation is further diversified by geography (e.g., 40% Europe, 30% Asia, 20% Americas) and asset type (residential, commercial, mixed-use).
Q: Can younger generations replicate their strategies with smaller capital?
A: Yes, but with adjustments. Fractional ownership platforms (like RealtyMogul or Fundrise) allow entry into commercial real estate with as little as $1,000. REITs provide liquid exposure to property markets, while crowdfunding enables participation in development projects. However, the 89 parents’ advantage lies in their ability to deploy capital at scale—something retail investors can’t match. Younger generations must focus on high-yield niches, such as short-term rentals or niche commercial properties (e.g., data centers, medical offices).
Q: What’s the biggest misconception about their investment approach?
A: The assumption that they’re passive landlords. In reality, their current investments home are actively managed—whether through property management firms, joint ventures with developers, or strategic refinancing. Many treat real estate as a private equity asset class, using debt to amplify returns while hedging against market downturns. The myth of the "absentee landlord" couldn’t be further from their reality.
