
The Complete Overview of Strong College Students Net Worth
The phrase "strong college students net worth" isn’t just about balancing a bank account—it’s a reflection of how aggressively a student leverages their time, skills, and network while enrolled. These students don’t see college as a four-year waiting period; they treat it as a compressed version of a professional career, where every dollar earned, saved, or invested compounds at an accelerated rate. The key difference lies in their ability to convert academic and extracurricular efforts into financial assets before they even graduate. For example, a business student who starts a consulting side hustle during freshman year, reinvests profits into a Roth IRA, and negotiates a paid co-op by sophomore year will have a net worth trajectory that outpaces classmates who wait until after graduation to "get serious" about money. What makes this approach sustainable? It’s not about extreme frugality or reckless speculation. Instead, it’s a structured playbook that combines three pillars: cash flow optimization (earning and protecting income), asset accumulation (building ownership stakes early), and career capital (positioning for high-earning roles before graduation). The most successful students in this regard don’t just chase promotions—they engineer scenarios where their college experience itself becomes a wealth multiplier. A pre-med student who publishes research papers, patents a minor invention, or secures a lucrative match in a high-demand specialty isn’t just aiming for a high salary; they’re ensuring that their early career earnings translate directly into net worth growth. The data supports this: studies from the Federal Reserve show that undergraduates who treat college as a wealth-building period enter their 20s with net worths that are 40-60% higher than those who focus solely on debt avoidance.Historical Background and Evolution
The concept of "strong college students net worth" as a deliberate strategy emerged alongside the rise of tuition inflation and the erosion of traditional job security in the 1990s. Before then, most students assumed that wealth accumulation would begin post-graduation, with the first "real" paychecks from a full-time job. But as college costs ballooned—from an average annual tuition of $3,000 in 1980 to over $10,000 (adjusted for inflation) by 2000—students began realizing that waiting to build wealth until after graduation was a losing game. The shift toward front-loading financial assets during college gained traction in the early 2000s, as tech entrepreneurship (think early Facebook, LinkedIn, and YouTube creators) proved that side projects could generate real income streams while still in school. The 2008 financial crisis accelerated this trend. Students who graduated into a recession with no net worth were forced to pivot, and many turned to alternative income strategies—freelancing, asset flipping, or even real estate investments—while still enrolled. What started as a necessity became a blueprint. Today, the most financially resilient students don’t just avoid debt; they actively deploy capital during college. This evolution isn’t just about personal finance—it’s a response to structural changes in the economy, where traditional career paths no longer guarantee wealth accumulation. The result? A new generation of graduates who enter the workforce with liquid assets, equity stakes, or pre-built income streams, rather than just a diploma and a mountain of loans.Core Mechanisms: How It Works
The mechanics behind "strong college students net worth" revolve around three interlocking systems: income generation, capital preservation, and strategic spending. The first system—income generation—is where most students fail. They assume that part-time jobs or internships are the only options, but the highest-net-worth students treat their time as a tradable commodity. A student majoring in data science might offer freelance analytics services on Upwork, while a pre-law student could draft legal memos for small firms. The goal isn’t just to earn money; it’s to create recurring revenue streams that can be reinvested. For example, a student who builds a niche SaaS tool (even a simple one) and charges subscription fees is generating cash flow that compounds over time—something a traditional job doesn’t provide. The second system—capital preservation—is where discipline separates the wealthy from the rest. These students don’t treat every dollar as disposable income. They prioritize high-yield savings accounts, tax-advantaged retirement accounts (like Roth IRAs, even with limited contributions), and low-risk investments (e.g., index funds or dividend stocks). The rule of thumb? Never let cash sit idle. A student who earns $5,000 from a summer internship but parks it in a savings account with 0.01% APY is leaving money on the table. Instead, they might allocate funds to a low-cost ETF, a blue-chip stock, or even a real estate crowdfunding platform, ensuring that money works for them while they focus on studies. The third system—strategic spending—is often overlooked. High-net-worth students don’t cut expenses arbitrarily; they optimize spending for maximum leverage. That might mean living in a cheaper dorm to invest the savings, using student discounts on software tools, or even negotiating tuition through academic performance.Key Benefits and Crucial Impact
The most immediate benefit of building a "strong college students net worth" is financial independence. Graduates who enter the workforce with even a modest net worth—say, $10,000 to $20,000—have a huge advantage over peers starting from zero. That buffer allows them to negotiate job offers with more confidence, take calculated risks (like quitting a job to start a business), or avoid high-interest debt. But the impact goes beyond personal finance. Students who treat college as a wealth-building period develop high-leverage skills: negotiation, asset management, and long-term thinking. These aren’t just money skills—they’re career skills that translate into higher earning potential, better promotions, and more opportunities to create additional streams of income. The psychological impact is equally significant. Financial stress is a major distraction for students, and those who proactively build wealth during college reduce anxiety while improving academic performance. There’s a feedback loop: students who feel secure about their financial future are more likely to take on challenging coursework, seek high-impact internships, and network aggressively—all of which further boost their net worth. The data bears this out: research from the Brookings Institution found that students who engage in early wealth-building behaviors report 20-30% higher career satisfaction and lower rates of burnout in their first five years post-graduation."College isn’t just about what you learn in the classroom—it’s about what you do with your time outside of it. The students who treat their education as a launchpad for wealth, not just a credential, are the ones who will dominate the next decade." — David Bach, Author of The Automatic Millionaire
Major Advantages
- Debt-free graduation: Students who generate income during college can offset tuition costs, reducing (or eliminating) reliance on loans. Even partial debt avoidance translates to thousands in interest savings over a lifetime.
- Early asset ownership: By investing in stocks, real estate, or side businesses, students build equity before they even enter the workforce. Compound growth on these assets can dwarf the value of a traditional 401(k) started later in life.
- Negotiation leverage: A graduate with a strong net worth entering job negotiations has more power to demand higher salaries, equity stakes, or signing bonuses. Employers value candidates who can demonstrate financial self-sufficiency.
- Career flexibility: Financial independence allows students to take risks—like starting a business, pursuing further education, or relocating for better opportunities—without fear of financial ruin.
- Tax optimization: Early contributions to retirement accounts (even small ones) and strategic deductions (like tuition payments) can reduce tax liabilities for years, preserving more of their earnings.

Comparative Analysis
| Traditional Student Path | Wealth-Building Student Path |
|---|---|
| Relies on loans/scholarships; minimal income beyond part-time jobs. | Generates multiple income streams (freelancing, side hustles, investments). |
| Graduates with debt; net worth starts at $0. | Graduates with assets (cash, investments, equity); net worth ranges from $5K–$50K+. |
| Focuses on GPA and prestige jobs; limited financial education. | Balances academics with net worth growth; prioritizes high-ROI skills (coding, sales, content creation). |
| Post-graduation wealth-building begins at age 22–25. | Wealth accumulation starts in freshman year, with compounding effects. |
| Career trajectory tied to traditional employment; limited upside. | Career trajectory includes entrepreneurship, remote work, or asset-based income. |
Future Trends and Innovations
The next wave of "strong college students net worth" strategies will be shaped by automation, decentralized finance (DeFi), and the gig economy’s evolution. Students who can leverage AI tools to automate side income (e.g., using no-code platforms to build and sell digital products) will have a massive edge. Similarly, the rise of crypto and tokenized assets means that even small investments in emerging tech could yield outsized returns—if managed carefully. Another trend is the blurring of education and entrepreneurship: platforms like Y Combinator’s Startup School now offer college credit for entrepreneurial projects, allowing students to build businesses while fulfilling degree requirements. The biggest shift, however, may be in how institutions support wealth-building. Top universities are already piloting programs that teach personal finance as a core skill, not an elective. Some even offer micro-investing tools for students, where small amounts (as little as $5) are automatically invested in diversified portfolios. As these trends mature, the gap between students who treat college as a cost and those who treat it as an investment will only widen. The question isn’t whether "strong college students net worth" is sustainable—it’s how quickly the rest of the student body will catch up.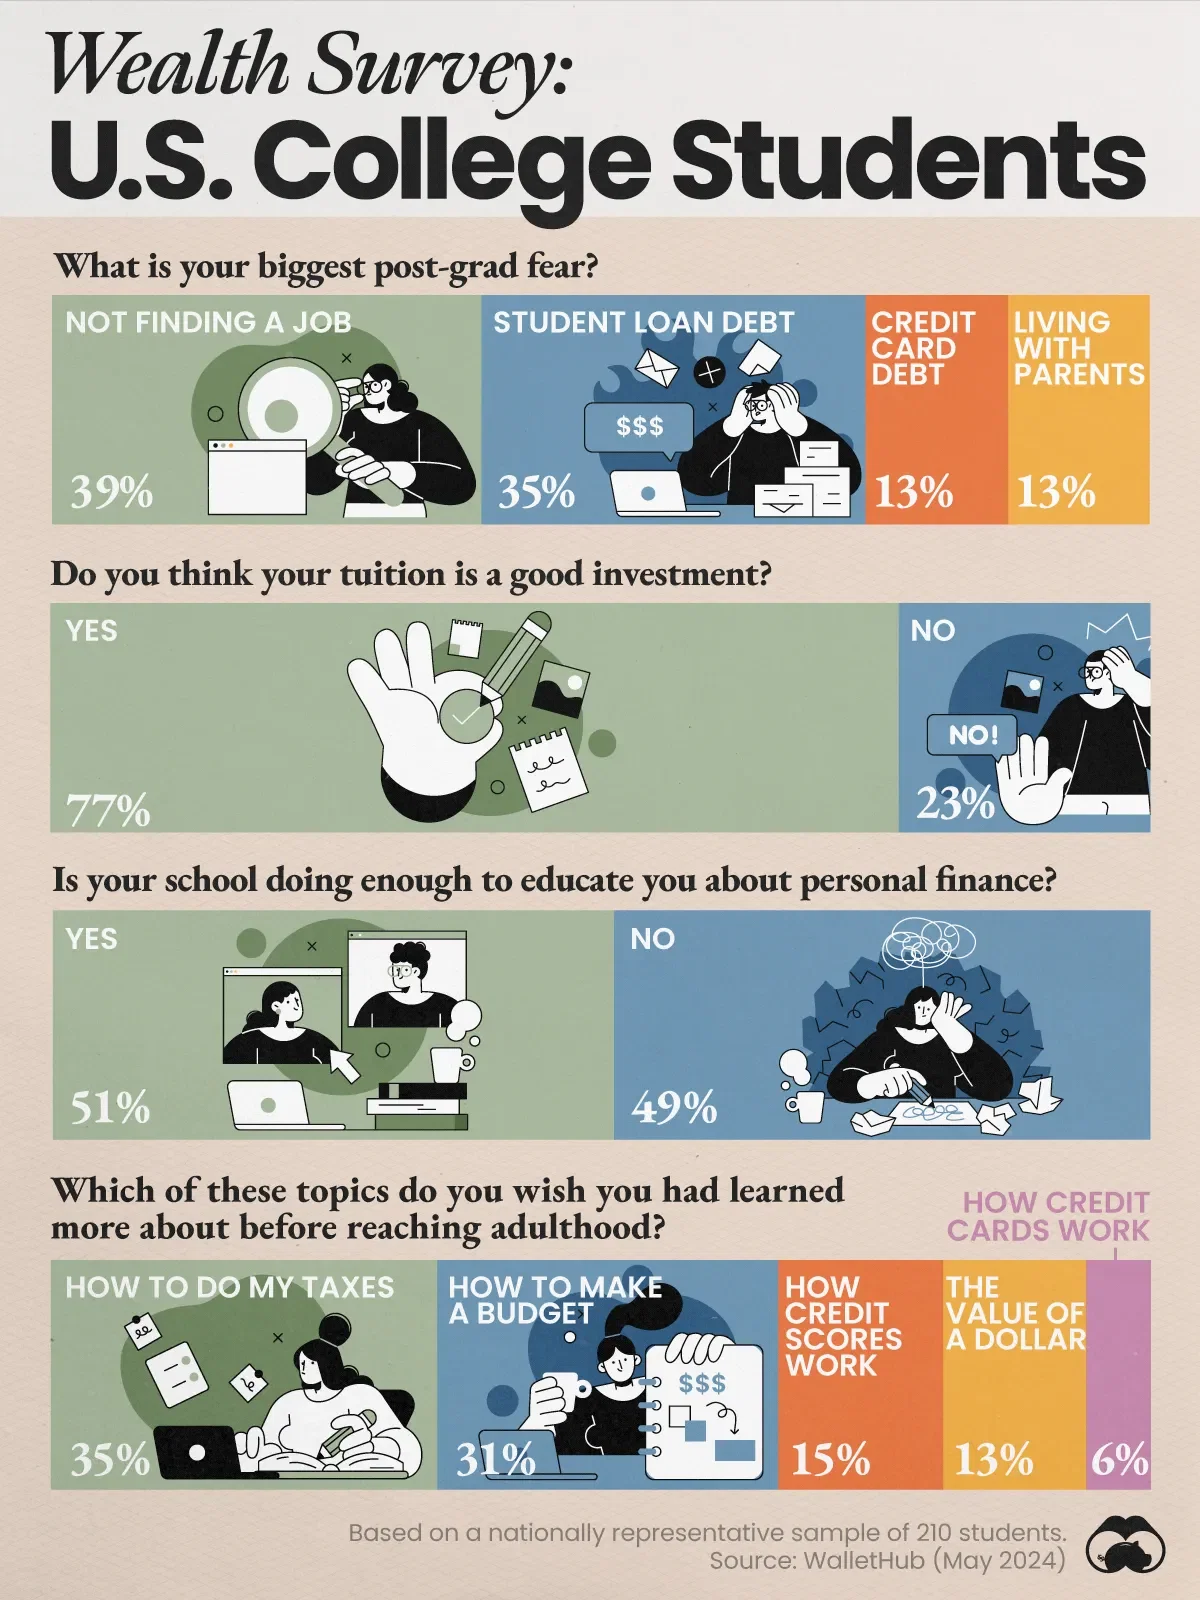
Conclusion
The most resilient graduates aren’t just those with the highest GPAs or the most prestigious internships—they’re the ones who engineer wealth while still in school. The playbook isn’t complex: earn aggressively, invest early, and treat college as a compressed career. The students who do this don’t just avoid debt; they build assets that appreciate over time. The long-term payoff? A net worth that grows exponentially, a career with more options, and financial security that most graduates can only dream of. The barrier to entry isn’t intelligence or connections—it’s discipline and early action. For those who master it, the rewards are life-changing. The best time to start building a "strong college students net worth" was four years ago. The second-best time? Today.Comprehensive FAQs
Q: Can a student with no prior business experience build a strong net worth in college?
A: Absolutely. Many high-net-worth students start with low-barrier entry opportunities—freelancing, tutoring, or flipping items—and scale from there. The key is consistency: even small, recurring income streams (like $200/month from a side gig) can be reinvested into assets over time. Platforms like Fiverr, Upwork, or local gig apps (e.g., TaskRabbit) make it easy to monetize skills without prior experience.
Q: Is it realistic to graduate with a net worth of $50,000 or more?
A: Yes, but it requires aggressive execution. Students who combine multiple income sources (e.g., a part-time job + freelancing + investments), live frugally, and avoid lifestyle inflation can achieve this. For example, a student who earns $15,000/year from a job, reinvests $5,000 into a Roth IRA (averaging 7% annual returns), and saves another $5,000 could see their investments grow to $30,000+ by graduation—before accounting for other assets like side businesses or real estate.
Q: What’s the biggest mistake students make when trying to build net worth in college?
A: Underestimating the power of compounding. Many students focus on earning more but neglect reinvesting. A $1,000 monthly income from a side hustle is meaningless if it’s all spent on dining out or subscriptions. The real wealth comes from reinvesting even small amounts—whether into index funds, a business, or skill development (e.g., courses that boost earning potential). Another mistake? Ignoring tax optimization—students who don’t contribute to Roth IRAs or take advantage of tuition deductions leave money on the table.
Q: Can international students build a strong net worth in the U.S.?
A: Yes, but with additional constraints. International students often face limited work hours (20 hrs/week on-campus during school, full-time during breaks). To compensate, they focus on high-ROI side hustles—like coding bootcamps, freelance writing, or e-commerce—that don’t require a social security number. Some also leverage remote internships or global freelance platforms (e.g., Upwork’s international clients). The key is maximizing remote opportunities and reinvesting earnings into assets that appreciate globally (e.g., ETFs, digital real estate).
Q: How does a student balance academics with wealth-building?
A: Time management is critical. High-net-worth students block-schedule their week: dedicated study hours, focused work blocks for side income, and automated systems (e.g., auto-investing apps) to handle finances without daily effort. They also prioritize high-leverage activities—like building a passive income stream (e.g., a YouTube channel or SaaS tool) that requires upfront work but pays off long-term. The goal isn’t to work 80 hours a week; it’s to optimize every hour for both learning and earning.
Q: Are there risks to building net worth too aggressively in college?
A: Yes, but they’re manageable. The biggest risks include burnout (overworking leads to poor academic performance) and poor investment choices (e.g., gambling on meme stocks or unproven startups). The solution? Diversify income streams (don’t rely on one side hustle) and stay disciplined—never invest money you can’t afford to lose. Another risk is social isolation; students who hyper-focus on wealth-building may miss networking opportunities. The fix? Balance financial hustle with strategic relationships (e.g., joining clubs that attract high-earning alumni).
Q: What’s the most underrated asset college students can build?
A: Career capital—the intangible value of skills, reputation, and connections that directly translate into earning power. A student who builds a strong personal brand (e.g., through LinkedIn, a portfolio, or open-source contributions) or secures high-profile internships isn’t just adding to their resume; they’re increasing their future salary potential by 20-40%. This is often more valuable than liquid cash because it appreciates over time—unlike a bank account balance, which stagnates without reinvestment.
Q: Can a student with average grades still build a strong net worth?
A: Yes, but the strategy shifts. Students with B/B+ averages focus on high-income skills (e.g., sales, tech, trades) and leverage alternative credentials (certifications, bootcamps, or freelance portfolios) to compensate for lower GPAs. They also prioritize career capital—networking aggressively, securing strong references, and targeting industries where skills matter more than degrees. The key insight? Net worth isn’t tied to academic performance—it’s tied to earning potential and asset accumulation. Many self-made millionaires dropped out of college or had mediocre grades but built wealth through execution and leverage.
