
The Short Answers
- Gulfstream’s exact valuation is private, but industry estimates place its enterprise value between $12–18 billion as of 2024, depending on methodology.
- The company’s worth is tied to defense contracts (e.g., C-37A, C-560) and luxury jet sales, which together account for over $10 billion in annual revenue for General Dynamics.
- Valuation fluctuates with supply chain risks, geopolitical tensions, and the cyclical nature of business jet demand—Gulfstream’s backlog hit $25+ billion in 2023 but faces delivery delays.
- Unlike public firms, Gulfstream’s value isn’t tied to a stock price; it’s derived from private equity multiples, EBITDA projections, and strategic asset assessments by General Dynamics.
Deep Dive: The Full Picture
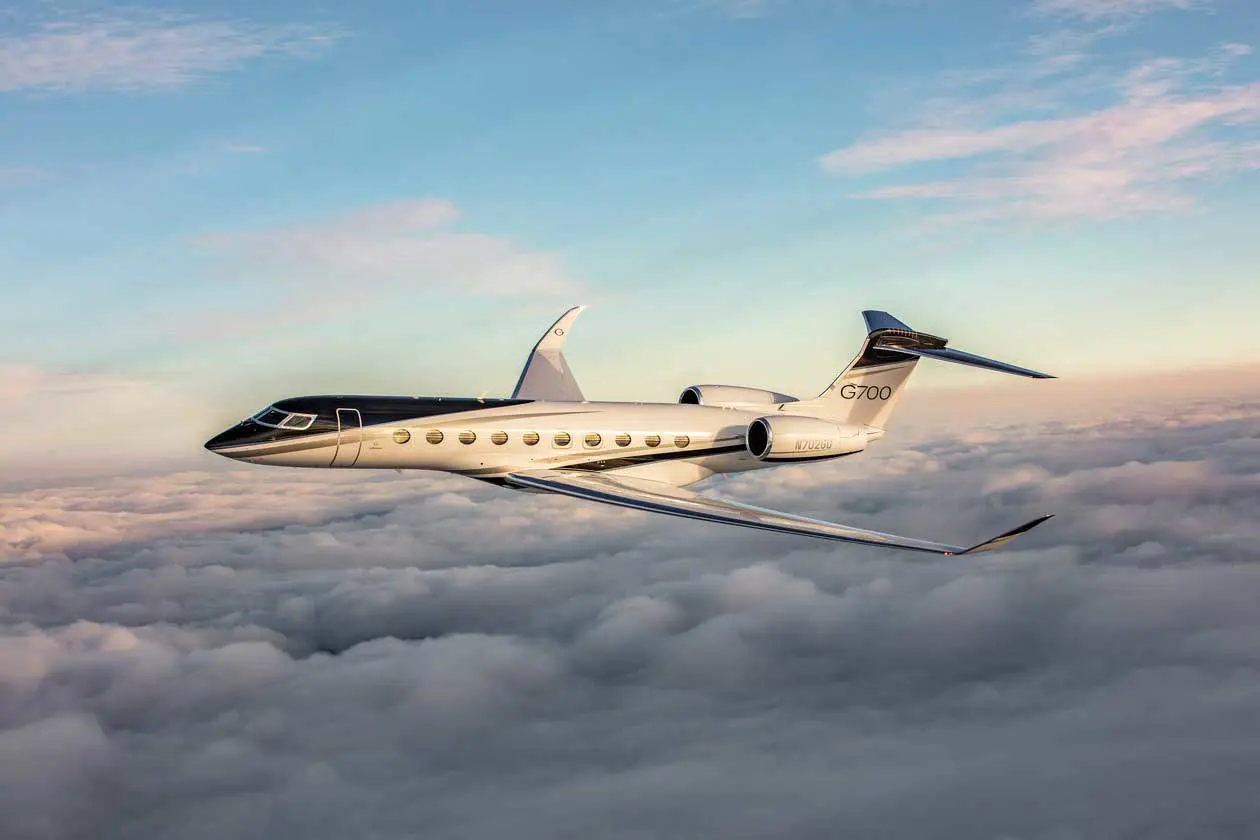
Gulfstream’s valuation isn’t static. It’s a function of three interlocking factors: its core business jet operations, its defense and government contracts, and the macroeconomic health of its primary markets—the U.S., Middle East, and Asia. The company’s luxury jets, like the G700 (priced at ~$75 million), are sold to clients who treat them as both assets and liabilities: assets because they generate revenue for private jet operators, liabilities because maintenance and fuel costs can exceed $1 million annually. Meanwhile, Gulfstream’s defense business—particularly its military transport variants—provides recurring revenue streams that are less volatile than commercial sales. This dual revenue model makes Gulfstream’s valuation more resilient than that of pure-play aviation firms. The challenge in answering how much is Gulfstream company worth lies in the absence of a transparent benchmark. Publicly traded peers like Textron Aviation or Bombardier provide guidance, but Gulfstream’s valuation is inferred from General Dynamics’ consolidated filings. For example, in 2022, Gulfstream contributed $9.5 billion to General Dynamics’ revenue, or roughly 50% of the parent company’s total. If you apply a private equity multiple (typically 6–10x EBITDA) to Gulfstream’s estimated $1.5–2 billion in annual profit, you arrive at a range of $9–20 billion. However, this is speculative—General Dynamics could hold Gulfstream at a lower multiple due to its integrated supply chain or higher due to its defense moat.The Context You Need
Gulfstream’s valuation isn’t just about today’s numbers; it’s about where the company is headed. The rise of electric VTOLs (e.g., Joby Aviation) and the shift toward sustainability could disrupt the business jet market, but Gulfstream’s defense contracts—particularly with the U.S. Air Force and Navy—act as a hedge. In 2023, the company secured a $1.2 billion contract to upgrade C-37A aircraft, a deal that extends its revenue visibility for years. Meanwhile, its commercial backlog remains robust, with 1,300+ aircraft on order as of early 2024, though delivery delays due to supply chain bottlenecks have tested investor patience. Another layer is ownership intent. General Dynamics has never seriously considered selling Gulfstream, but if it did, the valuation would hinge on whether a buyer saw it as a standalone luxury brand (like Ferrari) or a defense-adjacent manufacturer. Private equity firms like Carlyle or Blackstone might pay a premium for Gulfstream’s niche expertise in large-cabin jets, while a strategic buyer like Boeing or Airbus could see it as a way to enter the ultra-high-end market. The last time Gulfstream’s sale was seriously discussed (2018), rumors suggested $15–20 billion, but the deal collapsed over integration concerns.The Mechanics
To estimate what Gulfstream’s valuation might be, analysts typically use DCF (Discounted Cash Flow) models or comparable company analysis. A DCF approach would project Gulfstream’s free cash flows over 10 years, discounting them back to present value using a WACC (Weighted Average Cost of Capital) of ~8–10%. Given its defense exposure, Gulfstream’s WACC is lower than a pure-play luxury goods firm but higher than a mature aerospace contractor. Comparable company analysis, meanwhile, would look at firms like Bombardier Business Aircraft (sold for $6.3 billion in 2020) or VistaJet (valued at ~$1.5 billion), though Gulfstream’s scale and defense ties make direct comparisons difficult. One often-overlooked factor is Gulfstream’s intellectual property. The company holds patents for avionics systems, composite materials, and engine integration that are valuable to competitors. In 2021, a leaked internal document suggested Gulfstream’s IP portfolio could be worth $1–2 billion alone, though this was never verified. Add in its manufacturing facilities in Savannah, Georgia—a $1.5 billion asset in its own right—and the valuation puzzle becomes clearer. The company’s brand equity also plays a role; Gulfstream isn’t just selling jets—it’s selling exclusivity, a premium that private buyers pay for.Details That Change the Picture
Gulfstream’s valuation isn’t just about revenue—it’s about risk-adjusted returns. The company’s backlog visibility (a key metric for private equity) has been a bright spot, but supply chain disruptions (e.g., shortages of titanium or avionics chips) have pushed delivery timelines out by 12–18 months. This delays revenue recognition, which can temporarily depress valuation multiples. Meanwhile, geopolitical risks—such as U.S.-China tensions or Middle East instability—can dry up sales in key markets like Dubai or Singapore. Gulfstream’s customer concentration is another wild card: the top 10 buyers account for ~40% of its revenue, meaning a single client’s decision can swing valuation estimates by billions. The tax implications of a potential sale also matter. If General Dynamics were to spin off Gulfstream, it could trigger capital gains taxes on the original 1999 acquisition price. This could reduce the net proceeds by 20–30%, making a sale less appealing unless Gulfstream’s valuation surged. Conversely, if Gulfstream remained under General Dynamics, its value would be embedded in the parent’s enterprise value, making it harder to isolate. This is why strategic buyers (like a sovereign wealth fund) might pay more than financial buyers—because they’re less concerned with tax efficiency and more with long-term control."Gulfstream’s valuation is like a Swiss watch—it’s not just about the movement inside, but the craftsmanship, the heritage, and the trust that comes with it. A private equity firm might see a balance sheet, but a strategic buyer sees a brand that’s synonymous with power and prestige." — Aerospace M&A analyst, 2023
| Metric | Estimated Value (2024) |
|---|---|
| Revenue Contribution to General Dynamics | $9.5–10.5 billion (50% of parent’s total) |
| Backlog Value | $25+ billion (as of Q1 2024) |
| Private Equity Valuation Multiple (6–10x EBITDA) | $12–20 billion |
| Defense Contract Backlog (C-37A, C-560) | $5–7 billion (multi-year commitments) |
| Potential Spin-Off Value (if sold) | $15–25 billion (speculative, based on 2018 rumors) |

Conclusion
The question of how much is Gulfstream company worth has no single answer, but the range is narrowing. At its core, Gulfstream’s valuation is a reflection of two markets: the luxury aviation sector, where every jet is a bespoke experience, and the defense aerospace sector, where reliability and security outweigh cost. The company’s ability to navigate supply chain crises, geopolitical shifts, and changing buyer preferences will determine whether its valuation stays in the $12–18 billion range or climbs higher. For now, Gulfstream remains a hidden gem—valued not just for what it earns today, but for what it could command in the right hands. What’s clear is that Gulfstream isn’t just a manufacturer; it’s a strategic asset. Its worth isn’t measured in quarterly earnings alone but in decades of engineering excellence, a global dealer network, and the unmatched prestige of its aircraft. Whether you’re a private equity firm, a defense contractor, or a high-net-worth buyer, Gulfstream’s valuation is less about spreadsheets and more about what it represents: speed, exclusivity, and American aerospace dominance. And in a world where those things are increasingly scarce, that kind of value is priceless.Comprehensive FAQs
Q: Why doesn’t Gulfstream disclose its valuation?
Gulfstream operates as a private subsidiary of General Dynamics, meaning its financials are consolidated into the parent company’s reports. Disclosing a standalone valuation would require restructuring its reporting, which General Dynamics has no incentive to do. Additionally, competitive sensitivity plays a role—revealing Gulfstream’s worth could attract unwanted attention from regulators, competitors, or potential buyers looking to exploit perceived weaknesses.
Q: How does Gulfstream’s valuation compare to other private aviation firms?
Gulfstream’s estimated $12–18 billion valuation dwarfs that of its peers. For context:
- VistaJet (private jet operator): ~$1.5 billion
- NetJets (before IPO): ~$5 billion (2014)
- Bombardier Business Aircraft (at sale): $6.3 billion (2020)
Q: Could Gulfstream’s valuation drop if defense contracts decline?
Yes, but the impact would be mitigated by its commercial backlog. Gulfstream’s defense business accounts for ~30–40% of its revenue, but its $25+ billion commercial backlog provides a cushion. However, a prolonged downturn in defense spending (e.g., post-U.S. election shifts) could force Gulfstream to delay new programs, reducing its long-term valuation. The bigger risk isn’t immediate revenue loss but lost momentum in R&D, which could erode its technological moat over time.
Q: Has Gulfstream ever been sold or partially divested?
No, Gulfstream has never been sold as a standalone entity. The closest was in 1999, when General Dynamics acquired it for $1.6 billion. Since then, there have been rumors of spin-offs or partial sales, particularly in 2018 and 2021, but none materialized. General Dynamics has consistently treated Gulfstream as a core asset, using it to diversify away from traditional defense while maintaining its luxury aviation leadership. A sale would require a strategic buyer willing to pay a premium for its brand, IP, and backlog—something few have been willing to do at the right price.
Q: What would trigger Gulfstream’s valuation to spike?
Several factors could push Gulfstream’s valuation toward the upper end of estimates ($20+ billion):
- A successful IPO or spin-off, proving its standalone profitability.
- A major defense contract win (e.g., a new C-XX program replacing aging aircraft).
- Supply chain stabilization, reducing delivery delays and boosting backlog conversion.
- A strategic acquisition by a sovereign wealth fund (e.g., Mubadala, ADIA) seeking luxury aviation assets.
- Technological breakthroughs (e.g., hybrid-electric engines or AI-driven avionics) that redefine the business jet market.
