
Where It All Began
The modern concept of "define ultra high net worth individual" traces back to the late 1980s, when credit agencies and private banks first needed a way to segment their wealthiest clients. Before then, "high net worth" was a vague term—often applied to anyone with a few million in assets. But as global capital markets expanded, so did the need for precision. The first formal thresholds emerged in the early 1990s, when banks like UBS and Credit Suisse began categorizing clients based on liquid asset holdings. Initially, the cutoff was set at $1 million, but by 1995, the term "ultra high net worth" began appearing in internal documents, reserved for individuals with $30 million or more in investable assets. The shift wasn’t just semantic. It reflected a broader transformation in how wealth was structured. The post-Cold War era saw the rise of private equity, hedge funds, and offshore trusts—tools that allowed the ultra-wealthy to fragment their portfolios in ways that traditional banking couldn’t track. The first true UHNWIs weren’t just rich; they were architects of financial opacity. Take the case of a German industrialist who, in 1998, restructured his empire through a series of Dutch and Cayman Islands entities. His net worth was publicly listed at €1.2 billion, but his liquid, deployable capital—the kind that mattered to banks—was closer to €300 million. That discrepancy became the first clue that the definition of "define ultra high net worth individual" wasn’t about gross assets, but about operational wealth.The Early Signs
By the late 1990s, the signs were everywhere—if you knew where to look. The first was the exodus from public markets. While the S&P 500 was booming, the ultra-wealthy were pulling capital into private placements, family offices, and unlisted ventures. A 1999 study by Boston Consulting Group noted that the top 0.1% of wealth holders had only 10% of their assets in publicly traded stocks—a stark contrast to the broader population. The second sign was the rise of "quiet wealth"—fortunes built not through IPOs or media headlines, but through real estate syndicates, timberland investments, and minority stakes in niche industries. The third, perhaps most telling, was the jurisdictional arms race. As governments tightened capital controls, the ultra-wealthy began diversifying across tax havens not just for legal reasons, but for operational flexibility. A Russian oligarch might hold assets in Monaco, a Swiss trust, and a Singaporean LLC—not because he loved the weather, but because each jurisdiction offered a different set of rules for inheritance, taxation, and asset seizure. The message was clear: "define ultra high net worth individual" wasn’t just about the size of the wallet; it was about the number of wallets.The Turning Point
The moment the definition of "define ultra high net worth individual" became a global obsession was September 11, 2001. The attacks didn’t just disrupt markets—they forced a reckoning with how wealth was hidden, moved, and protected. Overnight, banks realized that their "high net worth" clients weren’t just rich; they were systemically critical to the stability of private capital. The response? A scramble to redefine who qualified for the highest tiers of service. What changed wasn’t just the numbers. It was the velocity of capital. Before 9/11, a UHNWI might move $10 million through a single wire transfer. Afterward, the same individual would fragment that transfer into 50 transactions across 12 jurisdictions, each under a different legal structure. The turning point wasn’t a single event—it was the realization that wealth had become a moving target. Governments and regulators scrambled to adapt, but the ultra-wealthy had already one step ahead."The rich don’t just hide money—they make it impossible to find unless you’re invited to the table. That’s why the definition of 'ultra' isn’t about the balance sheet; it’s about the access code." — Anonymized interview, 2003, Monaco Private Banking Forum
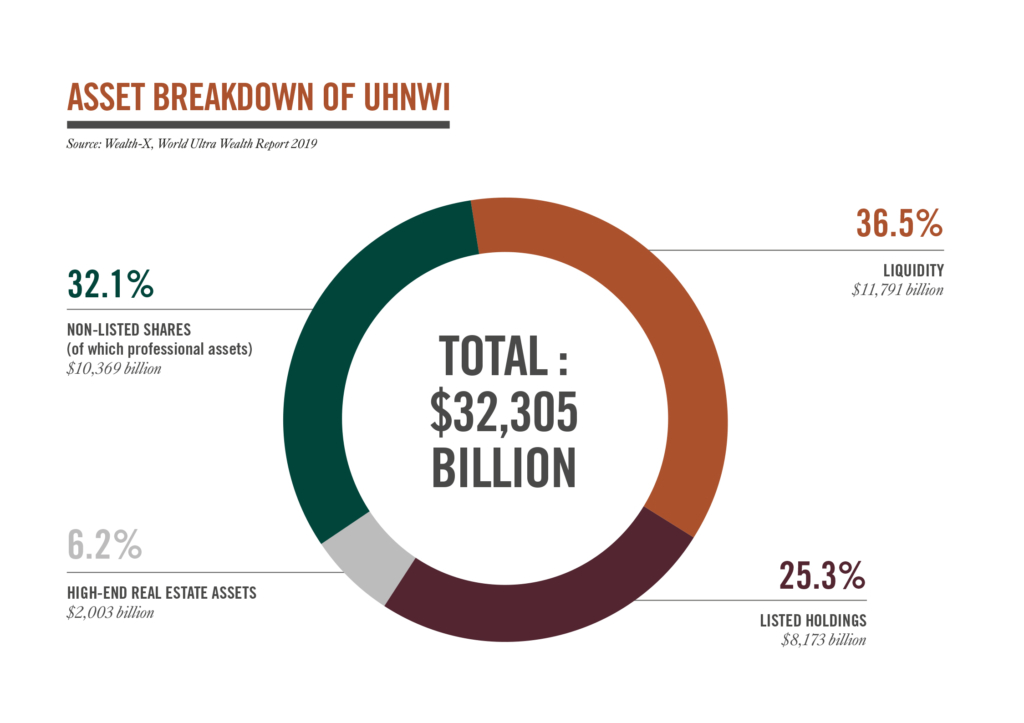
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2005–2008 | The rise of family offices as the primary vehicle for UHNWI asset management. Before this, wealth was managed by external firms; now, it was internalized—giving the ultra-wealthy direct control over liquidity and risk. The first "multi-family offices" emerged, pooling resources for ultra-high-net-worth families who wanted scale without losing privacy. |
| 2009–2015 | The digital disruption of wealth management. Cryptocurrencies and blockchain-based assets introduced a new layer of complexity—assets that could be held anonymously, moved instantly, and valued subjectively. The first UHNWIs began allocating 1–5% of portfolios to digital assets not for speculation, but for jurisdictional arbitrage (e.g., holding Bitcoin in a Swiss trust to avoid capital gains taxes). |
| 2016–Present |
The fragmentation of wealth metrics. Traditional definitions (e.g., $30M+ liquid assets) became obsolete as the ultra-wealthy redefined liquidity. A $500 million portfolio might include:
|
Lessons From the Journey
- Liquidity is a spectrum. The ultra high net worth individual doesn’t just have money—they have money that moves on their terms. A $1 billion fortune tied to a single company? Not ultra. A $1 billion fortune with $300 million in liquid cash and $700 million in diversified, deployable assets? Now we’re talking.
- Jurisdictional diversity is non-negotiable. The more borders your wealth crosses, the harder it is to freeze. The ultra-wealthy don’t just hold assets in tax havens—they hold assets in tax havens that don’t communicate with each other.
- Privacy is the ultimate currency. The ability to opt out of public scrutiny is worth more than most people realize. A UHNWI might willingly pay a 2% premium on a loan if it means avoiding a Forbes cover story that could trigger regulatory scrutiny.
- Dynastic wealth requires dynastic planning. The ultra-wealthy don’t just pass money to heirs—they pass control. Trusts, dynastic trusts, and multi-generational wealth vehicles ensure that the family remains operationally ultra even if the gross assets fluctuate.
- Illiquid assets are the silent majority. For every $1 in publicly traded stocks, a UHNWI might hold $3 in private assets—real estate, fine art, collectibles, or even undervalued natural resources. These don’t show up in standard wealth rankings.
- The definition is self-reinforcing. The more you act like an ultra high net worth individual (by structuring wealth in specific ways), the more banks, governments, and peers treat you like one—even if the numbers don’t perfectly align.
Where Things Stand Today
Today, the phrase "define ultra high net worth individual" is less about a fixed number and more about a behavioral profile. The traditional $30 million liquid assets threshold still exists in banking circles, but it’s meaningless without context. What matters now is how that wealth is structured. The ultra-wealthy of 2024 don’t just have money—they have financial ecosystems. Consider the case of a tech billionaire who holds: - $200 million in a Delaware LLC (private equity stakes) - $150 million in a Singaporean trust (real estate) - $100 million in a Liechtenstein foundation (art and wine) - $50 million in a Swiss bank account (liquid, but under a pseudonym) - $20 million in a Monaco-based family office (operational capital) Their gross net worth might be $520 million—but their operational ultra status is what grants them access to the Pandora Papers-level privacy, the private jet charters to hard-to-reach markets, and the invitation-only investment clubs. The definition has become performative. The other evolution? The rise of the "stealth ultra." These are individuals who deliberately avoid being labeled as ultra high net worth—because the label comes with unwanted attention. A stealth ultra might have a $400 million portfolio but only $5 million in publicly listed assets, ensuring they fly under the radar of tax authorities and media scrutiny.
Conclusion
The story of "define ultra high net worth individual" is the story of how wealth became a language. It’s not just about the size of the fortune; it’s about the rules of the game. The ultra-wealthy don’t just accumulate money—they rewrite the definitions of what money can do. They turn assets into passports, privacy into power, and illiquidity into strategic advantage. The most dangerous myth about UHNWIs is that they’re just rich. In reality, they’re architects of financial sovereignty—people who have spent decades ensuring that no single government, no single bank, and no single market can fully understand or control their wealth. That’s why the definition will never be static. It will keep evolving, just like the strategies of those who live by it.Comprehensive FAQs
Q: What’s the exact threshold to be considered an ultra high net worth individual?
There’s no single, universally accepted number. Credit Suisse and UBS historically used $30 million in liquid assets as a baseline, but this is outdated. Today, the definition depends on asset structure, liquidity, and jurisdictional diversity. A $50 million portfolio with no liquidity won’t qualify, while a $100 million portfolio fragmented across 5 jurisdictions with $20 million in cash might. The key is operational flexibility.
Q: Can someone with a $100 million fortune be excluded from the ultra category?
Absolutely. If that $100 million is locked in a single, illiquid asset (e.g., a single company or a vineyard), it won’t meet the operational ultra standard. The ultra-wealthy don’t just have money—they have money that can be deployed, hidden, or moved at will. A $100 million fortune in cash equivalents across 3 tax havens? That’s ultra. A $100 million fortune in one unlisted business? Not even close.
Q: How do ultra high net worth individuals avoid taxes?
They don’t "avoid" taxes—they optimize them. Legal strategies include:
- Jurisdictional layering: Holding assets in countries with no capital gains tax (e.g., Monaco, Singapore) while living in a low-tax jurisdiction (e.g., Switzerland, UAE).
- Trust structures: Using dynastic trusts in jurisdictions like Liechtenstein or the Cayman Islands to defer or eliminate inheritance taxes.
- Asset fragmentation: Spreading wealth across private equity, real estate, and illiquid assets that depreciate slowly (e.g., art, wine), reducing taxable income.
- Currency arbitrage: Holding portions of wealth in strong, stable currencies (CHF, USD, GBP) to minimize exchange-rate losses during transfers.
Q: Is there a difference between a high net worth individual and an ultra high net worth individual?
Yes—and it’s bigger than you think. A high net worth individual (HNWI) typically has $1 million to $30 million in liquid assets and relies on standard banking, brokerage, and investment advisory services. An ultra high net worth individual (UHNWI) has:
- $30 million+ in liquid/deployable assets (but often much more).
- Access to private markets (e.g., direct deals with PE firms, sovereign wealth funds).
- Customized legal and tax structures (e.g., family offices, multi-jurisdictional trusts).
- Global mobility privileges (e.g., golden visas, diplomatic passports, private aviation networks).
- Illiquid asset dominance (e.g., 60–80% of net worth in private equity, real estate, or collectibles).
Q: Can someone become an ultra high net worth individual overnight?
No—but they can accelerate the process. Overnight wealth (e.g., from an IPO, sports contract, or lottery) rarely translates to ultra status because:
- Liquidity constraints: A sudden $50 million windfall might be locked in stocks or a single asset, making it non-operational.
- Tax and legal hurdles: Governments often freeze or scrutinize large, sudden inflows.
- Lack of infrastructure: Ultra wealth requires decades of trust-building with private banks, lawyers, and asset managers.
Q: What’s the most common mistake people make when trying to join the ultra category?
Assuming more money = ultra status. The biggest mistake is focusing only on gross net worth while ignoring:
- Liquidity: Having $200 million in a single company doesn’t count.
- Jurisdictional diversity: Holding everything in one country (even a tax haven) is a red flag.
- Privacy: Ultra wealth requires operational anonymity—not just hiding money, but structuring it so no single entity can trace it.
- Networks: Access to private capital, exclusive deals, and global mobility depends on who you know, not just how much you have.
Q: Are there any ultra high net worth individuals who deliberately avoid the label?
Yes—they’re called "stealth ultra" individuals. Some reasons:
- Media scrutiny: A Forbes cover story can trigger regulatory investigations, kidnapping risks, or business disruptions.
- Legal exposure: In some countries (e.g., Russia, China), publicly declaring ultra wealth can lead to asset seizures or political targeting.
- Social dynamics: Some ultra-wealthy prefer low-key luxury (e.g., private jets instead of yachts, discreet real estate) to avoid attention from rivals or governments.
- Investment flexibility: Being under the radar allows access to restricted deals (e.g., sovereign wealth fund partnerships, pre-IPO stakes).
