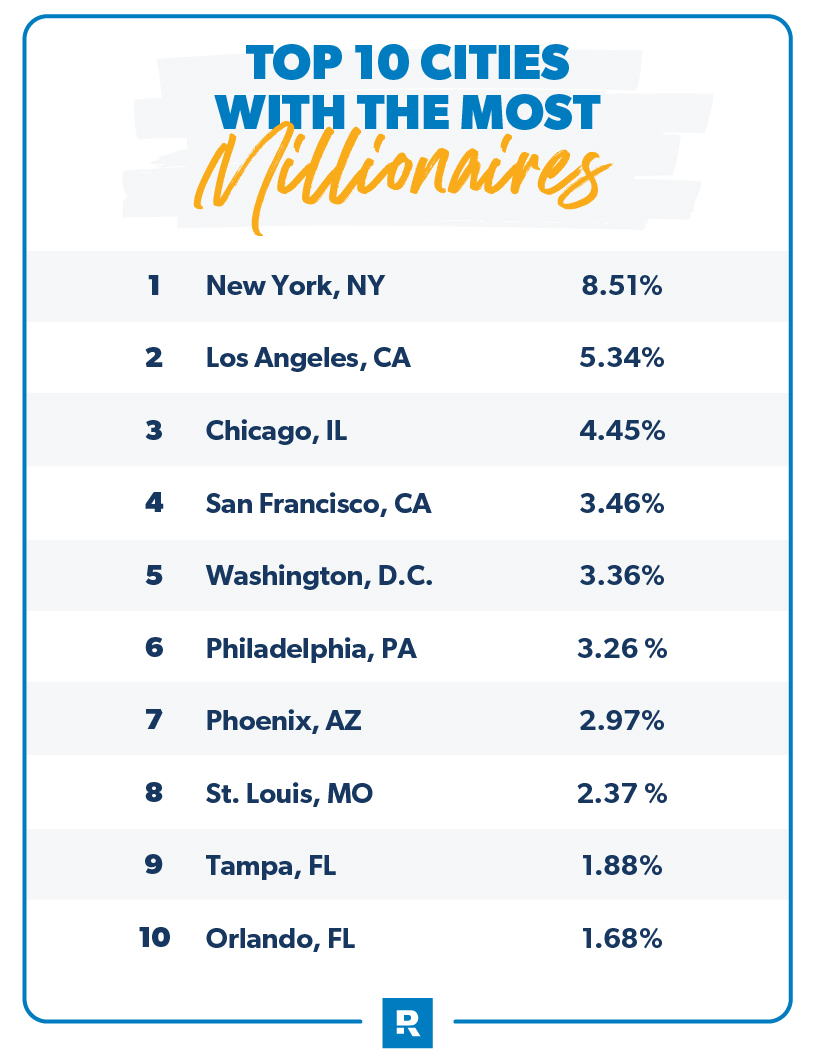
Breaking Down the Numbers
The most reliable starting point is Spectrem Group’s 2023 Millionaire Census, which pegged the U.S. millionaire household count at 23.1 million. This represents roughly 7% of all U.S. households, a share that has doubled since the 2008 financial crisis. The growth isn’t uniform. The firm’s data shows Florida added 1.3 million millionaires between 2020 and 2023 alone, while California’s millionaire population stagnated due to high taxes and housing costs. Texas, meanwhile, saw its millionaire ranks swell by 1.1 million in the same period, driven by remote work flexibility and lower cost of living in secondary cities. These shifts underscore a broader trend: the millionaire class is no longer confined to coastal elites. It’s dispersing, following capital and opportunity. The millionaire count is also a function of time. A household that crosses the threshold today may not retain that status in a downturn. Spectrem’s data accounts for net worth, not annual income, meaning a single windfall—an IPO, a real estate sale, or even a well-timed inheritance—can propel a family into the millionaire ranks overnight. This volatility explains why some estimates fluctuate wildly. The Federal Reserve’s 2022 report suggested the number of millionaire households could be as high as 25 million when including all forms of wealth, from stocks to business equity. The discrepancy highlights a fundamental truth: how many millionaires are there in America depends on how you define wealth—and who you ask.The Verified Baseline
The most defensible figure comes from the Federal Reserve’s triennial Survey of Consumer Finances (SCF), the gold standard for U.S. wealth data. The 2022 SCF, released in 2023, confirmed that the top 10% of households held 70.3% of all liquid assets, a figure that aligns with other high-income countries but stands out for its extremity. Within that top decile, the millionaire segment—households with net worth exceeding $1 million—accounted for roughly 3.5 million when excluding primary residences. Including home equity, that number jumps to 12.7 million. The SCF’s methodology is rigorous: it surveys 6,000 households annually, adjusting for inflation and asset types. What the SCF doesn’t capture is the shadow millionaire population: those whose wealth is tied to private businesses, illiquid assets, or offshore accounts. The Tax Policy Center estimates that undercounting in tax filings could inflate the true millionaire count by 15-20%. This gap is particularly wide in sectors like real estate and private equity, where valuations are harder to pin down. For example, a family that owns a $3 million rental portfolio may not appear in tax records at that value until assets are sold. This opacity is why some analysts argue the actual number of millionaires in America could exceed 25 million—but without verifiable data, such claims remain speculative.What the Estimates Suggest
Private wealth research firms fill the gaps left by government data. Spectrem Group’s 2024 projections suggest the millionaire count will reach 24 million by year-end, driven by S&P 500 gains and commercial real estate rebounds. Their data also highlights a generational shift: millennials now represent 30% of millionaires, up from 20% a decade ago. This isn’t just about younger tech founders; it’s about index fund investors, real estate flippers, and even side-hustle entrepreneurs who’ve leveraged low-interest rates to build wealth. The firm’s Wealth Monitor tracks spending habits of this group, revealing that 78% of new millionaires prioritize financial security over luxury, a stark contrast to the lavish displays of older generations. Industry estimates also point to geographic outliers. New York and California—long the millionaire magnets—have seen net outmigration of high-net-worth individuals to Texas, Florida, and Tennessee, where no state income tax and business-friendly policies create fertile ground for wealth accumulation. The Institutional Brokers’ Estimate System (IBES) data shows that Texas added more millionaires in 2023 than any other state, a trend linked to remote work policies and lower regulatory burdens. These shifts aren’t just statistical; they’re reshaping local economies. Cities like Austin and Dallas are seeing luxury home prices surge as millionaires relocate, while traditional finance hubs like Chicago and Boston struggle to retain wealth holders.
Case Study: A Closer Look
Consider the rise of Atlanta as a millionaire hub. A decade ago, the city’s wealth landscape was dominated by legacy fortunes tied to Coca-Cola and Delta. Today, it’s a story of new money: tech transplants from Silicon Valley, crypto founders, and real estate developers who’ve capitalized on the city’s affordability. The Federal Reserve Bank of Atlanta’s 2023 report noted that millionaire households in metro Atlanta grew by 18% annually between 2021 and 2023, outpacing national averages. This growth isn’t accidental. It’s the result of tax incentives for businesses, a booming logistics sector, and a younger, more entrepreneurial population. What’s striking isn’t just the numbers, but the mechanisms driving them. A deeper dive into Atlanta’s millionaire pipeline reveals three key factors:| Factor | Estimated Impact |
|---|---|
| Tech Transplants | Companies like Home Depot and Coca-Cola have attracted high-paying remote roles, with many employees reinvesting in local real estate. |
| Crypto and Venture Capital | Atlanta’s venture capital ecosystem has grown 40% since 2020, with early-stage founders seeing liquidity events that push them into seven figures. |
| Real Estate Arbitrage | Developers buying undervalued properties in suburbs like Alpharetta and Johns Creek, then flipping them at 2-3x original cost during the post-pandemic housing boom. |
| Legacy Wealth Reinvestment | Older millionaires, many tied to Delta Airlines, are diversifying into private equity and tech startups, keeping capital within the state. |
"We’re not just seeing millionaires move to Atlanta—we’re seeing millionaires being made here. The difference is critical." — Mark Zandi, Chief Economist at Moody’s Analytics
What This Means Going Forward
The millionaire count isn’t just a vanity metric. It’s a leading indicator of economic health. When the number climbs, it often signals strong asset appreciation, low interest rates, and consumer confidence. But when growth stalls—or worse, reverses—it’s a sign of stagnation or inequality. The 2022-2023 slowdown in millionaire growth, for example, correlated with rising interest rates and geopolitical uncertainty, proving that wealth accumulation is never linear. The question now is whether the current expansion is sustainable—or if it’s another bubble waiting to burst. The bigger picture is structural. The U.S. millionaire population is growing, but the composition is changing. Fewer millionaires today rely on pensions or stable corporate jobs; more depend on volatile assets like stocks, crypto, or real estate. This shift increases systemic risk: a market correction could wipe out millions of households that are just one bad quarter away from falling out of the millionaire ranks. Meanwhile, the ultra-wealthy—the top 0.1%—are seeing their fortunes grow at a far faster clip, deepening inequality. The result? A two-tiered economy: one where millionaires are increasingly common, but true financial security remains elusive for most.Conclusion
The answer to how many millionaires are there in America is less important than what the question reveals. It exposes a wealth system in flux, where old rules no longer apply and new ones are still being written. The millionaire count is a barometer, not a destination. It tells us that asset ownership is the new class marker, that geography is no longer destiny, and that wealth is more liquid—and more precarious—than ever. For policymakers, the data is a call to action: if millionaire growth is concentrated in a handful of states and sectors, what does that mean for regional inequality? For individuals, it’s a reminder that a million dollars today doesn’t buy what it did 20 years ago—and that the path to joining that club is getting harder for those without existing advantages. The millionaire population will keep rising, but the terms of entry are changing. The question isn’t just about numbers; it’s about who gets to play the game—and who gets left behind.Comprehensive FAQs
Q: How does inflation affect the millionaire count?
The millionaire threshold isn’t adjusted for inflation in most surveys, meaning a $1 million net worth in 2000 would require $1.7 million today to maintain the same purchasing power. Spectrem Group’s data accounts for real net worth, but government reports like the SCF often use nominal figures, leading to discrepancies. For example, a household that was a millionaire in 2010 may no longer qualify today due to rising home prices and healthcare costs, even if their assets have grown.
Q: Are most millionaires self-made or inherited wealth?
Spectrem’s data shows that 60% of millionaires under 45 are self-made, often through entrepreneurship, real estate, or tech, while inherited wealth dominates among those over 65. However, the line is blurring: many "self-made" millionaires today leverage family networks (e.g., connections, early capital) to accelerate wealth-building. The Federal Reserve’s 2022 SCF found that 40% of millionaires had at least one parent in the top 20% of earners, suggesting intergenerational advantage plays a role even in "self-made" success stories.
Q: Which states have the highest millionaire growth rates?
Florida leads with annual growth of 8-10%, driven by tax migration and remote work. Texas follows closely (7-9% annually), thanks to business-friendly policies and no state income tax. States like Tennessee and North Carolina are also seeing double-digit growth in millionaire households, while California and New York have seen net declines due to high taxes and housing costs. The Tax Foundation’s 2023 report notes that states with the lowest tax burdens tend to attract the most new millionaires.
Q: Can a middle-class household become a millionaire in a decade?
It’s possible, but extremely rare without leverage or windfalls. The Spectrem Group’s "Millionaire Next Door" studies show that most millionaires achieve their status through frugality, asset appreciation, and delayed gratification—not high incomes. For example, a $100,000 salary saved at 10% annually could grow to $1.3 million in 30 years, but most middle-class households don’t save that aggressively. The real barrier is liquidity: without access to home equity loans, 401(k) matching, or inheritance, breaking the millionaire barrier takes decades of disciplined investing—or a single lucky break.
Q: How do millionaires in America compare to those in other countries?
The U.S. has more millionaires than any other country, but the concentration of wealth is far more extreme. According to Credit Suisse’s 2023 Global Wealth Report, the U.S. accounts for 36% of the world’s millionaires, but China and Japan combined hold nearly as many. The key difference? Wealth distribution: in Nordic countries, the top 10% hold ~50% of wealth, while in the U.S., that figure is ~70%. This means more Americans are millionaires, but fewer have true economic security—since wealth in the U.S. is more volatile and asset-dependent than in countries with stronger social safety nets.
