7 Things Worth Knowing About Walmart’s Protection Plan
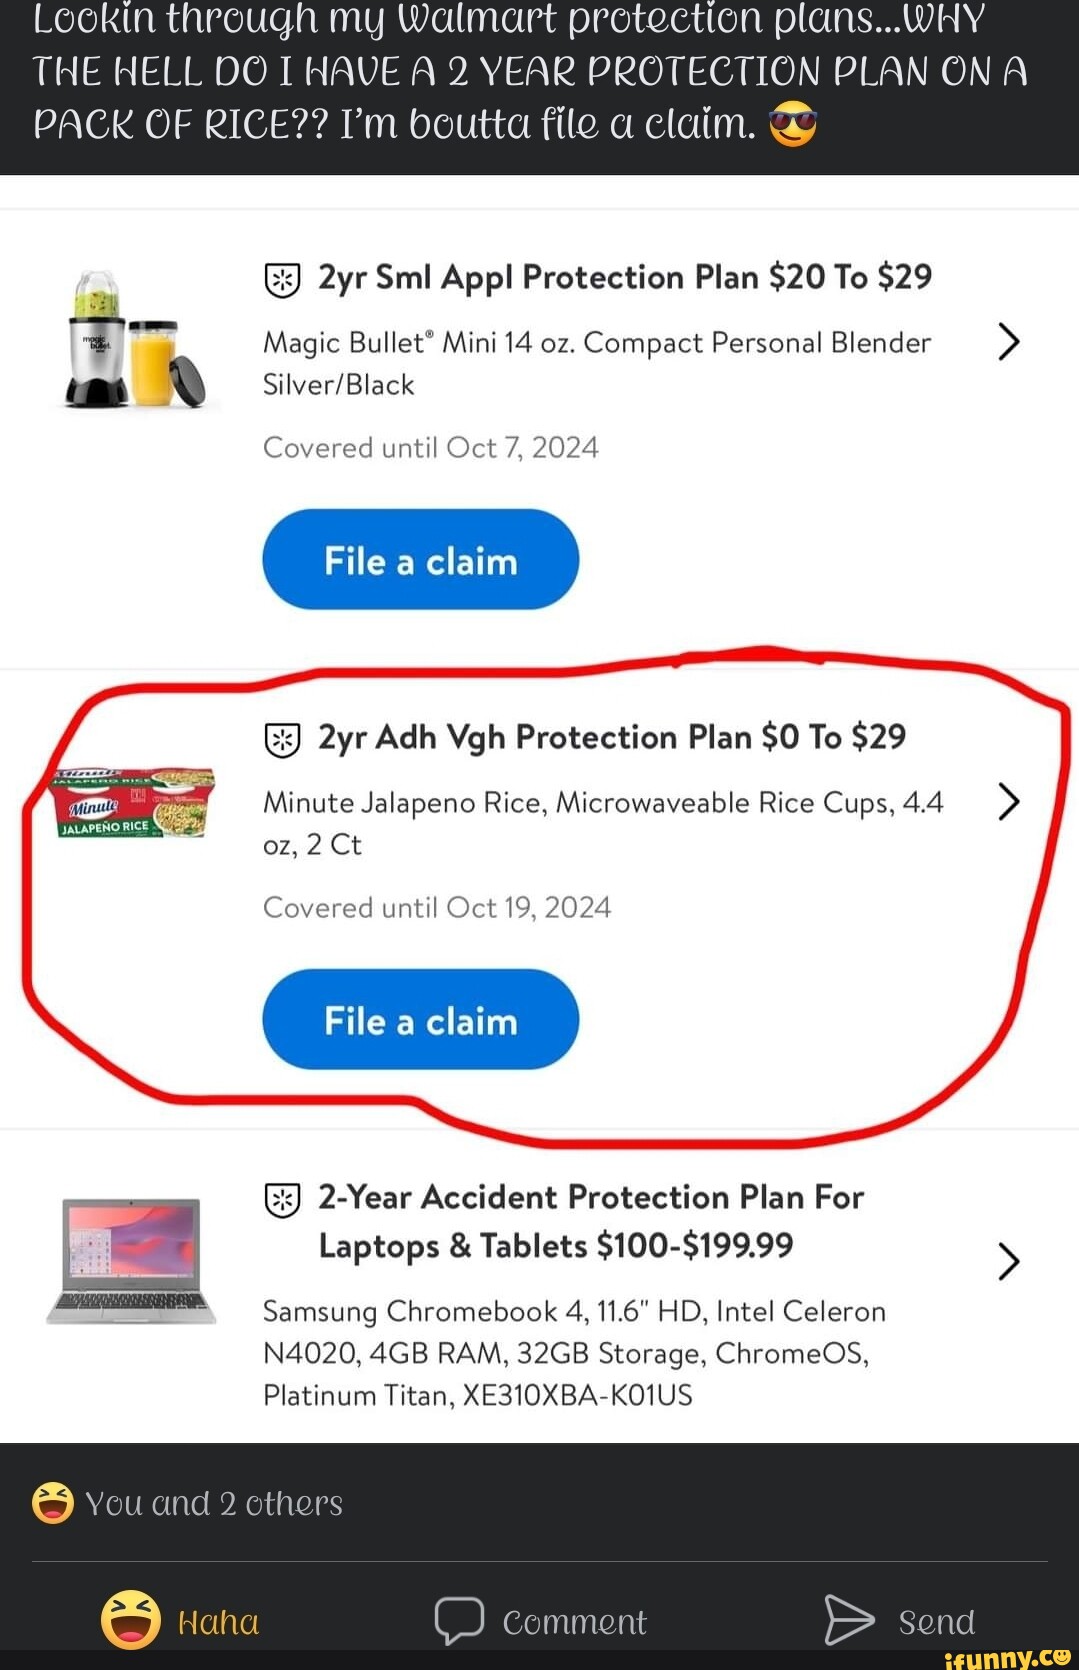
The Protection Plan at walmart.com/protection-plan operates on two levels: as a financial safeguard and as a psychological tool. On paper, it’s a straightforward proposition—extended coverage for accidental damage, normal wear and tear (in some cases), and even theft. But the devil lies in the details: deductibles, claim processes, and the fine print that often contradicts the marketing. Below are seven critical facts that define its true nature.1. It’s Not a True Warranty—It’s Insurance-Lite
Walmart’s Protection Plan is frequently mislabeled as an extended warranty, but it functions more like a limited insurance policy. Unlike manufacturer warranties, which cover defects, this plan focuses on accidental damage—dropped items, liquid spills, power surges. The distinction matters because it excludes pre-existing conditions, normal wear and tear (unless specified), and acts of God (like hurricanes). For example, a laptop with a cracked screen from a fall would qualify, but a battery that degraded over time would not. The plan’s language is deliberately vague, leaving room for Walmart to deny claims on technicalities. This insurance-lite model allows the retailer to keep premiums low while shifting risk to the customer through high deductibles or claim denials. The catch? The plan doesn’t replace manufacturer warranties—it supplements them. If an item already has a 1-year warranty from the brand, the Protection Plan might kick in after that period expires. But the coverage isn’t cumulative; it’s additive. This means a $1,000 TV with a 2-year manufacturer warranty could still leave you exposed for years three and beyond unless you renew the Protection Plan annually. The lack of long-term continuity is a major oversight for buyers who assume they’re future-proofing their purchase.2. Pricing Is Based on Perceived Risk, Not Actual Cost
The cost of walmart.com/protection-plan varies wildly depending on the item’s price tag, but the math rarely aligns with actuarial risk. A $500 smartphone might cost $30 to protect, while a $1,500 appliance could run $75. On the surface, that seems proportional—but dig deeper, and the logic unravels. The plan’s pricing is tied to transaction value, not replacement cost. So a $200 blender might have the same protection as a $2,000 refrigerator, even though the latter’s repair or replacement would be far more expensive. This disconnect suggests Walmart is pricing based on what customers are willing to pay at checkout, not what claims might actually cost. Industry estimates place the average claim payout at 20-30% of the item’s value, meaning Walmart’s profit margin on the plan is substantial. For a $1,200 TV protected for $50, the retailer stands to lose $240–$360 if a claim is filed. Yet the plan’s popularity suggests customers perceive the $50 as a small price for security. The asymmetry between risk and reward is where Walmart’s strategy shines: it’s betting that most customers won’t file claims, and those who do won’t exceed the payout cap.3. Claim Approval Isn’t Guaranteed—Even for Accidents
“Walmart’s Protection Plan is a gamble. You’re paying for the possibility of coverage, not the certainty of it. I’ve seen claims denied for ‘pre-existing damage’ even when the item was brand new.” —Retail fraud investigator, speaking on condition of anonymityThe marketing for walmart.com/protection-plan emphasizes accidental damage, but the reality is far stricter. Claims are subject to Walmart’s discretion, and the company has been known to reject payouts for: - Minor damage (e.g., a cracked screen with no functional impact). - Lack of proof (no photos, receipts, or police reports for theft). - User error (e.g., a phone dropped from waist height, deemed “foreseeable”). - Third-party modifications (e.g., a laptop with aftermarket parts). Even theft requires documentation—police reports, in many cases—which isn’t always practical. The burden of proof lies with the customer, and Walmart’s claim process is notoriously slow, often taking 30–60 days for approval. This creates a Catch-22: customers buy the plan to avoid out-of-pocket expenses, but the process of filing a claim can itself become costly in time and frustration.
4. It’s Often Bundled with Financing—And That Changes Everything
Walmart frequently pairs the Protection Plan with its Walmart Credit Card or layaway plans, creating a hidden cost structure. If you finance an item and add the plan, the protection cost is added to your monthly payments. This makes the plan seem cheaper upfront—$50 spread over 12 months is just $4.17—but the interest on the financing can erase any savings. For example, a $1,000 item with 24% APR financing and a $50 Protection Plan might cost $1,150+ by the time interest is factored in. The plan itself is now a $50 premium, but the financing turns it into a $150+ expense. The bundling strategy exploits a psychological quirk: customers focus on the immediate cost ($50) rather than the long-term financial impact. Walmart’s terms often require the plan to be purchased at the time of sale, removing the option to reconsider later. This tactic has drawn scrutiny from consumer advocacy groups, which argue it’s a form of deceptive pricing.5. Some Items Are Excluded—or Coverage Is Shockingly Limited
Not everything at walmart.com/protection-plan qualifies. High-value items like jewelry, art, or collectibles are often excluded unless specified. Even electronics have caveats: - Laptops and tablets: Coverage may not apply to liquid damage unless the plan is purchased within 30 days. - Appliances: Some models exclude mechanical failures (e.g., a fridge motor burning out). - Furniture: Accidental damage might cover a broken leg, but stains or fading are typically out of scope. The exclusions are buried in Walmart’s Product Protection Plan Terms, a document few customers read. This lack of clarity has led to disputes, with some shoppers discovering too late that their $2,000 smart TV isn’t covered for screen burn-in—a common issue with OLED displays.6. Competitors Offer More Flexible (But Often More Expensive) Alternatives
Walmart’s Protection Plan isn’t unique—Best Buy’s Geek Squad Protection, Amazon’s Accidental Damage Protection Plan, and Square Trade all provide similar coverage. The key differences lie in flexibility, payout speed, and exclusions: - Best Buy: Offers 24/7 repair/replacement for some items, but with higher upfront costs. - Amazon: Covers accidental damage and theft, but only for Prime members and with stricter proof requirements. - Square Trade: Provides multiple coverage tiers and home delivery for repairs, but at a premium. Walmart’s plan is cheaper upfront but lacks the hands-on service of competitors. For shoppers who value convenience over cost, alternatives like Square Trade might be worth the extra investment. However, for budget-conscious buyers, walmart.com/protection-plan remains the most accessible option—even if it’s not the most comprehensive.7. The Plan Can Be Renewed—But That’s Where It Gets Tricky
Unlike manufacturer warranties, which expire on a fixed date, Walmart’s Protection Plan requires annual renewal. This creates a subscription trap: customers must actively opt out each year or risk losing coverage. The renewal cost is often 50–70% of the original price, meaning a $50 plan could cost $75 the next year. For high-ticket items, this adds up quickly. A $1,500 appliance protected for $75 annually over 5 years would cost $375 in protection alone—more than some extended warranties from third parties. The renewal process is also non-transparent. Walmart doesn’t send reminders unless the customer has opted into marketing communications. This lack of proactive communication means many shoppers unintentionally let coverage lapse, leaving them vulnerable when accidents occur.
How These Facts Connect
Walmart’s Protection Plan is less about protecting products and more about managing consumer psychology. The company leverages loss aversion—the idea that people fear losses more than they value gains—to justify the plan’s cost. By framing protection as a must-have rather than a nice-to-have, Walmart taps into deep-seated anxieties about financial risk. The bundling with financing, the lack of long-term commitment, and the annual renewal cycle all serve to lock customers into repeat purchases, ensuring steady revenue from a service that may never pay off. The plan’s true value lies in its asymmetry: Walmart benefits from most customers never filing claims, while those who do often face high deductibles or bureaucratic hurdles. This model is sustainable because the cost of claims is low relative to the volume of sales. For every $100 spent on Protection Plans, Walmart might pay out $10–$20 in claims—a 90%+ profit margin on a service that feels essential to customers. The system works because it externalizes risk onto the retailer while making customers feel personally responsible for their purchases.| Fact | Key Takeaway | Consumer Impact |
|---|---|---|
| Insurance-lite model | Covers accidents, not defects | Limited to specific scenarios; excludes normal wear |
| Pricing based on transaction value | Cost doesn’t reflect actual risk | Overpriced for low-risk items, underpriced for high-risk |
| Claim approval isn’t guaranteed | Walmart retains discretion | Denials common for minor or ambiguous damage |
| Bundled with financing | Hidden cost structure | Interest erodes savings on the plan |
| Annual renewals required | Subscription model with increasing costs | Easy to forget; lapses leave customers exposed |
Conclusion
Walmart’s Protection Plan at walmart.com/protection-plan is a masterclass in retail psychology, blending affordability with enough ambiguity to keep customers second-guessing their purchases. For some, it’s a worthwhile safeguard—particularly for high-value items where accidental damage is a real concern. For others, it’s a financial trap, masking its true cost through clever bundling and opaque terms. The lack of transparency in claim approvals and the annual renewal cycle further tilt the balance against consumers. Yet, in a market where extended warranties are often overpriced and under-delivered, Walmart’s plan remains one of the most accessible options—even if it’s not the most ethical. The bottom line? Read the fine print. If you’re buying a $500 item, the plan might be a reasonable hedge. If you’re financing a $2,000 purchase, weigh the long-term cost against alternatives. And if you’re unsure, ask: Would I still buy this protection if I had to pay for it separately, without the upsell? The answer will tell you everything you need to know.Comprehensive FAQs
Q: Can I buy Walmart’s Protection Plan after purchase?
A: No. The plan must be purchased at the time of sale or within a short window (usually 30 days) for most items. Walmart does not offer retroactive coverage.
Q: Does the Protection Plan cover theft?
A: Yes, but only with proof of theft (e.g., a police report). The payout is typically replacement cost minus deductible, and the item must be reported within a specified timeframe (often 30–90 days).
Q: What’s the deductible for claims?
A: Deductibles vary by item but are often 10–20% of the item’s value. For example, a $1,000 TV might require a $100–$200 deductible before coverage kicks in.
Q: Can I transfer the Protection Plan to a new owner?
A: No. The plan is non-transferable and tied to the original purchaser’s Walmart account. If you sell or gift the item, the protection expires.
Q: Are there any items that always qualify for full coverage?
A: Rarely. Even high-ticket items like appliances or electronics have exclusions (e.g., pre-existing damage, lack of maintenance). Walmart’s terms prioritize deniability over full coverage.
Q: How long does a claim take to process?
A: Processing times vary, but most claims take 30–60 days. Complex cases (e.g., theft with police reports) may take longer. Walmart does not offer expedited processing.
Q: What happens if I don’t renew the Protection Plan?
A: Coverage expires automatically. Walmart does not send reminders unless you’ve opted into marketing emails, so it’s easy to lose protection unintentionally.
Q: Is the Protection Plan worth it for used or refurbished items?
A: No. The plan excludes pre-existing conditions, and refurbished items are assumed to have prior damage. Walmart will almost certainly deny claims for used/refurbished purchases.
Q: Can I stack the Protection Plan with manufacturer warranties?
A: Yes, but the plans do not combine coverage. The Protection Plan typically covers accidental damage, while manufacturer warranties cover defects. You’ll need to file separate claims.
