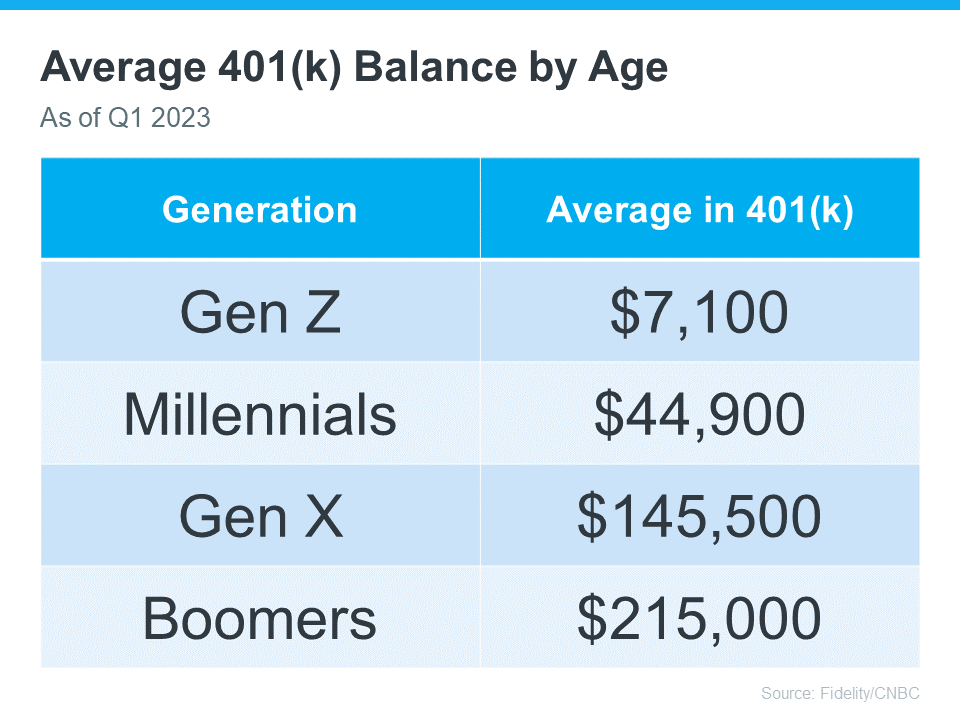
Breaking Down the Numbers
Fidelity’s methodology is straightforward: it aggregates account balances across its 401k platform, then segments them by participant age as of year-end. The results are published in press releases and investor reports, often cited by financial advisors as a rough benchmark. For 2023, the median balance for a 35-year-old was reported around the $60,000 mark, while a 55-year-old’s median hovered near $200,000. These figures align with broader industry trends showing slower growth in younger cohorts due to lower starting salaries and delayed contributions. Yet the data also reveals a silent crisis: the gap between median balances and what’s needed for a secure retirement has widened, particularly for those without high-earning spouses or additional income streams. The numbers become more revealing when adjusted for inflation and contribution limits. A 45-year-old’s median balance in 2010 would buy far less today, even if the nominal value appears higher. Fidelity’s reports don’t account for employer match percentages, loan activity, or hardship withdrawals—factors that can distort the picture of true retirement readiness. What’s clear is that the Fidelity average 401k balance by age functions as a mirror more than a roadmap. It reflects participation rates, market performance, and behavioral patterns, but it doesn’t prescribe action. The challenge lies in interpreting these snapshots without conflating them with personalized financial health.The Verified Baseline
Fidelity’s 2023 data confirms two immutable truths. First, consistent contributions matter more than age alone. A 30-year-old who’s contributed $500/month since turning 22 will outpace a 40-year-old who’s only saved sporadically. Second, employer matches are the single biggest lever for early-career savers. Fidelity’s figures show that participants with access to a 4% match (a common benchmark) see their balances grow ~25% faster than those without. The baseline data also underscores the impact of market cycles: the 2022 downturn erased years of growth for many, particularly those nearing retirement. What’s verifiable—and often overlooked—is the role of account ownership duration. A 50-year-old with a $250,000 balance might have had that account for 25 years, while a 30-year-old with $50,000 could have opened it just five years prior. Time in the market, not just dollars contributed, shapes these medians. Fidelity’s reports also highlight that high-earner participation skews the data upward. A tech executive in Silicon Valley will drag the median for their age group higher than a public-sector worker in the same cohort. The raw numbers, therefore, require context: they’re useful for comparison but poor substitutes for individualized planning.What the Estimates Suggest
Industry estimates suggest that the Fidelity average 401k balance by age understates the savings needed for a comfortable retirement. Financial planners often cite the 4% rule—withdrawing 4% annually from savings—as a guideline, which implies a nest egg of 25x annual expenses at retirement. For someone retiring at 65 with $80,000/year in expenses, that’s $2 million. Yet Fidelity’s median for a 65-year-old is estimated at $250,000, leaving a gap of $1.75 million. This disparity isn’t just about individual savings; it reflects systemic issues like rising healthcare costs, longer lifespans, and stagnant wage growth. Speculative analyses further complicate the picture. Some economists argue that the average 401k balance by age will improve if younger workers adopt auto-escalation features (automatically increasing contributions) or if Congress expands catch-up contributions for older savers. Others caution that market volatility could reset these balances downward. What’s certain is that the medians don’t account for sequence-of-returns risk—the devastation a poor market year early in one’s career can have decades later. The estimates, therefore, should prompt questions rather than dictate actions.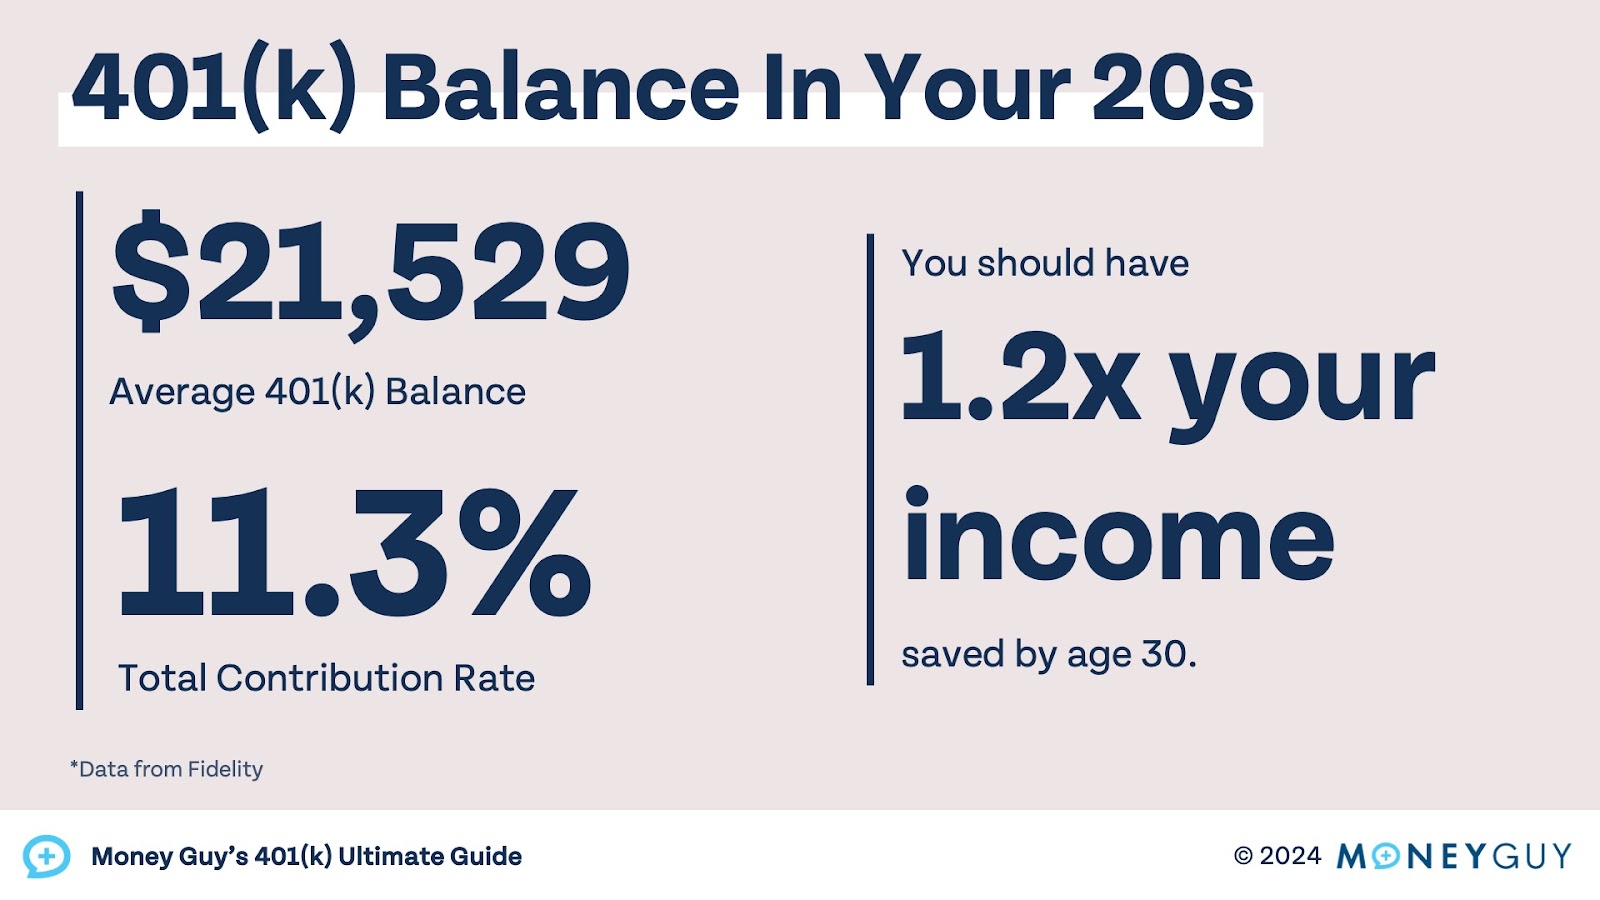
Case Study: A Closer Look
Consider the experience of a 42-year-old marketing manager in Chicago, whose Fidelity 401k balance sits at $180,000—right at the median for their age group. On paper, this appears solid, but a deeper look reveals cracks. They’ve been contributing 10% of their $75,000 salary for eight years, with a 3% employer match. Their account includes a $20,000 loan taken in 2020 to cover medical bills, which they’ve been repaying at $300/month. If they retire at 65 with a $70,000/year lifestyle, their 4% withdrawal rate would yield $5,600/year—far short of their needs. The median balance, in this case, masks the reality of debt and insufficient growth. The case study underscores why Fidelity’s average 401k balance by age is a starting point, not an endpoint. Adjustments like increasing contributions to 15%, paying off the loan faster, or delaying retirement by two years could close the gap. Yet without proactive steps, the median becomes a false reassurance. The table below outlines key factors affecting this scenario:| Factor | Estimated Impact |
|---|---|
| Loan Repayment Timeline | Extending repayment to 2030 reduces balance by ~$15,000 due to missed interest. |
| Contribution Increase to 15% | Adds ~$120,000 by age 65, assuming 7% annual returns. |
| Retirement Age Delay (67 vs. 65) | Increases balance by ~$80,000 through continued contributions and compounding. |
"The median is a statistical artifact, not a personal goal. If your balance aligns with Fidelity’s averages but your expenses or health risks are higher, you’re not ‘on track’—you’re just average." — Certified Financial Planner, Chicago
What This Means Going Forward
The Fidelity average 401k balance by age will continue to evolve, shaped by economic policies, employer trends, and worker behavior. One likely shift is the rise of auto-enrollment with higher default rates, which could lift medians for younger workers. Conversely, inflation and student debt may suppress savings for Gen Z and Millennials, dragging future medians downward. For planners, the key takeaway is that these benchmarks are dynamic, not static. A 30-year-old’s median today may not apply to their 40-year-old self in a decade. The data also highlights the need for personalized adjustments. Someone earning $200,000/year should aim higher than the median, while a single parent on $50,000 may need to prioritize Roth IRAs or side income. Fidelity’s reports should prompt three questions: Where do I stand relative to the median? What’s my unique retirement gap? And what actions can close it? Ignoring the medians risks complacency; fixating on them risks paralysis. The goal isn’t to hit a number but to build a plan that accounts for the numbers’ limitations.
Conclusion
Fidelity’s annual 401k balance disclosures serve a vital function: they demystify retirement savings by providing a real-world reference point. Yet their value lies in how they’re used—not as a target, but as a conversation starter. The average 401k balance by age reveals trends, exposes disparities, and challenges assumptions. For a 25-year-old, it’s a wake-up call; for a 55-year-old, it’s a reality check. The danger isn’t in the data itself but in treating it as a one-size-fits-all solution. Retirement planning is inherently personal, and the medians are just the beginning. The next step is action. For those below the median, the focus should be on increasing contributions, leveraging employer matches, and reducing debt. For those above, the work may involve tax-efficient withdrawals, legacy planning, or phasing into retirement. Either way, the Fidelity average 401k balance by age is a tool, not a verdict. Used wisely, it can illuminate the path forward; ignored, it becomes just another statistic in the noise.Comprehensive FAQs
Q: How often does Fidelity update its average 401k balance by age?
A: Fidelity releases updated median balances annually, typically in January or February, based on year-end data. The reports are published in press releases and investor communications, often accompanied by commentary on trends.
Q: Does Fidelity’s median include Roth 401k contributions?
A: Yes, Fidelity’s median balances include both traditional and Roth 401k contributions, as the data aggregates all account types. However, the reports don’t break out Roth balances separately, so participants must track those independently.
Q: Can I use Fidelity’s averages to project my future balance?
A: While the averages provide a rough benchmark, projecting your future balance requires inputting your specific contribution rate, employer match, investment allocation, and expected returns. Fidelity’s retirement calculators can help, but they’re estimates, not guarantees.
Q: What’s the biggest misconception about these median figures?
A: The most common mistake is assuming the median represents a target rather than a reference point. Many people compare their balance to the median and either panic if they’re below or relax if they’re above, without considering their unique financial situation.
Q: How do employer match percentages affect the median?
A: Employer matches can significantly boost the median for participants who take full advantage. For example, a 3% match on a $60,000 salary adds $1,800/year to the account, accelerating growth. Fidelity’s data shows that participants with access to matches tend to have higher balances across all age groups.
Q: Are there differences in median balances by industry or location?
A: Yes, but Fidelity doesn’t publish breakdowns by industry or geography. However, industry estimates suggest that tech, finance, and healthcare workers tend to have higher median balances due to higher salaries and employer contributions, while public-sector and service-industry workers often lag behind.
Q: What should I do if my balance is below the median for my age?
A: Start by increasing contributions, even by 1-2%, and ensure you’re maximizing employer matches. If possible, delay retirement or explore additional income streams. A financial advisor can help tailor a plan based on your specific goals and risk tolerance.
