The Complete Overview of the Richest Man in the Whole World
The concept of the richest man in the whole world is fluid, a title that shifts with market fluctuations, tax filings, and the occasional billionaire’s sudden ascent or fall. As of recent assessments, the individual currently occupying this position didn’t achieve it through traditional corporate leadership but through a hybrid model of technology, speculation, and financial engineering. Their empire spans multiple industries—technology, renewable energy, private spaceflight—but the core remains a holding company that acts as a black box for global capital. The fortune isn’t just accumulated; it’s optimized, with assets structured across tax havens, private equity vehicles, and jurisdictions where transparency is optional. What makes this figure distinct from historical titans like Rockefeller or Vanderbilt is the speed of wealth generation. The old guard built railroads and oil; this generation builds data monopolies that capture value from user attention, algorithmic trading, and the commodification of personal information. The wealth isn’t just passive; it’s active, reinvested in ventures that further concentrate power. For every publicized acquisition or charity donation, there are a dozen quiet maneuvers—acquisitions of struggling competitors, lobbying for deregulation, or even direct investments in political campaigns that ensure the rules remain tilted in their favor. The title richest man in the whole world isn’t just about dollars; it’s about leverage. The public narrative often reduces this figure to a caricature: the eccentric billionaire with a rocket company or a Twitter empire. But the reality is more insidious. Their wealth is systemic, a product of late-stage capitalism where financialization has outpaced productive investment. The fortune isn’t just personal; it’s a public good turned private asset, where infrastructure, innovation, and even basic services are funneled into private hands. The question of whether this concentration of wealth is justified isn’t just moral—it’s structural. If the systems that produce such extremes aren’t addressed, the title richest man in the whole world will remain less a personal achievement and more a warning sign. The media’s obsession with this individual—whether through profiles, interviews, or tabloid speculation—often obscures the bigger picture. The real story isn’t about one person’s net worth but about the rules that allow it to exist. Tax loopholes, weak antitrust enforcement, and the erosion of labor rights aren’t bugs in the system; they’re features, designed to ensure that wealth compounds while responsibility dilutes. The richest man in the whole world isn’t just a benchmark; they’re a canary in the coal mine of global economics.Historical Background and Evolution
The modern era of the richest man in the whole world began in the late 20th century, when the collapse of traditional industrial monopolies gave way to financialized capitalism. The first true global billionaire in the modern sense emerged not from manufacturing but from information control—first through media (think Rupert Murdoch’s early empire), then through software (Microsoft’s Gates, Oracle’s Ellison), and finally through the attention economy of the internet. Each wave brought a new mechanism for wealth extraction: licensing fees, subscription models, and now, data harvesting. The current holder of the title didn’t invent this model but perfected it, turning platforms into wealth machines that generate revenue with minimal overhead. The evolution from industrial tycoons to digital oligarchs wasn’t linear. The old guard—Rockefeller, Carnegie—built empires on physical assets that required labor, infrastructure, and regulation. The new guard operates in a weightless economy, where the primary asset isn’t steel or oil but code and algorithms. This shift has two critical implications: first, the barrier to entry is lower (anyone with a laptop can start a tech company), but the moat around wealth is higher—once a platform achieves scale, competition becomes nearly impossible. Second, the wealth isn’t just personal; it’s embedded in the infrastructure of daily life. The richest man in the whole world today doesn’t just own a company; they own the pipes through which modern society communicates, shops, and entertains itself. The financial crisis of 2008 was a turning point. While most economies staggered, the ultra-wealthy didn’t just survive—they thrived. The reason? Their assets were already decoupled from traditional markets. Cash, real estate, and private equity performed while public markets crashed, and the subsequent bailouts (which saved banks but not Main Street) further tilted the playing field. The post-crisis era saw the rise of alternative wealth, where fortunes are made not just in stocks but in private markets, hedge funds, and speculative bets that ordinary investors can’t access. The richest man in the whole world today operates in this parallel universe, where the rules of engagement are written by—and for—the ultra-wealthy. The cultural shift is equally significant. Where once the wealthy were expected to display their wealth through conspicuous consumption (mansions, yachts, art), today’s elite prefer conspicuous influence. The goal isn’t just to be rich; it’s to reshape the systems that define wealth. This explains the shift from philanthropy (which is still performed) to policy advocacy, where donations to think tanks, lobbying efforts, and even "charitable" foundations serve to lock in regulatory advantages. The richest man in the whole world isn’t just a beneficiary of capitalism; they’re its architect.Core Mechanisms: How It Works
The fortune of the richest man in the whole world isn’t built on a single industry but on a diversified, often opaque, network of assets. At its core, the mechanism is simple: control the flow of capital. This is achieved through three primary levers. First, platform monopolies—companies that dominate a market segment (social media, e-commerce, cloud computing) and extract rent from users and advertisers. Second, financial engineering—structuring assets across jurisdictions to minimize taxes and maximize liquidity. Third, strategic investments—placing bets on emerging sectors (AI, biotech, space) before they become mainstream, ensuring a first-mover advantage. The platform monopoly is the most visible but not the most lucrative. The real money lies in secondary assets: private equity stakes in struggling companies, real estate holdings in prime global locations, and illiquid investments that ordinary markets can’t touch. For every publicized acquisition (like a high-profile tech buyout), there are dozens of quiet maneuvers—buying distressed assets, acquiring minority stakes in startups, or even shorting markets to profit from volatility. The richest man in the whole world doesn’t just play the stock market; they reshape it. Their wealth isn’t static; it’s a living organism, constantly evolving to exploit new opportunities. Tax optimization is where the system truly bends. The use of offshore entities, trusts, and shell companies isn’t illegal in many jurisdictions—it’s standard practice. The fortune isn’t just hidden; it’s structurally protected. For every dollar reported on a tax return, there are likely multiple dollars parked in accounts where disclosure isn’t required. The richest man in the whole world doesn’t pay taxes at the same rate as a middle-class earner; they pay at the effective rate of a multinational corporation, even if they’re not running one. This isn’t just about loopholes; it’s about rewriting the rules so that the ultra-wealthy operate in a parallel fiscal system. The final piece is influence. Wealth begets power, but power also begets more wealth. The richest man in the whole world doesn’t just donate to political campaigns; they fund entire ecosystems—think tanks that shape policy, media outlets that control narrative, and even educational institutions that produce the next generation of elites. The goal isn’t just to win elections; it’s to ensure that the economic landscape remains tilted in their favor. This is why the title isn’t just about money; it’s about control over the mechanisms that generate money.Key Benefits and Crucial Impact
The concentration of wealth at the top isn’t just an economic phenomenon—it’s a geopolitical one. The richest man in the whole world doesn’t just influence markets; they shape global priorities. When their company invests in renewable energy, it’s not just a business decision; it’s a signal to governments and investors about where the future lies. When they acquire a media outlet, they’re not just expanding their empire; they’re reshaping public discourse. The benefits of this concentration are clear: innovation accelerates, infrastructure improves, and capital flows to where it’s most needed—at least, in theory. The reality is more complicated. The impact isn’t just positive. The richest man in the whole world operates in a feedback loop where wealth begets more wealth, while the rest of society struggles with stagnant wages and eroding public services. The question isn’t whether this individual deserves their fortune; it’s whether the system that produced it is sustainable. History shows that when wealth becomes this concentrated, it doesn’t just create winners—it creates losers, too. The middle class shrinks, inequality deepens, and the social contract begins to unravel. The richest man in the whole world isn’t just a product of this system; they’re a catalyst for its extremes."Extreme wealth isn’t just a symptom of capitalism—it’s a correction of its failures. When markets don’t reward hard work, they reward control. And when control becomes the primary metric of success, society pays the price." — Economist and inequality researcher, 2023The benefits of this concentration are often framed in terms of trickle-down economics: if the rich get richer, eventually, the rest will benefit. But the evidence suggests the opposite. The richest man in the whole world doesn’t just hoard wealth; they hoard opportunity. The jobs they create are often low-wage, the innovations they fund are frequently locked behind paywalls, and the influence they wield ensures that the rules remain stacked in their favor. The system isn’t broken; it’s designed to produce outcomes like this.
Major Advantages
- Asset diversification across jurisdictions—minimizing tax exposure while maximizing liquidity in global markets.
- Control over key infrastructure—from digital platforms to physical assets like real estate and energy.
- Access to exclusive financial instruments—private equity, hedge funds, and speculative bets unavailable to retail investors.
- Political influence that shapes policy—from tax reform to antitrust enforcement—before it’s even debated.
- The ability to rewrite cultural narratives—through media ownership, philanthropy, and public relations—to frame wealth as meritocratic.
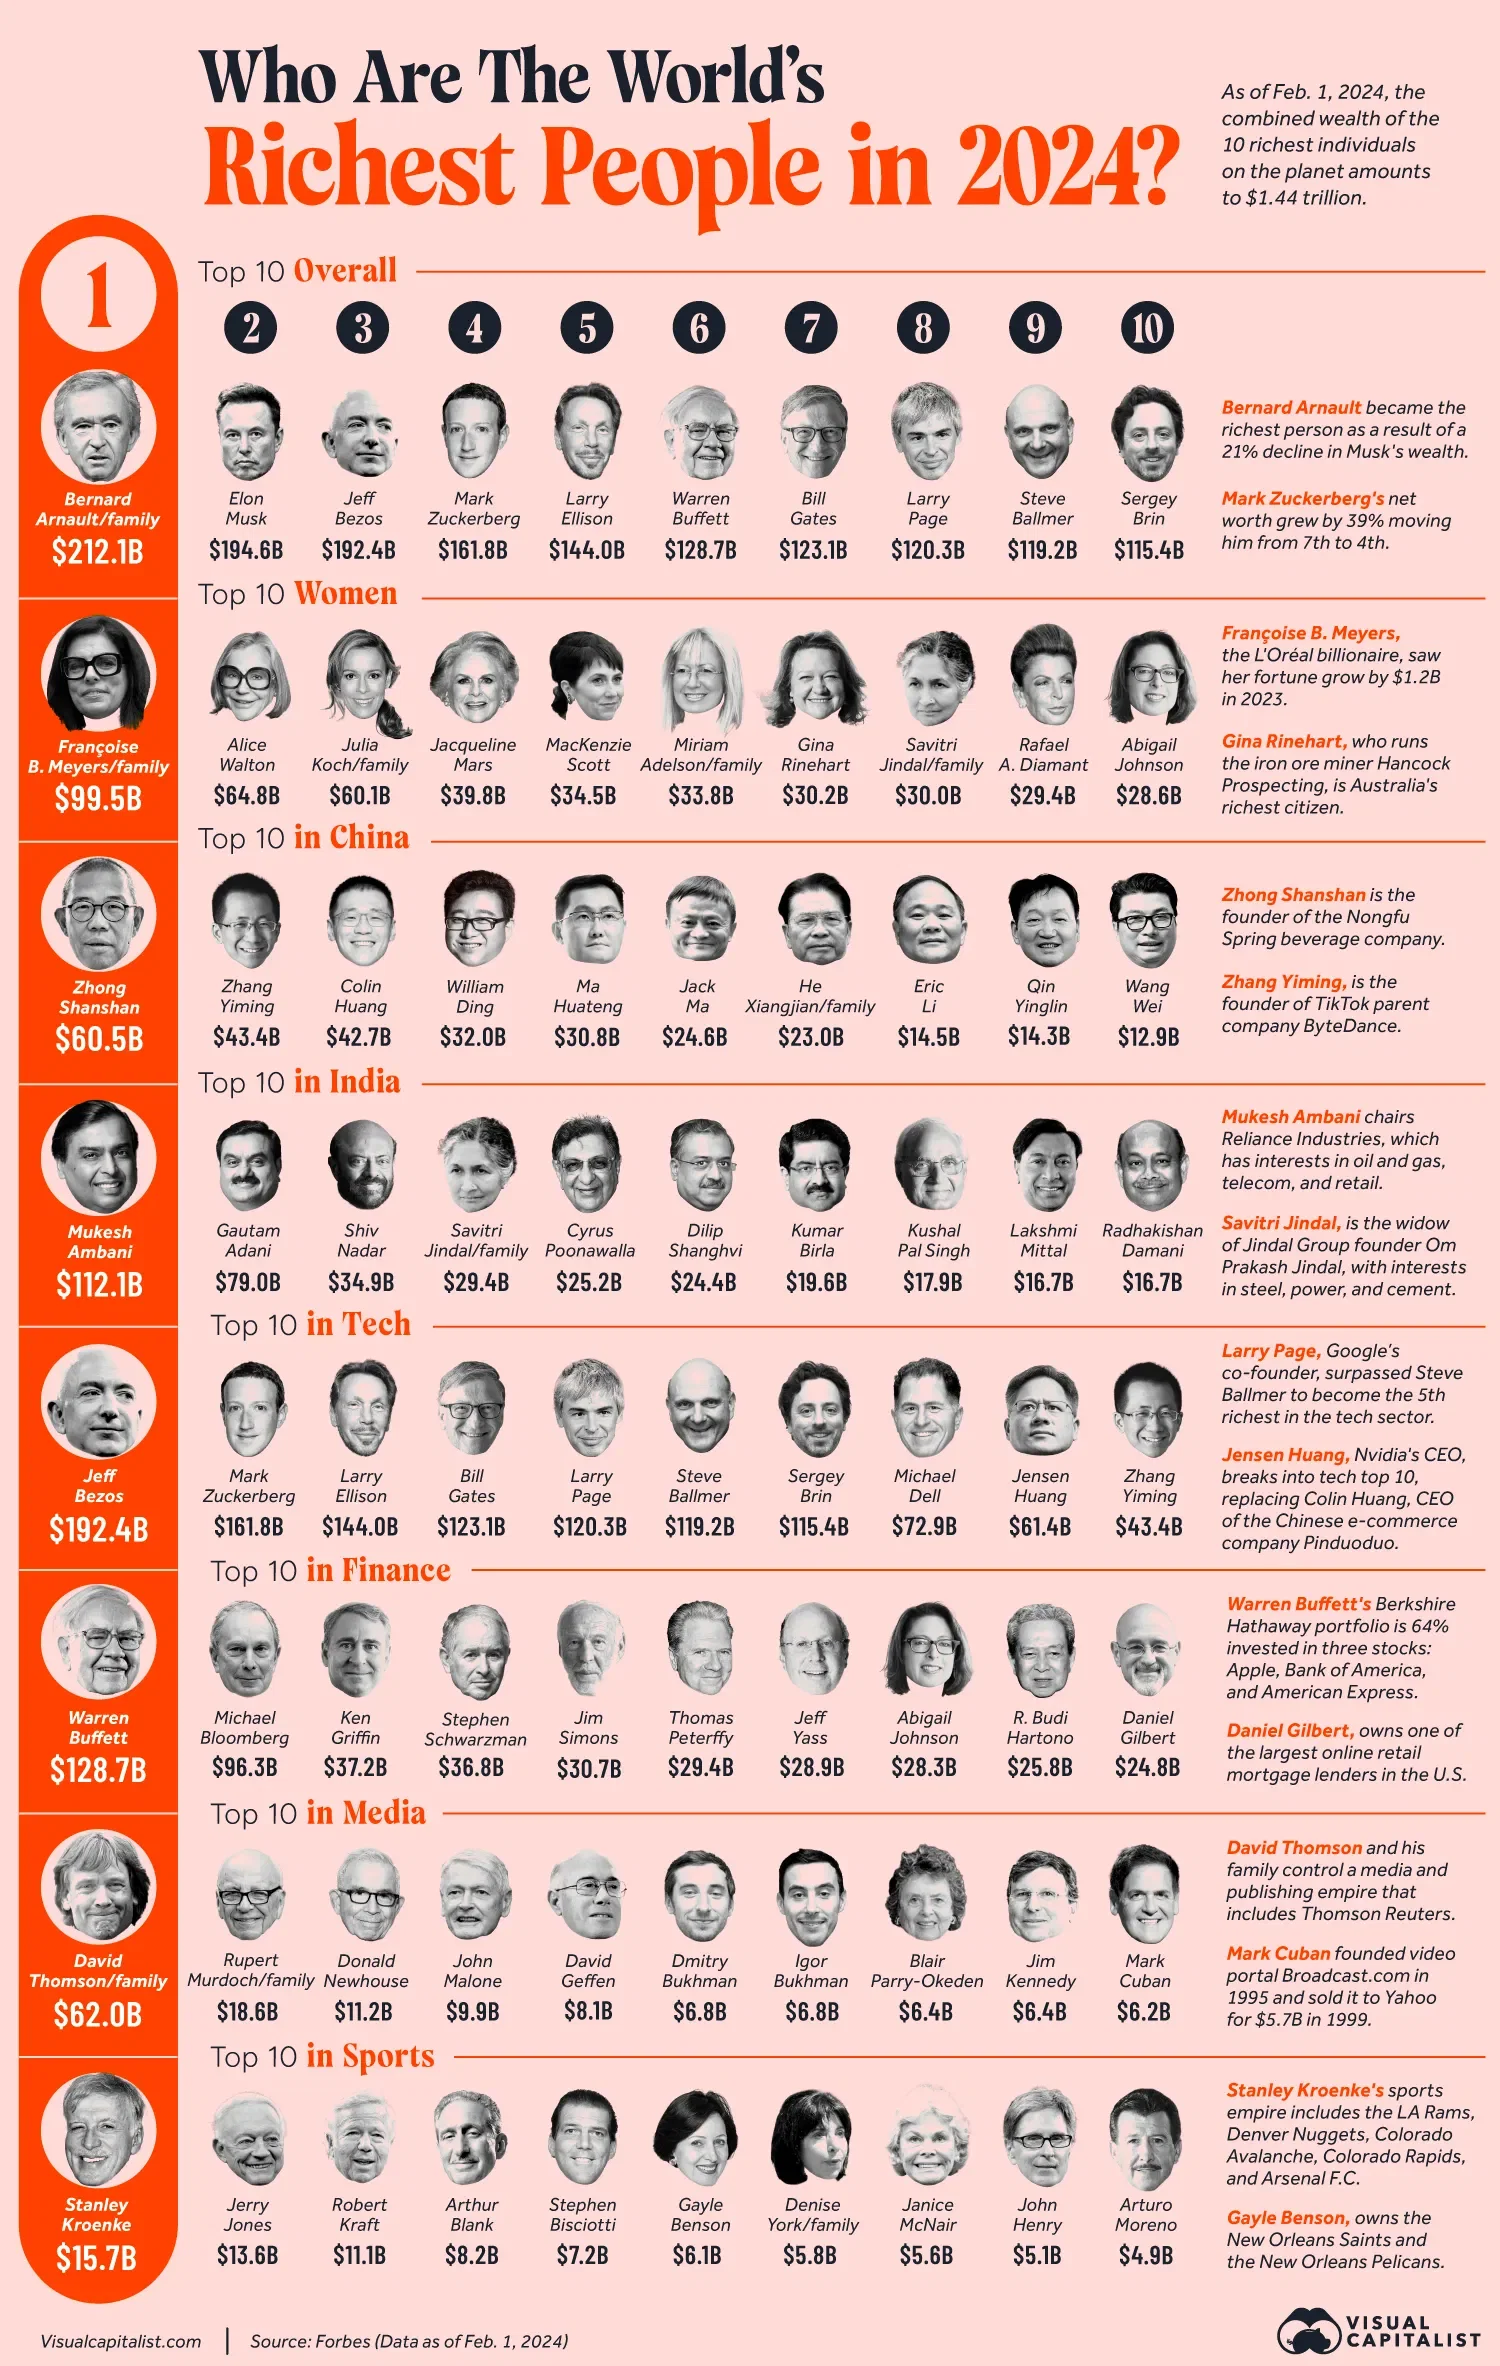
Comparative Analysis
| Current Holder of Title | Historical Predecessors (Rockefeller, Gates, etc.) |
|---|---|
| Wealth derived from digital platforms and financial engineering | Wealth derived from industrial monopolies and manufacturing |
| Assets structured across tax havens and private markets | Assets tied to physical infrastructure and public markets |
| Influence exerted through policy advocacy and media control | Influence exerted through direct political donations and lobbying |
| Wealth compounds through speculation and algorithmic trading | Wealth compounds through dividends and asset appreciation |
| Public perception shaped by tech culture and philanthropic branding | Public perception shaped by industrial legacy and philanthropic foundations |
Future Trends and Innovations
The next phase of wealth accumulation won’t be driven by traditional business models but by emerging technologies and financial innovations. The richest man in the whole world today is already positioning assets in AI, biotech, and space exploration—sectors where the barriers to entry are high, but the potential returns are exponential. The trend isn’t just about owning companies; it’s about owning the future. Whether it’s investing in brain-computer interfaces, carbon credits, or private space stations, the goal is to ensure that the next wave of economic activity is controlled by those who can shape its rules. The bigger question is whether this concentration of wealth will persist or fracture. The systems that sustain the richest man in the whole world today—tax loopholes, weak antitrust enforcement, and financial secrecy—are under increasing scrutiny. Regulatory crackdowns, public backlash, and even technological disruptions (like decentralized finance) could force a reckoning. But history suggests that wealth finds a way. The richest man in the whole world tomorrow won’t look the same as today’s; they’ll adapt, evolve, and reinvent the mechanisms of extraction. The real question isn’t whether someone will still hold this title in a decade—it’s whether the system that allows it will still stand.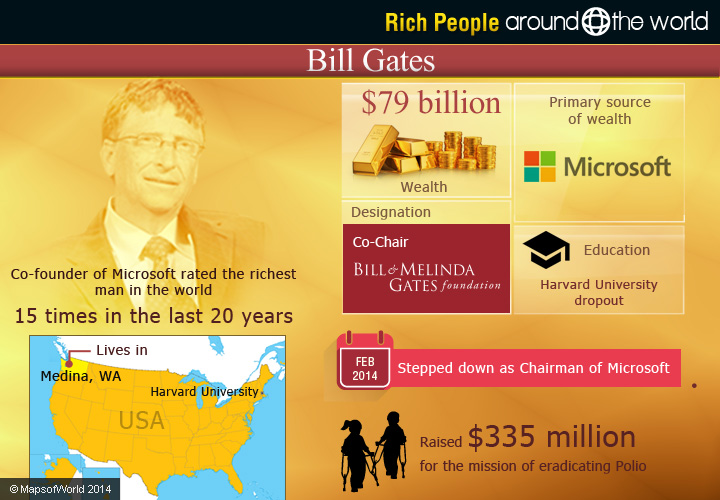
Conclusion
The title richest man in the whole world is more than a statistical curiosity—it’s a diagnostic tool for understanding the health of global capitalism. The individual who holds it today isn’t just a product of their own ingenuity; they’re a product of the system. The wealth they’ve accumulated isn’t just personal; it’s structural, a result of policies, technologies, and cultural narratives that have been engineered to favor the ultra-wealthy. The debate over whether this concentration of wealth is fair misses the point. The real issue is whether the system that produces it is sustainable. The richest man in the whole world isn’t the problem—the system that creates them is. Until that system is reformed, the title will continue to shift, but the underlying dynamics will remain the same. The question isn’t how to dethrone the current holder; it’s how to redesign the rules so that extreme wealth isn’t the default outcome of capitalism. That, more than any fortune, is the true measure of progress.Comprehensive FAQs
Q: How does the richest man in the whole world maintain their lead over other billionaires?
The lead isn’t maintained through traditional business competition but through financial engineering, tax optimization, and strategic influence. Unlike industrialists who relied on physical assets, today’s wealthiest individuals operate in illiquid markets, private equity, and speculative bets that ordinary investors can’t access. Additionally, their control over digital platforms and media allows them to shape narratives that frame their success as inevitable, while also lobbying for policies that benefit their asset classes.
Q: Are there any legal or ethical limits to how much wealth one person can accumulate?
Legally, no—there are no hard caps on personal wealth. However, tax laws, antitrust regulations, and financial reporting requirements create soft limits that the ultra-wealthy navigate through offshore structures, shell companies, and lobbying. Ethically, the debate centers on whether extreme wealth concentration undermines democratic principles, exacerbates inequality, and erodes social mobility. Many economists argue that when wealth reaches a certain threshold, it distorts markets and politics in ways that harm broader society.
Q: How does the richest man in the whole world influence global policy?
Influence isn’t bought outright but embedded in the system. This includes:
- Funding think tanks and policy groups that shape legislation before it’s debated.
- Donating to political campaigns and super PACs to ensure favorable regulations.
- Acquiring media outlets to control narrative around economic issues.
- Using charitable foundations to lobby for causes that align with their business interests.
- Hiring former regulators and politicians as advisors to exploit insider knowledge.
Q: What role does technology play in their wealth accumulation?
Technology isn’t just a tool—it’s the primary mechanism of wealth extraction. The richest man in the whole world today controls platforms that monetize attention, data, and transactions, creating network effects that make competition nearly impossible. Additionally, AI, algorithmic trading, and blockchain allow for high-frequency speculation that ordinary investors can’t replicate. The result is a digital feudalism, where a few entities control the infrastructure of the modern economy.
Q: How do they protect their wealth from market downturns or political risks?
Protection comes from diversification across asset classes and jurisdictions. This includes:
- Parking cash in tax havens and offshore accounts where disclosure isn’t required.
- Investing in illiquid assets (private equity, real estate, art) that don’t fluctuate with public markets.
- Using hedge funds and derivatives to bet against market declines.
- Lobbying for bailout protections in case of financial crises.
- Building private infrastructure (data centers, energy projects) that are immune to public market volatility.
Q: Is there a risk that their wealth could be seized or redistributed?
The risk is theoretical but growing. While no government has successfully seized the wealth of the richest individuals in modern history, public pressure, regulatory crackdowns, and even technological disruptions (like decentralized finance) could force changes. However, the ultra-wealthy have decades of legal and financial maneuvering to protect their assets. The more likely scenario is incremental reform—higher taxes on capital gains, stricter antitrust enforcement, or transparency laws—rather than outright confiscation.
Q: How does their wealth compare to national economies?
The net worth of the richest man in the whole world today exceeds the GDP of many small nations. For context, their fortune is larger than the economies of Switzerland, Sweden, or South Africa. This concentration means they have more financial power than entire governments, allowing them to outspend states on lobbying, influence, and even military-grade technology (e.g., private space programs). The comparison underscores how wealth has become a form of soft power, rivaling traditional state sovereignty.
Q: What happens if they lose their title to someone else?
The title is symbolic but not structural. Even if another individual surpasses them in net worth, the mechanisms of wealth accumulation would remain the same. The real question isn’t who holds the title but whether the system that produces such extremes is sustainable. If the next holder is equally embedded in the same financial and political structures, the dynamics of inequality would persist—regardless of who’s at the top.
