
The Short Answers
- A country’s net worth GDP isn’t a standard metric, but it combines GDP with total assets minus liabilities to show true wealth.
- Norway’s sovereign wealth fund makes its country net worth GDP far higher than GDP alone suggests, despite volatile oil revenues.
- High GDP doesn’t guarantee high net worth—Japan’s GDP ranks third globally, but its debt-to-GDP ratio exceeds 260%.
- Measuring national net worth requires data on public debt, private wealth, and non-financial assets like real estate.
Deep Dive: The Full Picture
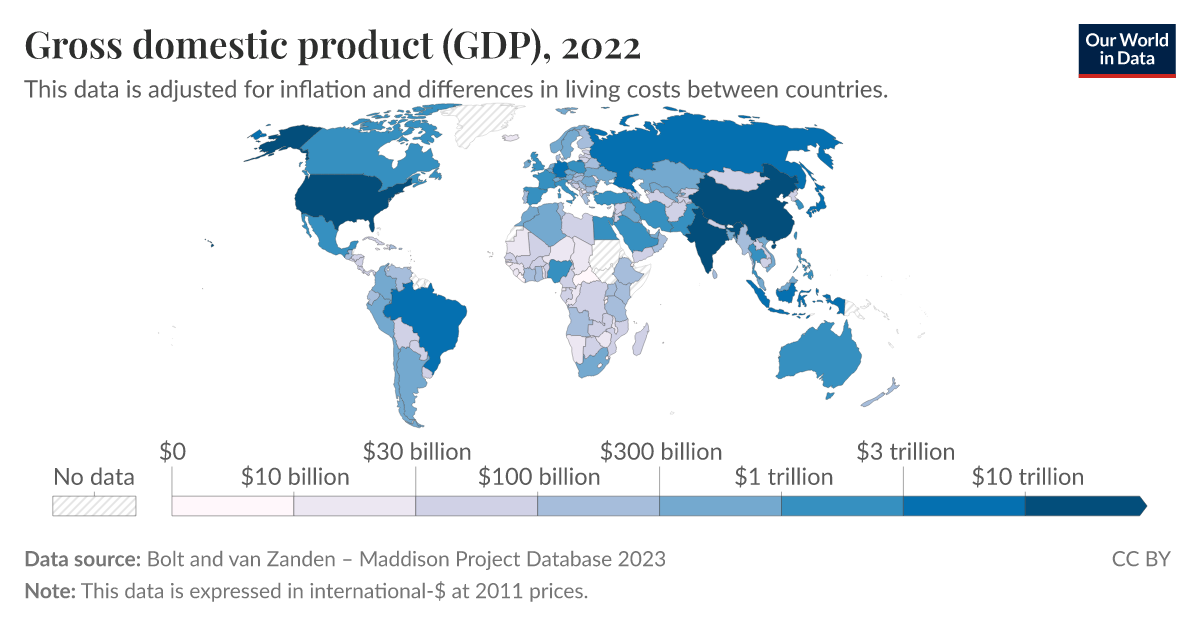
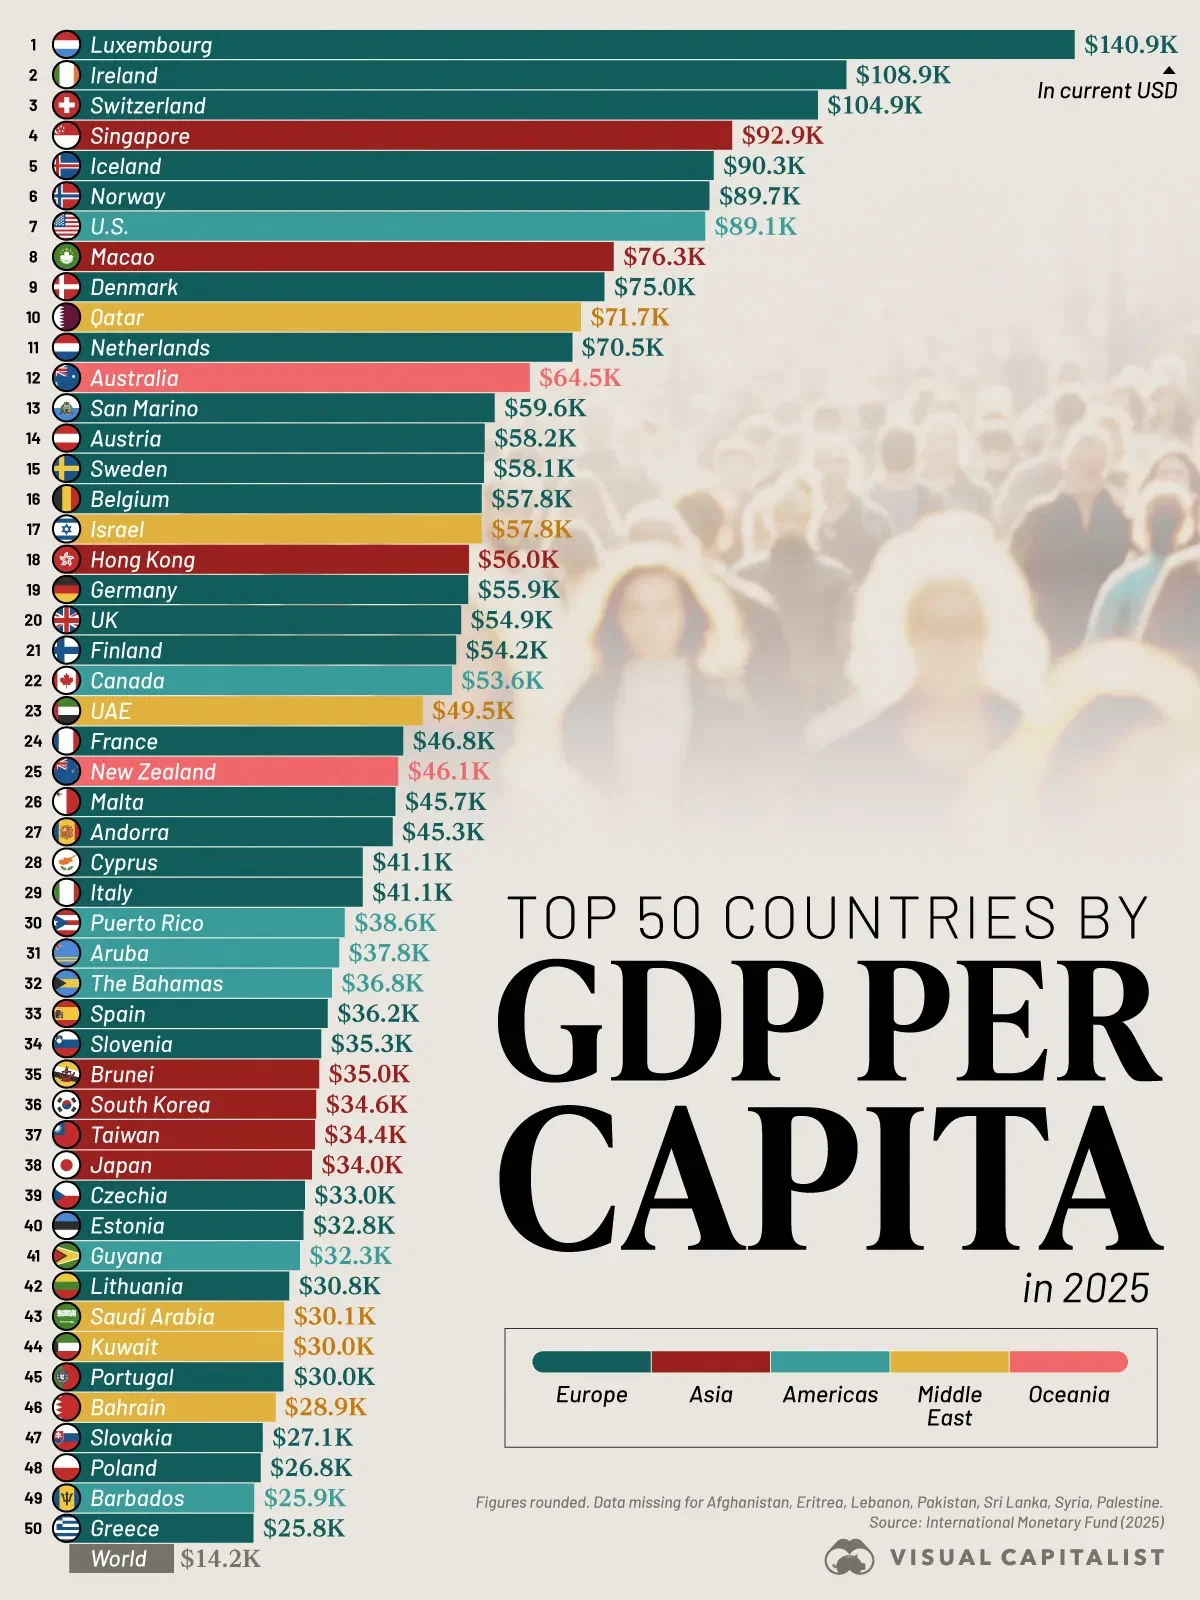
GDP remains the default lens for evaluating national economies, but it’s a snapshot, not a balance sheet. A country’s net worth GDP—if calculated—would include everything from the value of its roads and universities to the liabilities of its pension systems. The IMF’s World Economic Outlook tracks GDP growth, yet it quietly acknowledges that wealth inequality between nations is widening faster than income inequality. For example, the U.S. GDP per capita is $76,000, but its median household net worth sits at $188,000—meaning most Americans’ personal wealth doesn’t align with national output. Conversely, Qatar’s GDP per capita is $70,000, but its sovereign wealth fund (worth ~$400 billion) dwarfs the GDP of many nations, illustrating how country net worth GDP can distort traditional rankings. The problem isn’t just academic. When the World Bank assesses a nation’s ability to fund development, it relies on GDP projections. Yet GDP ignores the opportunity cost of depleted resources—like Norway’s oil fields—or the hidden wealth in undervalued assets, such as Brazil’s Amazon rainforest, which generates ecological services worth billions annually. Economists like Thomas Piketty have argued that national wealth inequality is the defining challenge of the 21st century, yet no global institution tracks it systematically. The closest proxies—like the Credit Suisse Global Wealth Report—focus on private wealth, not the interplay between public and private balance sheets.The Context You Need
The concept of country net worth GDP emerged from critiques of GDP’s limitations. In the 1990s, economists like William Nordhaus and Joseph Stiglitz pushed for broader measures of well-being, but policymakers resisted. Today, the Sovereign Wealth Fund Institute tracks funds like Singapore’s Temasek, which hold assets worth trillions—wealth that GDP cannot quantify. These funds act as national savings accounts, smoothing out economic cycles. Without them, a country’s GDP volatility would be far more extreme. For instance, Saudi Arabia’s GDP dropped by 4% in 2020 due to oil price shocks, yet its Public Investment Fund (worth ~$620 billion) cushioned the blow. The absence of a country net worth GDP metric also obscures how debt burdens differ. Italy’s GDP is €1.9 trillion, but its national debt is €2.8 trillion—meaning its net worth is negative. Meanwhile, Switzerland’s GDP is €700 billion, but its net international investment position (a proxy for net worth) is positive, thanks to strong banks and foreign assets. This explains why Switzerland can afford lower taxes despite a smaller economy: its accumulated wealth supports public services without relying on annual GDP growth.The Mechanics
Calculating country net worth GDP would require aggregating: 1. Public sector net worth: Government assets (land, infrastructure) minus liabilities (debt, pension obligations). 2. Private sector net worth: Household and corporate wealth, including real estate and financial assets. 3. Natural capital: The value of forests, water reserves, and mineral deposits (often omitted from GDP). 4. Foreign assets and liabilities: Claims on other countries (e.g., U.S. Treasury bonds held abroad) versus debts owed. The World Inequality Database attempts this, but its data is patchy. For example, Russia’s GDP is $1.7 trillion, but its net worth is inflated by state-owned energy assets (like Rosneft) and deflated by corruption-linked capital flight. Meanwhile, the Netherlands’ GDP is €900 billion, but its net worth is boosted by offshore financial hubs like Rotterdam, which generate wealth beyond domestic borders. The challenge lies in valuation. How do you assign a monetary value to a country’s social capital—its education system, healthcare infrastructure, or cultural heritage? The OECD’s Better Life Index tries, but it’s not integrated into financial models. Until then, country net worth GDP remains a theoretical tool, not a standardized metric.Details That Change the Picture
The most glaring discrepancy appears in resource-rich nations. Australia’s GDP is $1.6 trillion, but its net worth is higher due to vast mineral reserves and agricultural land. Yet GDP growth doesn’t always translate to wealth accumulation—witness Venezuela, which sits on the world’s largest oil reserves but has a GDP per capita of just $5,000 due to mismanagement. The country net worth GDP framework would reveal that Venezuela’s liabilities (corruption, debt defaults) far exceed its assets, even with oil. Another distortion: tax havens. Luxembourg’s GDP is €70 billion, but its net worth is inflated by the €3 trillion managed in its financial sector—wealth that belongs to foreign investors. If country net worth GDP were adjusted for such flows, Luxembourg’s true economic contribution would look vastly different. Similarly, Switzerland’s GDP is €700 billion, but its net worth is bolstered by private banking assets worth over €7 trillion—wealth that circulates globally but isn’t reflected in Swiss output."GDP measures the flow of money; net worth measures the stock of assets. One tells you how fast you’re running; the other tells you how much fuel you have left." — Nobel laureate Joseph Stiglitz, 2019
| Country | GDP (Nominal, 2023) | Estimated Net Worth (Proxy) | Key Driver |
|---|---|---|---|
| Norway | $450 billion | $1.4 trillion (sovereign wealth fund) | Oil reserves + fiscal discipline |
| United States | $28 trillion | $140 trillion (private wealth + debt) | Household assets vs. national debt |
| Japan | $4.2 trillion | $12 trillion (negative net worth due to debt) | Public debt > GDP |
| Switzerland | $700 billion | $8 trillion (private banking + real estate) | Financial services + neutral assets |
Conclusion
The obsession with GDP as a measure of national success is a relic of mid-20th-century economics. A country net worth GDP framework would force a reckoning with how wealth is distributed—not just produced. It would expose the fiction that high GDP equals prosperity when debt, inequality, or resource depletion undermine long-term stability. For emerging markets, this matters most: a nation with high GDP but low net worth is vulnerable to shocks, as seen in Argentina’s repeated defaults. The solution isn’t to abandon GDP, but to complement it. The European Central Bank’s Balance Sheet of the Euro Area already tracks net worth for households and corporations—why not extend this to nations? Until then, the country net worth GDP remains an untapped lens, one that could redefine how we assess global power. The question isn’t whether it should be measured, but why it hasn’t been sooner.Comprehensive FAQs
Q: Is "country net worth GDP" an official economic metric?
A: No. While GDP is standardized by the IMF and World Bank, country net worth GDP is a conceptual framework used in academic and policy discussions. The closest official measures are the IMF’s Government Finance Statistics and the OECD’s Wealth Accounts, but neither provides a consolidated "net worth GDP" figure.
Q: Which country has the highest net worth relative to GDP?
A: Norway stands out due to its sovereign wealth fund (worth over $1.4 trillion against a GDP of ~$450 billion). Other candidates include Singapore (government assets exceed GDP) and Switzerland (private wealth dwarfs public output). However, exact comparisons are difficult due to data gaps.
Q: How does national debt affect a country’s net worth?
A: National debt is a liability that directly reduces net worth. Japan’s debt-to-GDP ratio of ~260% means its net worth is negative—its assets (like land and infrastructure) are outweighed by its obligations. Conversely, countries like Estonia have low debt relative to GDP, boosting their net worth.
Q: Can a country have high GDP but low net worth?
A: Yes. South Africa has a GDP of ~$400 billion but faces negative net worth due to high public debt and underperforming state-owned enterprises. Similarly, Italy’s GDP is €1.9 trillion, but its debt (~€2.8 trillion) erodes its net position.
Q: Are there any initiatives to standardize net worth measurements?
A: The System of Environmental-Economic Accounting (SEEA) by the UN aims to integrate natural capital into national accounts, and the OECD’s Wealth Accounts track household and corporate wealth. However, no global body yet publishes a country net worth GDP equivalent. The World Inequality Database is the closest proxy.
Q: How does private wealth factor into national net worth?
A: Private wealth—household and corporate assets—is critical. In the U.S., median net worth ($188,000) exceeds GDP per capita ($76,000), showing that personal assets often outstrip national output. In contrast, India’s median net worth (~$5,000) lags far behind its GDP per capita (~$2,400), highlighting wealth concentration.
Q: Would adopting a net worth GDP metric change economic policy?
A: Absolutely. Policies like debt ceilings, pension reforms, and resource management would shift focus from short-term GDP growth to sustainable asset accumulation. For example, a country net worth GDP approach might prioritize infrastructure investment over consumption-driven growth, as seen in Germany’s emphasis on industrial assets.
Q: Are there risks to calculating net worth for entire nations?
A: Yes. Valuation challenges (e.g., assigning a price to a country’s education system) and political sensitivities (e.g., exposing debt or inequality) complicate adoption. Additionally, capital flight and offshore wealth distort net worth figures, making comparisons between nations difficult. The IMF has warned that over-reliance on net worth metrics could lead to misplaced confidence in asset-rich but debt-laden economies.
