The Complete Overview of net present worth MARR
The net present worth MARR framework is a hybrid valuation tool that integrates time-value-of-money principles with investor-specific risk appetites. Unlike static NPV, which relies on a single discount rate, this approach requires stakeholders to define their minimum attractive rate of return (MARR)—the floor below which an investment fails to meet strategic objectives. The result is a dynamic metric that evolves with market conditions, personal financial goals, and even psychological biases. For example, a retiree with a net present worth MARR of 4% might reject a 5% corporate bond, while a growth-stage VC firm with a 20% hurdle would dismiss the same asset outright. The flexibility isn’t a flaw; it’s the feature that makes the metric adaptable to everything from corporate M&A to personal retirement planning. What distinguishes net present worth MARR from traditional discounted cash flow (DCF) is its emphasis on relative rather than absolute returns. A project with a $10 million NPV might still be rejected if it fails to clear the net present worth MARR benchmark—say, 15%—set by the decision-maker. This isn’t about nitpicking margins; it’s about aligning investments with overarching financial philosophy. Take the case of a real estate developer evaluating a mixed-use property. The raw NPV might suggest profitability, but when discounted at the developer’s net present worth MARR (which could be 18% given their capital constraints), the true economic viability becomes clear. The metric doesn’t replace judgment; it sharpens it.Historical Background and Evolution
The roots of net present worth MARR trace back to military logistics in the 1940s, where the U.S. Army used cost-benefit analysis to justify infrastructure spending during World War II. The concept of a minimum acceptable rate of return emerged as a way to prioritize projects amid scarce resources. By the 1960s, corporate finance adopted these principles, though initially as a secondary check rather than a primary decision tool. The shift toward net present worth MARR gained traction in the 1990s as firms realized that static discount rates couldn’t account for the volatility of global markets. The dot-com bubble’s collapse accelerated this trend, as investors who relied on single-rate NPV models suffered catastrophic misallocations. Today, the net present worth MARR methodology is embedded in frameworks like real options valuation and stochastic discounting, where the MARR isn’t fixed but adjusted dynamically based on scenario analysis. Private equity firms, for instance, might set a net present worth MARR of 25% for early-stage ventures but drop it to 12% for mature assets. This adaptability reflects a broader evolution in finance: from deterministic models to probabilistic ones. The metric’s modern form also owes much to behavioral economics, as practitioners now factor in cognitive biases—like overconfidence or loss aversion—that can distort traditional NPV calculations. In short, net present worth MARR isn’t just a tool; it’s a response to the limitations of older valuation paradigms.Core Mechanisms: How It Works
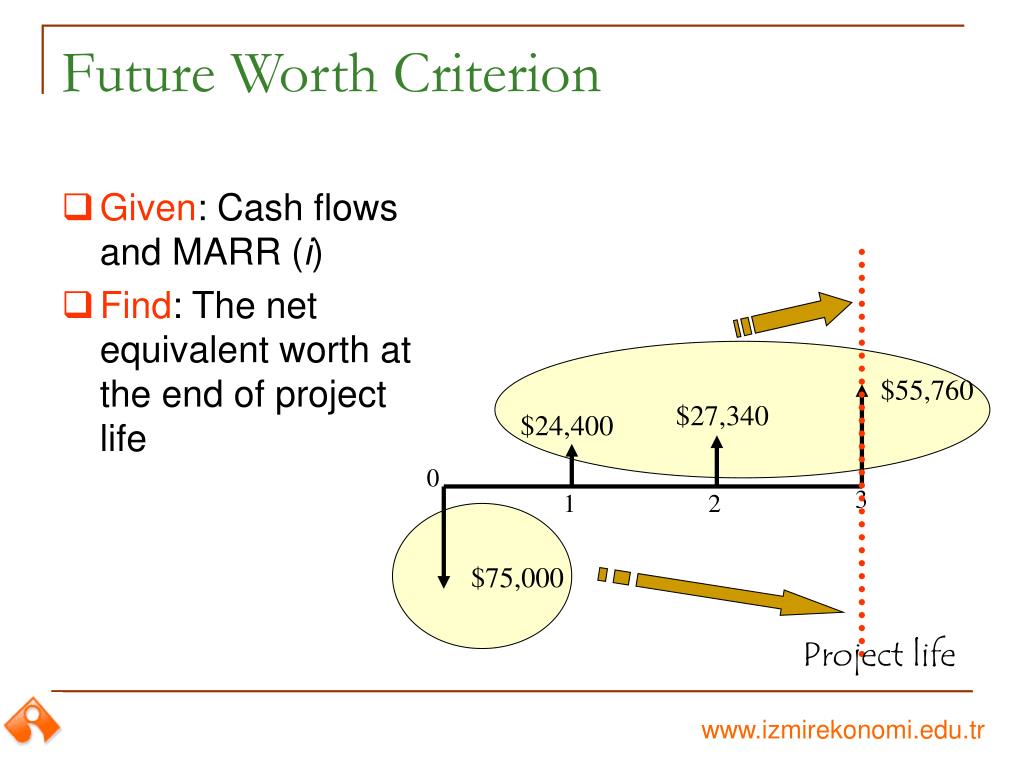
At its core, net present worth MARR operates by discounting future cash flows to present value using the investor’s minimum attractive rate of return as the discount rate. The formula is straightforward: NPW = Σ [CFₜ / (1 + MARR)ᵗ] – Initial Investment Here, CFₜ represents cash flow at time t, and MARR is the hurdle rate. If the result is positive, the investment meets or exceeds the net present worth MARR threshold; if negative, it’s rejected. The critical difference from NPV lies in the MARR’s subjectivity. A pension fund might set its net present worth MARR at 5%, while a hedge fund could demand 20%. This customization ensures the metric aligns with the decision-maker’s risk profile. The real sophistication of net present worth MARR lies in its ability to incorporate qualitative factors. For example, a family office might adjust its net present worth MARR downward for a philanthropic project, even if the financial returns are modest. Conversely, a venture capitalist might inflate the MARR for a high-risk startup to account for the likelihood of failure. The metric also allows for sensitivity analysis, where the MARR is varied to test how changes in risk appetite affect investment viability. This isn’t just number-crunching; it’s a stress test for financial discipline.Key Benefits and Crucial Impact
The adoption of net present worth MARR isn’t just a technical upgrade—it’s a cultural shift in how institutions approach capital allocation. Traditional NPV analysis treats all investments as equal, but net present worth MARR forces a hierarchy based on strategic priorities. This is why private equity firms now use it to screen deals: a $1 billion acquisition might have a positive NPV, but if it fails to clear the firm’s net present worth MARR (often 20%+), it’s a non-starter. The metric’s precision reduces the "surprise factor" in financial outcomes, making it a favorite among fiduciaries and risk-averse investors. What’s often overlooked is how net present worth MARR bridges the gap between finance and psychology. A high MARR isn’t just about returns; it’s a reflection of an investor’s tolerance for uncertainty. A retiree with a net present worth MARR of 3% might reject a 4% bond if it conflicts with their liquidity needs, while a tech entrepreneur with a 30% hurdle will only pursue ventures that promise outsized upside. The metric doesn’t eliminate emotion from investing; it channels it into structured decision-making."NPV tells you if a deal is profitable. Net present worth MARR tells you if it’s worth your time. The difference is the gap between accounting and strategy." — James Tobin, former Yale economist (paraphrased)
Major Advantages
- Risk alignment: The MARR acts as a dynamic hurdle that evolves with market conditions, ensuring investments match the investor’s risk tolerance.
- Strategic filtering: Projects with marginal NPV but subpar net present worth MARR are systematically excluded, reducing portfolio dilution.
- Behavioral guardrails: By forcing explicit hurdle rates, the metric mitigates overconfidence and emotional decision-making.
- Scenario adaptability: The MARR can be adjusted for different economic environments (e.g., higher in recessions, lower in bull markets).
- Transparency: Unlike black-box models, net present worth MARR calculations are auditable and explainable to stakeholders.
- Long-term focus: The discounting process inherently penalizes short-termism, rewarding investments with sustained value creation.
Comparative Analysis
| Net Present Value (NPV) | Net Present Worth MARR |
|---|---|
| Uses a single, often arbitrary discount rate (e.g., WACC). | Employs a minimum attractive rate of return (MARR) tailored to the investor’s goals. |
| Static; doesn’t account for changing risk appetites. | Dynamic; MARR can be adjusted based on market conditions or personal circumstances. |
| May approve low-return, high-risk projects if NPV is positive. | Rejects projects below the net present worth MARR threshold, even if NPV is positive. |
| Widely used but prone to misapplication (e.g., ignoring opportunity cost). | Designed to address NPV’s limitations by integrating qualitative factors. |
Future Trends and Innovations
The next frontier for net present worth MARR lies in its integration with machine learning and alternative data. Firms are now using predictive models to dynamically adjust MARR thresholds based on real-time market signals—such as geopolitical risk or sector-specific volatility. For example, a sovereign wealth fund might automatically raise its net present worth MARR for energy assets during a supply crisis, then lower it as conditions stabilize. This "living MARR" approach is still in its infancy but could redefine how institutions allocate capital in real time. Another emerging trend is the application of net present worth MARR to non-financial metrics, such as environmental or social impact. A corporation evaluating a sustainability initiative might set a net present worth MARR that balances financial returns with ESG (Environmental, Social, and Governance) goals. This hybrid approach is gaining traction among impact investors who demand both profitability and purpose. As regulatory pressures mount—particularly around climate risk—the metric’s ability to quantify intangible value could make it indispensable.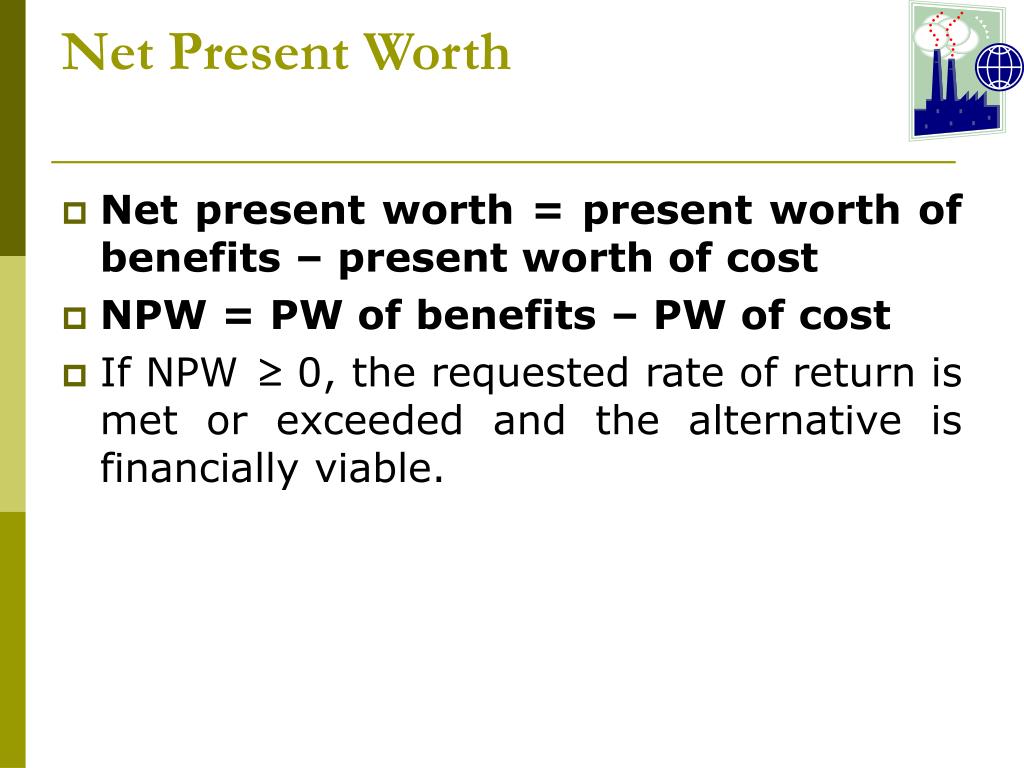
Conclusion
The rise of net present worth MARR reflects a fundamental truth: financial decisions are never purely mathematical. They’re a negotiation between numbers and narrative, between spreadsheets and strategy. What makes this metric distinctive is its refusal to compromise—it doesn’t just evaluate investments; it interrogates the assumptions behind them. In an era where capital is abundant but attention is scarce, the ability to distinguish between a good NPV and a strategically sound net present worth MARR is the difference between success and irrelevance. For investors, the takeaway is clear: net present worth MARR isn’t a replacement for intuition, but it is the ultimate disciplinarian. It forces hard choices, exposes hidden biases, and ensures that every dollar deployed is aligned with long-term objectives. Whether you’re a hedge fund manager, a family office trustee, or an entrepreneur weighing a pivot, mastering this framework isn’t optional—it’s the new standard for rational capital allocation.Comprehensive FAQs
Q: How is the MARR determined in a net present worth MARR calculation?
A: The minimum attractive rate of return (MARR) is typically derived from three sources: (1) the investor’s opportunity cost (e.g., what they could earn elsewhere), (2) their risk tolerance (higher for aggressive investors, lower for conservative ones), and (3) external benchmarks like industry averages or government bond yields. Many institutions set MARR through a consensus process involving CFOs, risk committees, and external advisors.
Q: Can net present worth MARR be used for personal finance?
A: Absolutely. Individuals can apply net present worth MARR to major decisions like buying a home, funding education, or retiring early. For example, a professional might calculate the net present worth MARR of quitting a stable job for entrepreneurship by comparing the opportunity cost of lost salary against the potential upside of the new venture.
Q: What happens if a project’s NPV is positive but fails the net present worth MARR test?
A: The project is rejected unless the investor is willing to adjust their net present worth MARR threshold downward. This is a deliberate guardrail—it prevents "good enough" investments from crowding out higher-return opportunities. Some firms even use this as a signal to renegotiate terms (e.g., lower upfront costs) rather than abandon the deal entirely.
Q: How does inflation affect net present worth MARR calculations?
A: Inflation is already embedded in the MARR, as it reflects the real (not nominal) return required to compensate for eroding purchasing power. For instance, if inflation is 3% and an investor demands a 10% nominal return, their effective net present worth MARR is ~7% in real terms. Adjusting for inflation ensures the MARR remains a true measure of economic value.
Q: Are there industries where net present worth MARR is more critical than others?
A: Yes. Industries with high capital intensity (e.g., energy, infrastructure) or long payback periods (e.g., biotech, aerospace) rely heavily on net present worth MARR because miscalculations can lead to decades of stranded assets. Conversely, consumer-facing businesses with shorter cash flow cycles may use it less frequently, though even they benefit from its disciplined approach to capital allocation.
Q: Can net present worth MARR be combined with other valuation methods?
A: Not only can it be combined, but it’s often used in tandem with methods like discounted cash flow (DCF), real options pricing, and monte carlo simulations. For example, a private equity firm might run a net present worth MARR analysis alongside a scenario-based DCF to stress-test an acquisition under different economic conditions.
Q: How do tax implications factor into net present worth MARR?
A: Taxes are typically incorporated into the cash flows before discounting. For instance, if a project’s pre-tax returns are discounted at the net present worth MARR, the after-tax cash flows should reflect the investor’s marginal tax rate. Some advanced models even adjust the MARR itself to account for tax shields or deferred liabilities, though this requires granular financial modeling.
Q: What’s the biggest misconception about net present worth MARR?
A: The biggest myth is that it’s a one-size-fits-all solution. In reality, the net present worth MARR is only as good as the inputs it’s given. A poorly chosen MARR—whether too conservative or overly aggressive—can lead to either missed opportunities or reckless bets. The metric’s power lies in its customization, not its rigidity.
