Breaking Down the Numbers
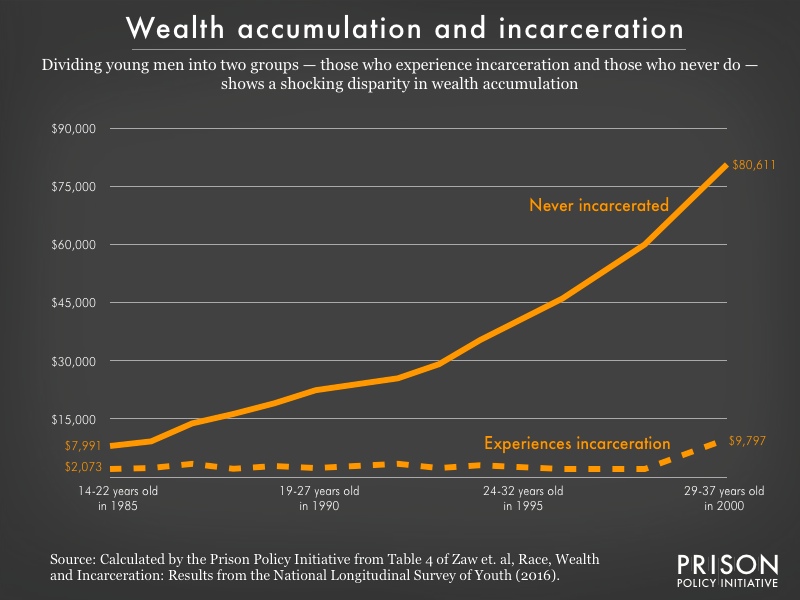
The scale of wealth disparity in America is often reduced to a single metric—the Gini coefficient—but the reality is far more granular. In 2023, the top 0.1% of households (those with net worth exceeding $30 million) held roughly 20% of the nation’s wealth, according to Federal Reserve estimates. Meanwhile, the bottom 50% collectively owned less than 2.6%. These figures aren’t just numbers; they reflect a system where asset appreciation (stocks, real estate, private equity) has become the primary engine of wealth creation, bypassing wages entirely. The median household income has stagnated for decades, adjusted for inflation, while the S&P 500 has delivered annualized returns of nearly 10%—a disparity that compounds over generations. The gap isn’t static. It’s dynamic, widening during economic expansions and contracting—only slightly—during recessions. The Great Recession of 2008 wiped out trillions in household wealth, but the recovery that followed was uneven. By 2021, the top 1% had regained all their losses and then some, while the bottom 90% were still playing catch-up. The pandemic years exacerbated this further: stimulus checks and rent relief provided temporary relief, but they didn’t address the structural issues. Wealth disparity in America today is less about income inequality and more about the accumulation of assets—and who controls them.The Verified Baseline
Public data confirms what anecdotal evidence has long suggested: the wealth gap is persistent and deepening. The Federal Reserve’s Survey of Consumer Finances, conducted every three years, provides the most reliable snapshot. In 2022, the median net worth for a white household was $188,200, compared to $36,100 for a Black household and $74,500 for a Hispanic household. These aren’t outliers; they’re the result of decades of policy choices, from redlining in the mid-20th century to the erosion of labor unions in the late 20th. Homeownership rates tell a similar story: 73% of white families own their homes, versus 44% of Black families and 48% of Hispanic families. Wealth disparity in America isn’t just a matter of income—it’s a legacy of systemic barriers. The tax code further entrenches this divide. The top 1% pay a lower effective tax rate than the middle class, thanks to loopholes that favor capital gains over earned income. Corporate tax avoidance—estimated at $1 trillion annually in lost revenue—also disproportionately benefits those who can afford high-priced tax advisors. The result? A system where wealth begets more wealth, and where the lack of it becomes a self-perpetuating cycle. The data doesn’t lie: the wealth disparity in America is not an accident. It’s the product of deliberate policy choices, reinforced by economic structures that favor accumulation over distribution.What the Estimates Suggest
Industry estimates paint an even more stark picture when extended into speculative territory. For instance, private wealth managers suggest that the ultra-wealthy—those with $50 million or more—have seen their net worth grow by 15% annually over the past decade, largely through illiquid assets like private equity and venture capital. Meanwhile, the bottom 40% of Americans have seen little to no growth in real terms, with many trapped in a cycle of debt. The Brookings Institution estimates that the top 1% captured 90% of all new wealth created in the U.S. between 2009 and 2018, a period when the economy technically recovered from the Great Recession. The impact of this disparity is felt most acutely in intergenerational mobility. Studies from the Equality of Opportunity Project show that a child born into the bottom 20% of earners has only a 7% chance of reaching the top 20% as an adult. For those born into the top 20%, the odds are 40%. The wealth disparity in America isn’t just about current income—it’s about the inheritance of advantage. A child born into a family with $1 million in assets has a far greater chance of attending elite schools, securing low-interest loans, and avoiding the predatory financial products that plague lower-income households. The estimates don’t just describe inequality; they predict it.
Case Study: A Closer Look
Consider the example of Detroit’s bankruptcy in 2013, a microcosm of how wealth disparity in America plays out in real time. The city’s financial collapse wasn’t caused by reckless spending alone—it was the result of decades of wealth extraction. Wealthy homeowners and corporations had already fled, taking their tax base with them, while the remaining residents—disproportionately Black and poor—were left holding the bag. Pension cuts for public workers, the privatization of city assets, and the failure to reinvest in infrastructure all contributed to a fiscal crisis that was, in many ways, predictable. The bailout that followed prioritized bondholders over residents, with creditors receiving $7 billion in payouts while retirees saw their pensions slashed. The fallout revealed the true cost of wealth disparity. Home values in Detroit plummeted, but the city’s wealthiest residents—those who could afford to leave—had already transferred their assets to suburban counties with lower taxes and better schools. The middle class, meanwhile, saw their savings evaporate, and the poor were left with few options beyond predatory lending. The case of Detroit isn’t unique; it’s a template for how wealth disparity in America hollows out cities, leaving behind populations with little political or economic power to demand change."Wealth inequality isn’t a bug in the system—it’s the system itself. The rules are written to protect the accumulation of capital, not the creation of opportunity." — Thomas Piketty, Capital in the Twenty-First Century
| Factor | Estimated Impact on Wealth Disparity |
|---|---|
| Tax Policy (Capital Gains vs. Earned Income) | The top 1% pay an effective rate of ~15% on capital gains, while the middle class pays ~22% on wages. |
| Homeownership Gaps | White households are 3x more likely to own homes than Black households, translating to $200K+ in lost wealth over a lifetime. |
| Corporate Profits vs. Wages | Since 2000, corporate profits have grown 120%, while wages have grown ~15%. Most gains flow to shareholders, not workers. |
| Private Equity & Leveraged Buyouts | Estimated $1 trillion+ in worker wages has been stripped via LBOs since 2000, with proceeds going to private equity firms. |
| Student Loan Debt | The bottom 40% of earners hold 60% of all student debt, while the top 20% hold 10%. Debt suppresses wealth-building. |
What This Means Going Forward
The wealth disparity in America isn’t a temporary blip—it’s a structural reality that will shape the next generation’s opportunities. Without intervention, the trends suggest a future where the ultra-wealthy control not just economic resources but political ones as well. Campaign finance laws already favor the rich, and as wealth becomes more concentrated, so too will influence over policy. The result? A feedback loop where the rules are written to benefit those who already have the most, ensuring that the disparity persists—or worsens. The solutions aren’t simple, but they require addressing the root causes: tax reform that closes loopholes for the ultra-wealthy, expanded access to homeownership and education, and policies that prioritize wage growth over shareholder returns. The alternative is a society where the American Dream is reserved for a select few, and where the rest are left to navigate an economy rigged against them. The question isn’t whether wealth disparity in America will continue—it’s whether the political will exists to change it.
Conclusion
Wealth disparity in America is more than a statistic. It’s a measure of power, a reflection of who gets to write the rules of the economy, and a predictor of who will inherit the future. The data doesn’t just describe inequality—it exposes the mechanisms that create and sustain it. From tax codes that favor capital over labor to education systems that replicate advantage, the structures are in place. The challenge now is whether society will recognize these structures for what they are: not neutral policies, but choices—choices that have been made, and choices that can be unmade. The conversation about wealth disparity in America has too often been framed as a moral debate, but it’s fundamentally an economic one. The numbers don’t lie, and the trends are clear. The question is whether the next generation will demand a different set of rules—or whether they’ll accept a future where opportunity is determined by birth, not effort.Comprehensive FAQs
Q: How does wealth disparity in America compare to other developed nations?
The U.S. has the highest wealth inequality among developed nations, according to the OECD. While countries like Germany and France have seen rising inequality, their Gini coefficients remain lower than America’s. The key difference? The U.S. lacks universal healthcare, strong labor unions, and progressive taxation—all of which mitigate disparity elsewhere.
Q: Can wealth disparity in America be fixed without radical policy changes?
Unlikely. Incremental reforms (e.g., higher marginal tax rates, expanded child tax credits) can help at the margins, but structural change requires addressing asset concentration, corporate power, and intergenerational wealth transfer. Without tackling these, the gap will persist—or widen.
Q: How does wealth disparity in America affect small businesses?
Small businesses owned by minorities and low-income individuals struggle to access capital, while wealthy entrepreneurs benefit from inherited wealth, venture capital networks, and tax advantages. Studies show that Black-owned businesses receive just 1% of venture capital, despite making up 14% of the population.
Q: Does wealth disparity in America explain political polarization?
Yes. The ultra-wealthy have disproportionate influence over elections, lobbying, and media. As wealth concentrates, so does political power—leading to policies that favor the rich (e.g., tax cuts, deregulation) while leaving the rest to navigate a shrinking safety net.
Q: How does student loan debt worsen wealth disparity in America?
Student debt suppresses homeownership, entrepreneurship, and savings for the bottom 60% of earners. Meanwhile, the top 20%—who rarely take on student loans—benefit from inherited wealth and low-interest loans for investments. The result? A $1.7 trillion wealth transfer from young borrowers to older, wealthier generations.
Q: Are there any bright spots in the fight against wealth disparity in America?
Yes, but they’re localized. Cities like San Francisco and Seattle have seen success with progressive tax policies, affordable housing initiatives, and unionization efforts. However, these gains are often offset by corporate resistance and state-level rollbacks (e.g., anti-union laws, tax breaks for the wealthy).
Q: What’s the biggest misconception about wealth disparity in America?
That it’s inevitable or merit-based. The data shows that 90% of wealth accumulation comes from inheritance, not hard work. The system is designed to reward those who already have advantages—whether through family wealth, elite education, or political connections.
