The Complete Overview of Mattel’s 2018 Financial Landscape
Mattel’s fiscal year 2018 closed with a mixed bag of metrics that underscored its dual nature: a heritage powerhouse with a struggling public face. While the company’s reported revenue hovered around the $2.6 billion mark—down slightly from prior years—the decline masked deeper structural issues. Activist investor Paul Singer’s push for cost cuts and leadership changes had already reshaped the board by early 2018, forcing Mattel to confront inefficiencies in its supply chain and marketing spend. Yet, the same year saw Barbie’s 58th anniversary celebrations, a milestone that, in theory, should have bolstered its brand valuation—a key component of Mattel net worth 2018 assessments. The disconnect between perception and performance was stark. Internally, Mattel’s R&D investments in augmented reality toys (like the Barbie Dreamhouse app) signaled a pivot toward tech-driven play, but these initiatives required years to yield tangible returns. Externally, competitors like Hasbro and Lego were outpacing Mattel in both innovation and stock appreciation. Analysts debated whether Mattel’s asset-heavy model—rooted in physical inventory and licensing deals—was sustainable in an era where digital-first brands were redefining the toy industry. The answer would hinge on how well Mattel could monetize its IP without overleveraging its balance sheet.Historical Background and Evolution
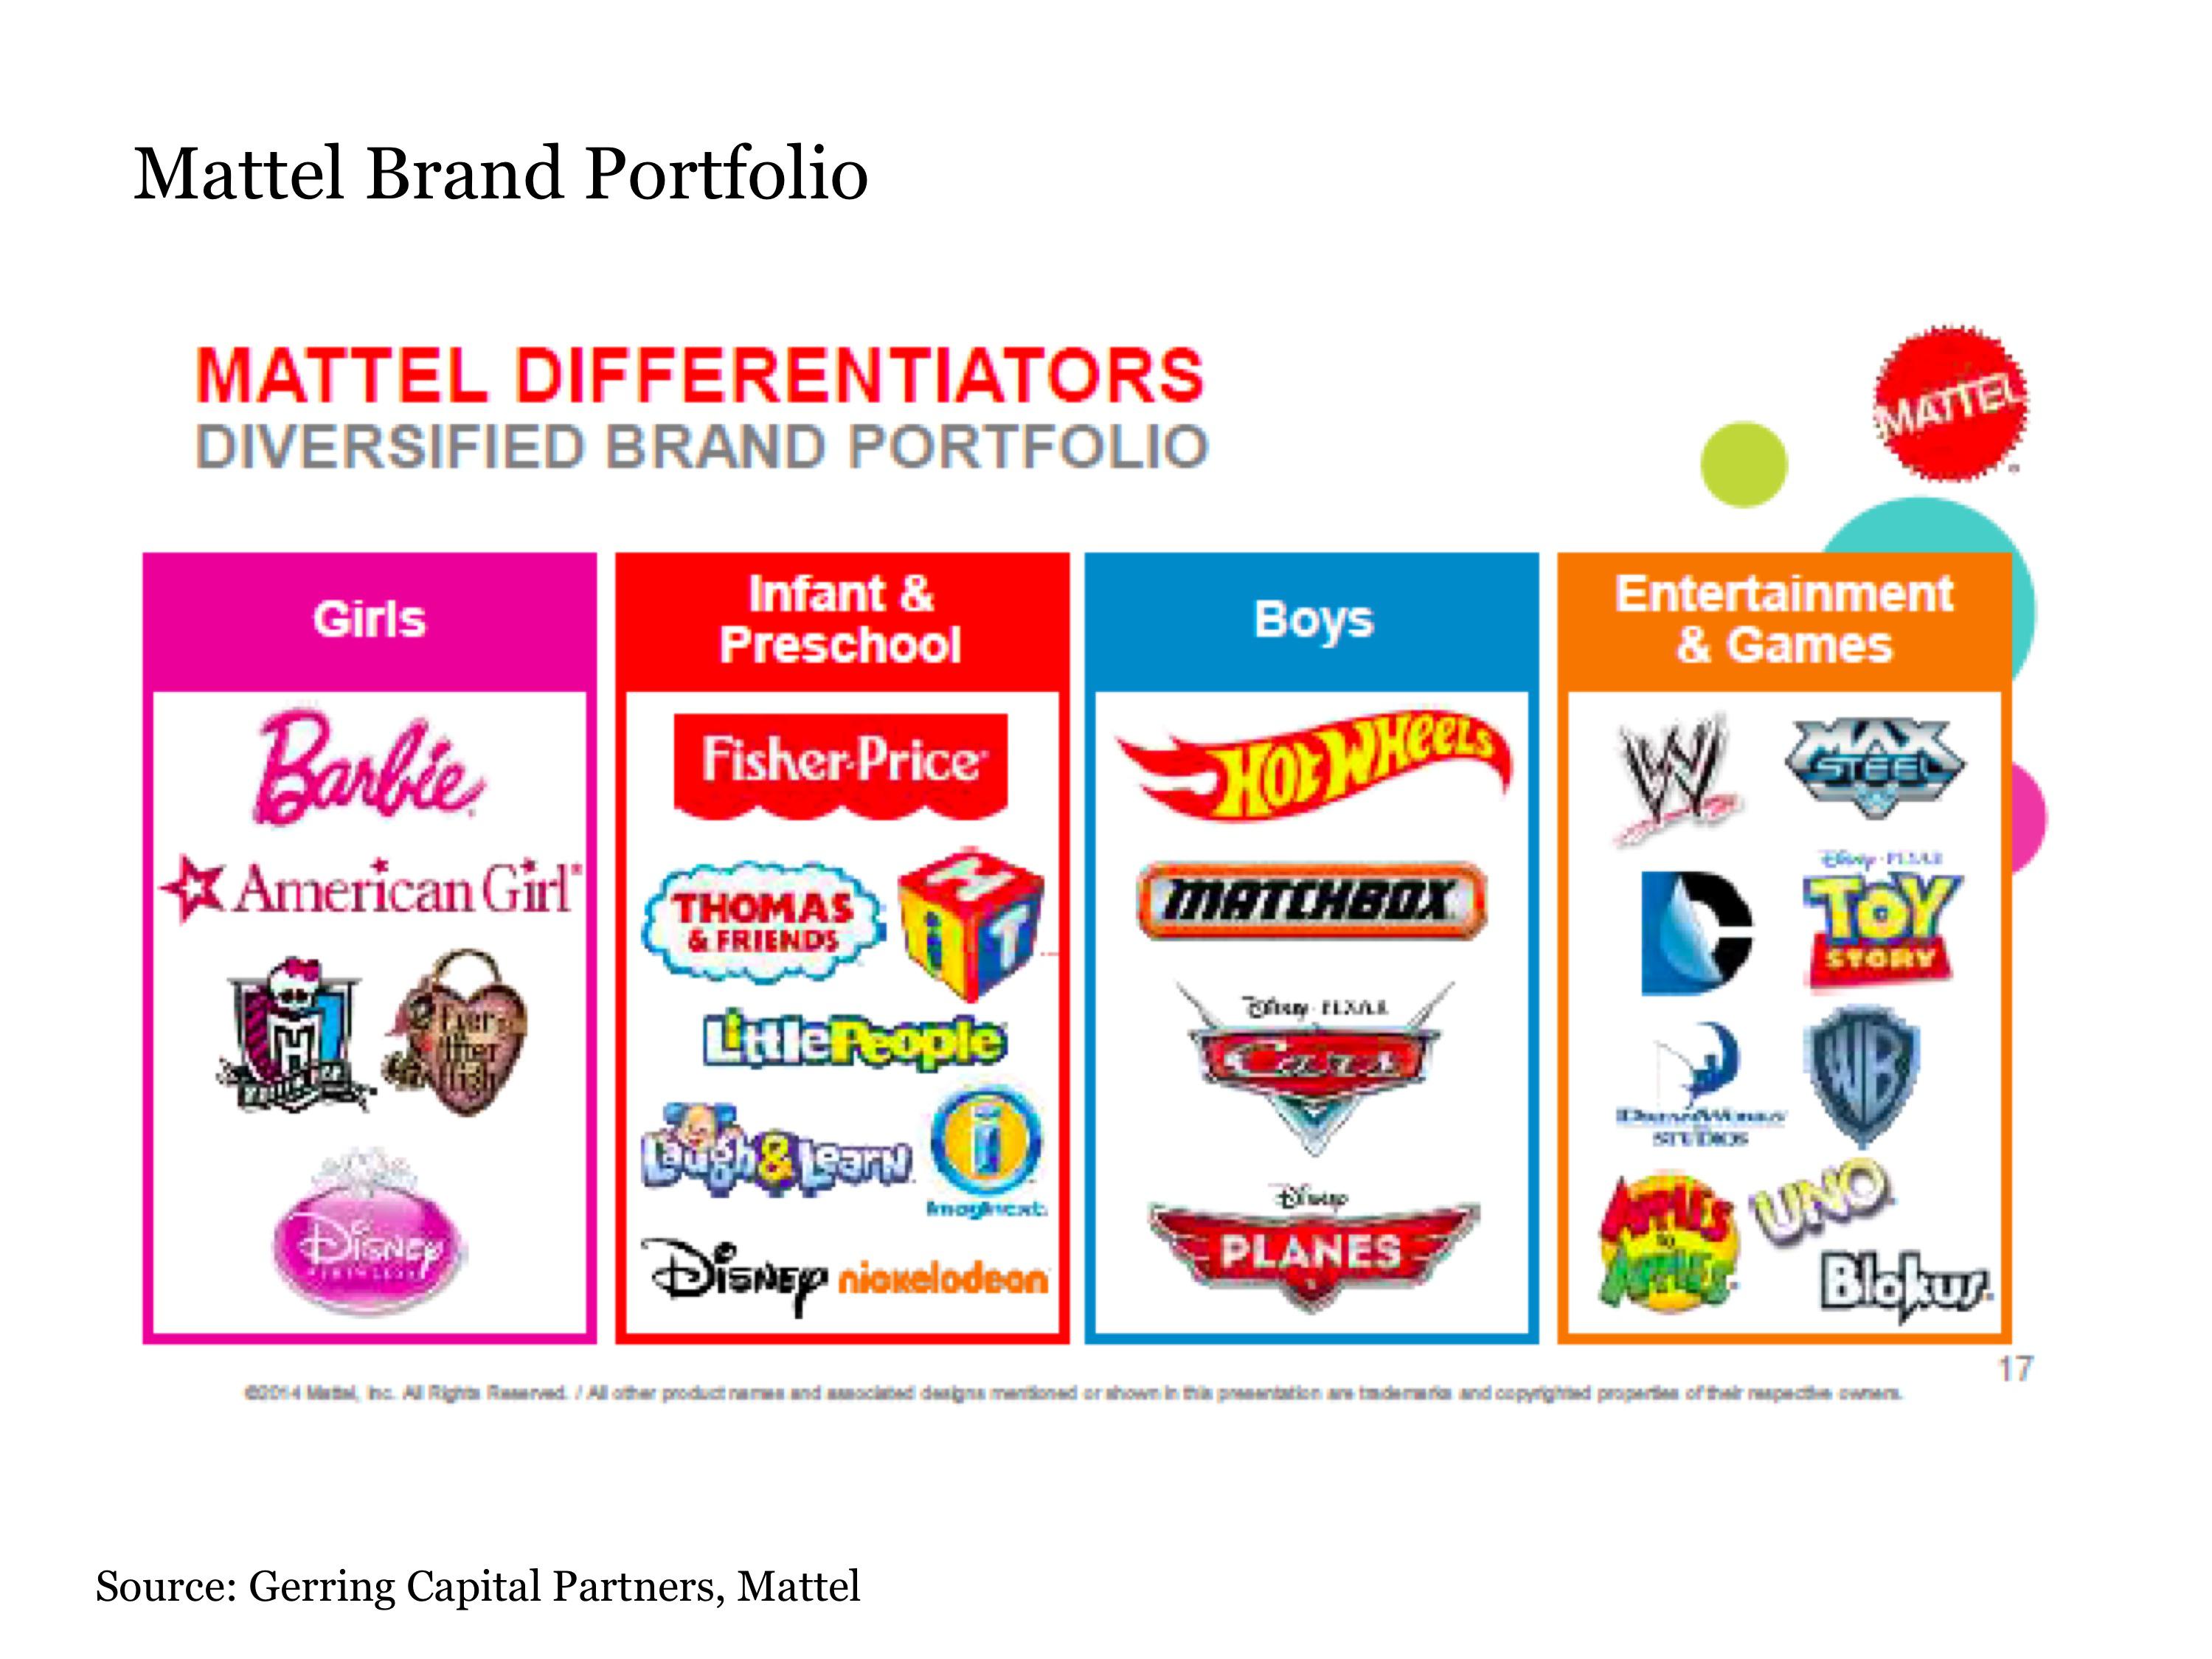
Mattel’s trajectory in the late 2010s was shaped by decades of strategic missteps and occasional brilliance. Founded in 1945, the company’s rise was built on two pillars: Barbie, which debuted in 1959 and became a cultural icon, and Hot Wheels, launched in 1968 as a response to Matchbox’s dominance. By the 2000s, Mattel’s portfolio expanded to include Fisher-Price, American Girl, and Thomas & Friends, but this diversification came at a cost—operational sprawl diluted focus. The financial crisis of 2008 exposed these weaknesses, leading to layoffs and a 2011 spin-off of Fisher-Price to Mattel Creations. Entering 2018, Mattel’s net worth was a function of its brand equity, physical assets, and intellectual property—yet its stock price had underperformed for years. The company’s enterprise value was estimated at roughly $3 billion by some analysts, though this figure was volatile given its debt load and fluctuating revenue. The arrival of Paul Singer’s Elliott Management in 2017 accelerated a reckoning: Mattel needed to either streamline operations or risk being acquired by a larger conglomerate. The stakes were clear—Mattel net worth 2018 wasn’t just a number; it was a litmus test for its survival strategy.Core Mechanisms: How It Worked
Mattel’s financial model in 2018 relied on three interlocking systems: licensing revenue, direct-to-consumer sales, and wholesale distributions. Licensing accounted for a significant portion of its income, with Barbie alone generating billions through partnerships with brands like Mattel Creations and third-party retailers. Direct sales, meanwhile, were concentrated in North America and Europe, where seasonal toy launches (back-to-school, holidays) drove spikes in cash flow. Wholesale, however, was a double-edged sword—while it expanded reach, it also tied up capital in unsold inventory. The company’s working capital was another critical lever. Mattel’s supply chain, stretched across Asia and North America, incurred high logistics costs, which squeezed margins. In 2018, efforts to reduce these costs included renegotiating contracts with manufacturers and exploring near-shoring options—a costly but necessary shift. Yet, the real challenge was balancing these operational tweaks with R&D spending. Mattel’s bet on AR-enhanced toys and subscription-based play services (like Barbie’s digital companions) required upfront investment with uncertain payoffs. The tension between short-term cost-cutting and long-term innovation defined Mattel’s financial calculus in 2018.Key Benefits and Crucial Impact
Mattel’s enduring strength lay in its portfolio of evergreen brands, each with decades of consumer trust. Barbie, for instance, wasn’t just a doll—it was a cultural asset with merchandising extensions into fashion, film, and even adult collectibles. This multi-generational appeal ensured steady licensing fees, even during downturns. Hot Wheels, meanwhile, maintained a loyal fanbase through limited-edition releases and racing events, proving that nostalgia could drive sales in an era of disposable toys. Yet, the benefits of Mattel’s legacy were tempered by risks. Its reliance on physical inventory made it vulnerable to retail disruptions, such as Amazon’s encroachment into toy sales or Walmart’s shifting buying patterns. The company’s debt-to-equity ratio was another red flag, signaling that aggressive cost-cutting might not be enough to stabilize its 2018 financial position. Still, Mattel’s ability to license its IP to media franchises (e.g., Barbie movies, Hot Wheels racing series) provided a hedge against pure retail exposure."You can’t just sell toys—you have to sell experiences." — Mattel CEO Ynon Kreiz, 2018 earnings call
Major Advantages
- Brand stickiness: Barbie and Hot Wheels remain among the most recognized toy names globally, with licensing deals generating recurring revenue streams.
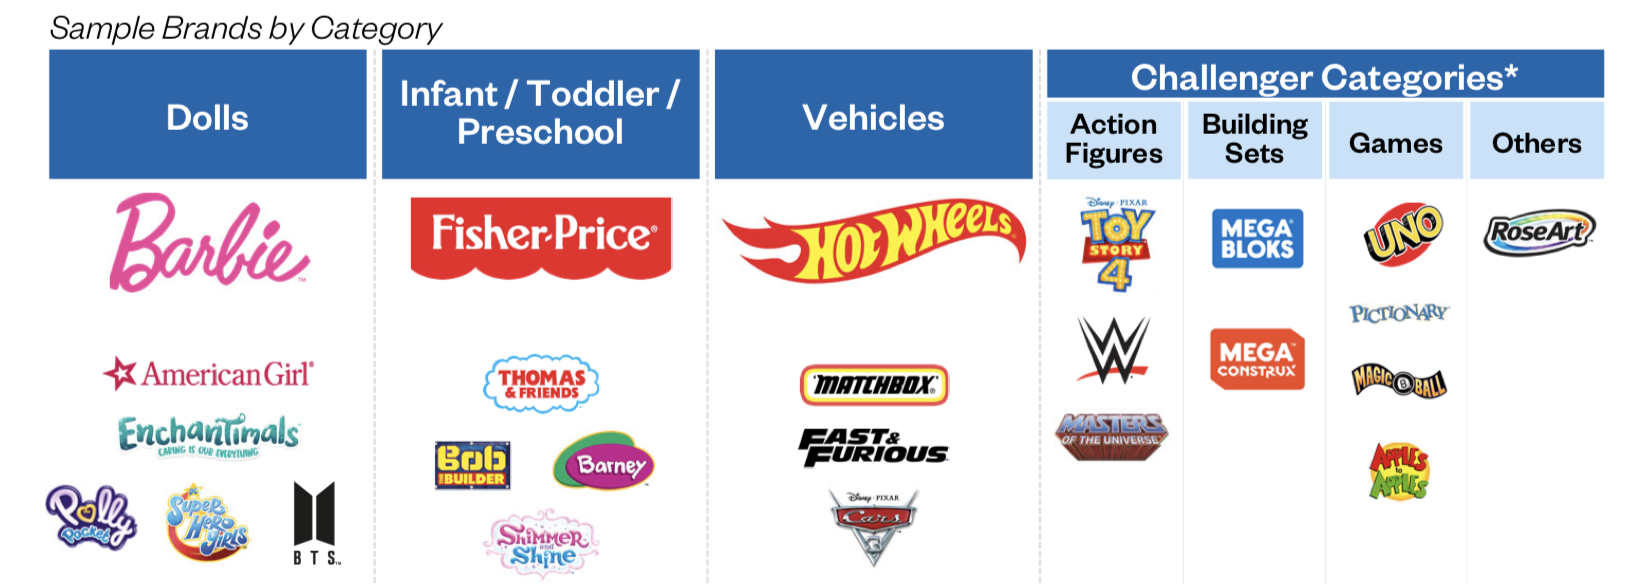
- Diversified IP: Beyond core brands, Mattel’s portfolio included American Girl (historical storytelling) and Thomas & Friends (family-friendly franchises), reducing reliance on any single product.
- Retail partnerships: Long-standing relationships with Walmart, Target, and Toys “R” Us (pre-collapse) ensured shelf presence, though this came with high wholesale markups.
- Cultural relevance: Mattel’s ability to tie its brands to trends—e.g., Barbie’s 2018 push for diversity in doll designs—kept it in media headlines, indirectly boosting perceived net worth.
Comparative Analysis
| Metric | Mattel (2018) | Hasbro (2018) |
|---|---|---|
| Revenue | ~$2.6B (down ~5%) | ~$5.1B (stable) |
| Market Cap | ~$3B (volatile) | ~$12B (strong) |
| Key Growth Driver | Licensing (Barbie, Hot Wheels) | Gaming (Monopoly, Dungeons & Dragons) |
| Debt Load | High (activist pressure) | Moderate (strong cash flow) |
| Innovation Focus | AR toys, digital play | Hybrid physical/digital (e.g., Monopoly app) |
Future Trends and Innovations
By late 2018, Mattel’s leadership was doubling down on digital integration as a path to revive growth. The Barbie Dreamhouse app, launched in 2017, was an early experiment in blending physical and digital play, but it required a broader ecosystem to succeed. Meanwhile, partnerships with tech firms (rumored collaborations with Google on AR toys) hinted at a shift toward smart playthings—a space where competitors like Lego were already making inroads with Lego Boost. The bigger question was whether Mattel could execute these transitions without alienating its core audience. Older consumers might resist digital overlays on classic toys, while younger buyers expected seamless tech integration. The company’s 2018 net worth thus became a proxy for its ability to straddle these divides. If it failed, the alternative—acquisition by a larger player—loomed as the most likely outcome.
Conclusion
Mattel’s 2018 financial year was a microcosm of the toy industry’s broader struggles: legacy brands clashing with digital disruption, activist pressures reshaping governance, and the ever-present risk of irrelevance. The company’s net worth in 2018 wasn’t just a balance-sheet figure; it was a reflection of its ability to monetize nostalgia while investing in the future. Barbie and Hot Wheels remained cultural touchstones, but their financial returns were no longer guaranteed. For investors, the takeaway was clear: Mattel’s survival depended on two moves—pruning costs aggressively and betting big on innovation. Whether these strategies would pay off remained an open question as 2019 approached. One thing was certain: the phrase "Mattel net worth 2018" would be remembered not just for its numbers, but for the existential choices it forced upon the company.Comprehensive FAQs
Q: What was Mattel’s exact revenue in 2018?
A: Mattel’s reported revenue for fiscal year 2018 was approximately $2.6 billion, a decline from prior years. Exact figures varied slightly by quarter, with holiday seasons typically driving spikes in sales.
Q: Did Mattel’s stock price improve in 2018?
A: No. Mattel’s stock underperformed throughout 2018, reflecting investor concerns over debt levels and sluggish revenue growth. Activist investor Paul Singer’s involvement pressured the company to implement cost-saving measures, but these didn’t immediately translate to stock gains.
Q: How did Barbie contribute to Mattel’s net worth in 2018?
A: Barbie was Mattel’s largest revenue driver, generating billions through doll sales, licensing deals (e.g., fashion collaborations), and media adaptations. Analysts estimated her brand valuation alone could exceed $1 billion, though exact figures were proprietary. Her cultural relevance ensured steady licensing income, even during retail downturns.
Q: Were there rumors of Mattel being acquired in 2018?
A: Speculation about a potential acquisition surfaced intermittently in 2018, particularly as Mattel’s stock struggled and debt levels rose. Hasbro and private equity firms were occasionally cited as potential suitors, but no concrete offers materialized. The company’s leadership emphasized organic growth strategies over a sale.
Q: What was Mattel’s biggest financial challenge in 2018?
A: The primary challenge was balancing short-term cost reductions (demanded by activists) with long-term innovation investments (needed to compete with digital-native brands). Overleveraging its balance sheet while failing to modernize its product lineup risked marginalizing Mattel in a rapidly evolving industry.
