Where It All Began
The debate over whether stocks belong in liquid net worth traces back to the birth of modern finance. In the early 20th century, when stock exchanges were fledgling institutions and liquidity was scarce, assets were divided into two crude categories: cash (immediately spendable) and everything else (speculative or tied up). Publicly traded stocks fell into the latter camp because selling them required a buyer—something not always guaranteed during panics. The 1929 crash reinforced this view: even blue-chip stocks could become worthless overnight if no one was willing to take the risk. By the 1950s, as institutional investing grew, the definition of liquidity evolved. Pension funds and mutual funds began treating stocks as near-cash equivalents, assuming they could be liquidated within a reasonable timeframe (weeks, not months). The rise of index funds in the 1970s further blurred the lines—suddenly, millions of dollars’ worth of equities could be moved with a single phone call. Yet the question persisted: If a stock can be sold, but selling it might trigger a fire sale, does it still count as liquid?The Early Signs
The first cracks in the old paradigm appeared in the 1980s, when leveraged buyouts and junk bonds introduced a new variable: forced liquidation. Highly leveraged firms discovered that even liquid assets like stocks could become illiquid if creditors demanded immediate repayment. The 1987 Black Monday crash exposed another flaw—market liquidity isn’t absolute. On that day, even the most tradable stocks saw bid-ask spreads widen dramatically, making it harder to execute large trades without moving the market. Meanwhile, the rise of exchange-traded funds (ETFs) in the 1990s changed the game. ETFs promised the liquidity of stocks with the diversification of mutual funds. For the first time, investors could treat a basket of assets as a single, highly liquid security. This shift forced accountants and financial planners to reconsider: if an ETF tracking the S&P 500 could be bought or sold in seconds, why wasn’t it as liquid as cash?The Turning Point
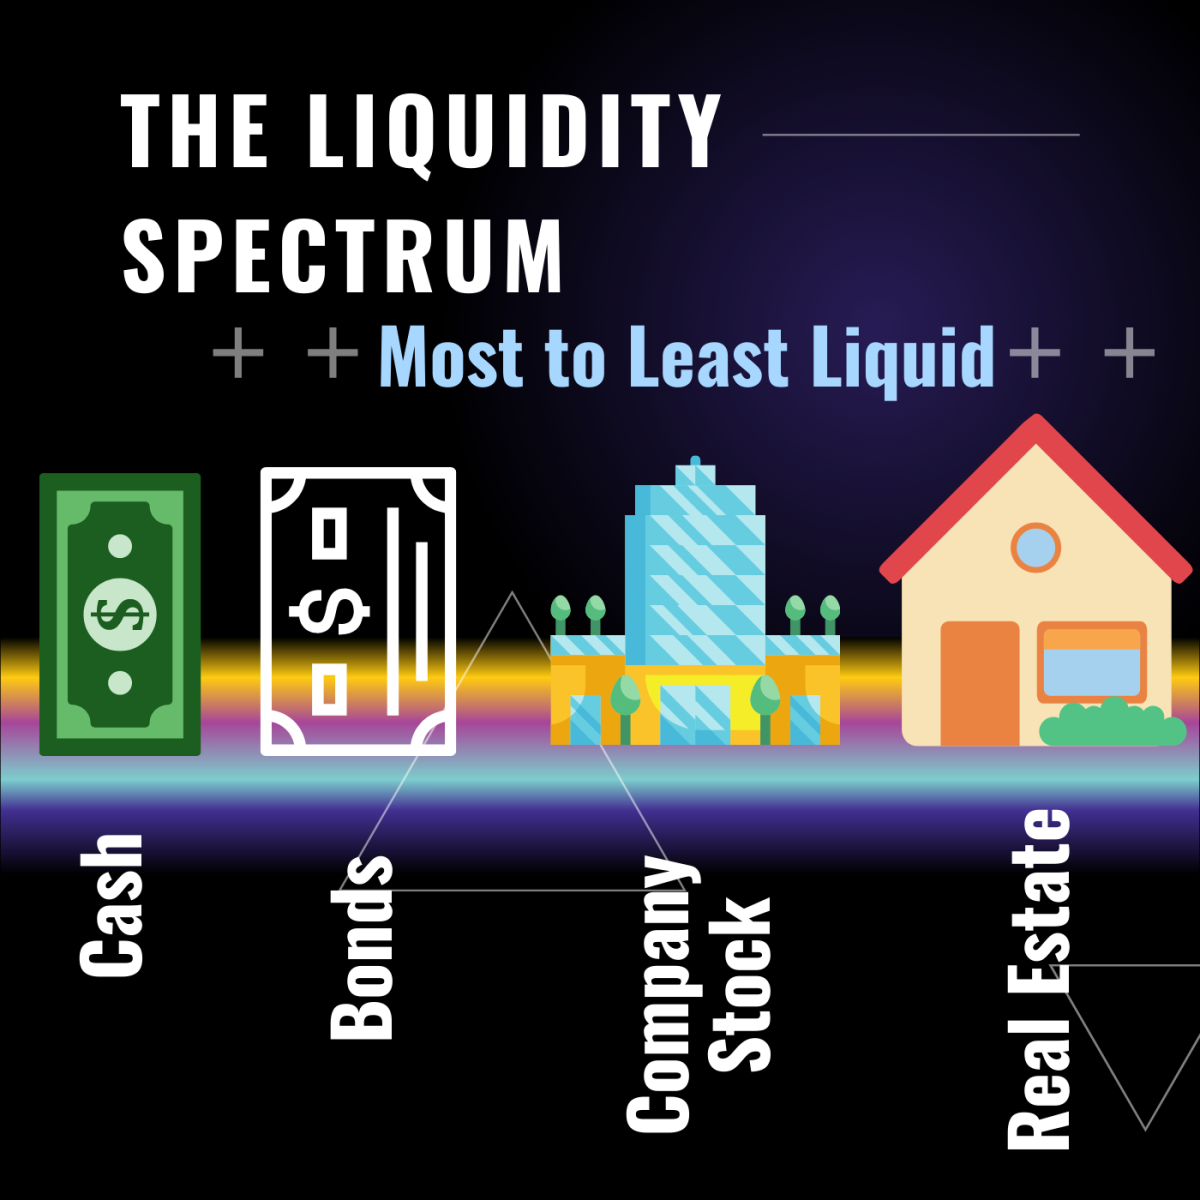
The 2008 financial crisis didn’t just answer the question—it weaponized it. When Lehman Brothers collapsed, even the most liquid stocks became toxic. The SEC temporarily halted short-selling, and bid-ask spreads on major indices spiked. Overnight, a portfolio worth $10 million on paper might only fetch $7 million in a fire sale. This was the moment when the distinction between theoretical liquidity (what a stock is worth on a statement) and practical liquidity (what it fetches in a crisis) became critical. Financial planners began advising clients to separate their net worth into tiers: immediately liquid (cash, money market funds), short-term liquid (stocks in high-volume ETFs), and long-term illiquid (private equity, real estate). The crisis proved that even the most tradable assets could freeze up when confidence vanished. For institutions, this meant stress-testing portfolios under extreme conditions. For individuals, it meant rethinking how much of their wealth they could realistically access in a downturn."Liquidity isn’t a binary state—it’s a spectrum. The question isn’t whether stocks count, but how much of a discount you’re willing to accept to turn them into cash." — Markus Rosenbaum, CIO of a $40 billion asset management firm (2010)

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1990s | ETFs emerge, treating baskets of stocks as single liquid securities. Institutional investors start including them in liquidity calculations. |
| 2000–2007 | Leveraged finance booms; stocks held as collateral become illiquid during margin calls. The term "market liquidity risk" enters mainstream finance. |
| 2008–2010 | Financial crisis forces a reevaluation. Stocks in distressed sectors (e.g., financials) see forced sales at deep discounts, proving liquidity isn’t guaranteed. |
| 2012–2019 | Algorithmic trading and high-frequency trading compress bid-ask spreads, making large-cap stocks nearly as liquid as cash for institutional players. |
| 2020–Present | Memestock frenzy (e.g., GameStop) shows that even liquid stocks can become illiquid during short squeezes. Retail investors face slippage when trying to exit positions en masse. |
Lessons From the Journey
- Liquidity depends on the buyer. A stock may trade actively, but if no one wants to buy it at the current price, it’s effectively illiquid.
- Market conditions override asset class. Even the most liquid stocks can become stuck during crises, regulatory freezes, or flash crashes.
- Institutions and individuals face different risks. A pension fund can hold stocks for decades; a retiree may need to sell them tomorrow.
- The discount factor matters. Selling $1 million in stocks might only yield $900,000 if executed hastily—so does it count as liquid?
Where Things Stand Today
Today, the answer to "do stocks count to liquid net worth?" depends on three variables: asset class, market depth, and time horizon. Large-cap stocks in ETFs or index funds are treated as near-cash by most institutions, while small-cap or thinly traded stocks may require a liquidity haircut. The rise of fractional shares and direct-listing IPOs has further complicated the picture—assets once considered illiquid (e.g., private company shares) are now tradable, but their liquidity is still unproven. For high-net-worth individuals, the trend is toward liquidity segmentation: separating assets into tiers based on how quickly they can be converted to cash. A tech founder might classify their public equity as "liquid" but their private venture stakes as "illiquid," even if both are technically "stocks." The key insight? Liquidity isn’t a property of the asset—it’s a function of the market and the seller’s urgency.
Conclusion
The question "do stocks count to liquid net worth?" has no single answer because liquidity isn’t absolute—it’s situational. What counts as liquid for a hedge fund (a basket of blue-chip ETFs) may not qualify for a retiree relying on dividends. The 2008 crisis and the 2020 memestock rally proved that even the most tradable assets can become illiquid when conditions turn. The lesson? Treat stocks as a spectrum: some are liquid under normal conditions, others only in crises, and a few never are. For investors, this means two things: first, align your liquidity assumptions with your risk tolerance; second, stress-test your portfolio under worst-case scenarios. The stocks that seem liquid today might not be tomorrow—and that’s the difference between a smooth exit and a fire sale.Comprehensive FAQs
Q: Are stocks considered liquid assets in financial statements?
It depends on the context. Publicly traded stocks are generally classified as current assets (if held for trading) or long-term investments (if held strategically). However, their liquidity is often qualified—accountants may note restrictions like market volatility or regulatory limits on sales.
Q: How do institutions determine if stocks are "liquid enough" for net worth?
Institutions use liquidity horizons: the time it would take to sell a position without significantly impacting its price. For example, a pension fund might treat S&P 500 ETFs as liquid (sellable in days) but private equity as illiquid (years). Stress tests simulate forced sales to assess discounts.
Q: Can stocks be illiquid even if they trade daily?
Yes. Thinly traded stocks (low volume) or distressed stocks (e.g., during a short squeeze) can face wide bid-ask spreads, making them effectively illiquid. Even high-volume stocks may become illiquid if too many sellers hit the market at once (e.g., margin calls in 2008).
Q: Does holding stocks in a brokerage account make them more liquid?
Brokerage accounts improve accessibility (you can sell with a click), but liquidity still depends on market conditions. During a crash, even instantly sellable stocks may require deep discounts. Some brokers impose position limits or short-sale restrictions, further reducing liquidity.
Q: How should individuals adjust their net worth calculations for stock liquidity?
Segment your portfolio:
- Tier 1 (Immediately Liquid): Cash, money market funds, highly liquid ETFs (e.g., SPY, QQQ).
- Tier 2 (Short-Term Liquid): Large-cap stocks with deep markets (e.g., Apple, Microsoft).
- Tier 3 (Illiquid): Small-cap, private equity, or stocks with low trading volume.
Q: What’s the difference between "liquid net worth" and "total net worth"?
Total net worth includes all assets (stocks, real estate, private equity) at fair market value. Liquid net worth excludes assets that can’t be quickly converted to cash without a significant loss. For example, a $5M stock portfolio might only count as $3M in liquid net worth if selling it would trigger a 40% discount.
Q: Are dividends from stocks considered liquid income?
Dividends are cash flow, not liquid assets—but they contribute to liquidity over time. However, if an investor relies on dividends for living expenses, a dividend cut (e.g., during a recession) can suddenly reduce liquidity. Some advisors treat annualized dividend income as a liquidity buffer.
Q: How do tax implications affect stock liquidity?
Taxes reduce after-sale proceeds, effectively lowering liquidity. For example, selling stocks at a gain may trigger capital gains taxes, leaving less cash than the gross sale price. Short-term capital gains (held <1 year) are taxed as income, further eroding liquidity. Tax-loss harvesting can offset this but adds complexity.
Q: What’s the worst-case scenario for stock liquidity?
The 2008 financial crisis and the 2020 GameStop short squeeze demonstrated extreme illiquidity:
- In 2008, even blue-chip stocks saw 20–50% discounts in forced sales.
- In 2020, retail traders piled into meme stocks, causing bid-ask spreads to widen—some investors couldn’t exit positions without massive losses.
