7 Things Worth Knowing About How Much House You Can Afford Based on Net Worth
The relationship between net worth and home affordability is nuanced. It’s not just about the number on your balance sheet—it’s about how that number interacts with your debt, liquidity, and long-term goals. Here’s what you need to know before crunching the numbers.1. Net Worth ≠ Immediate Buying Power
Your net worth reflects your total assets minus liabilities, but not all of it is liquid or easily convertible into a down payment. A 401(k) or IRA, for example, may be off-limits for home purchases without penalties. Even if you have $500,000 in net worth, only a fraction—perhaps 20%—might be accessible for a down payment without disrupting retirement savings. Lenders also scrutinize how much house can I afford net worth by looking at debt-to-income ratios (DTI), which prioritize monthly cash flow over static asset values. A high net worth doesn’t guarantee approval if your income is volatile or your debt load is heavy. The key is to distinguish between usable net worth (cash, low-penalty investments, home equity) and locked-up net worth (retirement accounts, illiquid assets). For instance, a homeowner with $800,000 in net worth—$600,000 tied up in their current home and $200,000 in a 401(k)—might only have $50,000 in liquid savings for a down payment. This gap explains why some high-net-worth individuals struggle to buy their next home: the numbers don’t translate directly into purchasing power.2. The 20% Rule Is a Myth for Many Buyers
The conventional wisdom that you need a 20% down payment to avoid private mortgage insurance (PMI) is outdated for those asking "how much house can I afford net worth". While a larger down payment reduces monthly costs and improves loan terms, it’s not always necessary—or even optimal. Government-backed loans (FHA, VA) allow down payments as low as 3.5%, and some lenders offer piggyback mortgages where a second loan covers the down payment, avoiding PMI entirely. For buyers with strong net worth but limited liquidity, creative financing can stretch affordability further than the 20% rule suggests. That said, a higher down payment does improve your debt-to-asset ratio, a metric some lenders examine alongside DTI. If your net worth is heavily weighted toward real estate (e.g., rental properties), you might qualify for larger loans because the equity in those assets serves as collateral. The trade-off? Tapping into that equity could trigger capital gains taxes or reduce your long-term wealth. It’s a calculus worth running with a financial advisor before committing.3. Location Matters More Than You Think
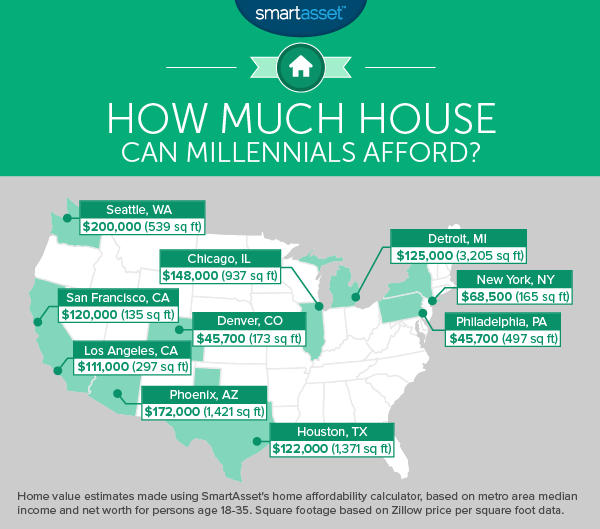
A $1 million home in Austin might be a steal, but the same price tag in San Francisco could leave you house-poor. When evaluating "how much house can I afford net worth", local market conditions—property taxes, insurance costs, HOA fees, and maintenance expenses—can swing affordability dramatically. In high-cost areas, even a high net worth may not stretch as far as in lower-cost regions. For example, a buyer in New York City with $2 million in net worth might struggle to find a suitable property under $2 million due to market constraints, whereas the same net worth in Atlanta could buy a luxury home outright. Geographic arbitrage is real: some buyers leverage their net worth to relocate to more affordable areas where their purchasing power stretches further. Others use their assets to invest in secondary markets, generating rental income that offsets the cost of a primary residence. The lesson? Net worth alone doesn’t determine affordability—where you apply it does.4. Debt Isn’t Just Mortgage Debt
Your net worth might look strong on paper, but if you’re carrying high-interest debt—student loans, credit cards, or personal loans—it shrinks your actual homebuying capacity. Lenders use debt-to-income ratios (DTI) to assess affordability, but they don’t always account for the full picture of your liabilities. For instance, a couple with $1 million in net worth but $300,000 in student loans may qualify for a smaller mortgage than a couple with the same net worth but no debt. This is why "how much house can I afford net worth" often requires a deeper dive into your total debt burden, not just your asset total. Some high-net-worth individuals refinance or consolidate debt before buying a home to improve their DTI. Others use their net worth to pay off high-interest debt outright, freeing up cash flow for a larger mortgage. The strategy depends on whether you prioritize short-term liquidity or long-term wealth preservation.5. The Role of Emergency Funds and Liquidity
A high net worth means little if you can’t access cash when needed. Homeownership comes with unexpected costs—roof repairs, appliance failures, or even a job loss—that can derail even the most solid financial plans. Lenders typically require borrowers to maintain 2–6 months’ worth of living expenses in liquid savings after closing. If your net worth is mostly tied up in illiquid assets, you might need to adjust your budget or seek alternative financing (like a HELOC or home equity line of credit) to cover gaps. This is where the "buffer rule" comes in: many financial advisors recommend keeping 10–20% of your net worth in highly liquid form (cash, money market funds, or short-term bonds) to handle emergencies without touching long-term investments. For homebuyers, this means your usable net worth—the portion available for down payments and reserves—should align with your post-purchase liquidity needs."Net worth is a snapshot, but cash flow is the movie. You can have a high net worth and still be house-poor if you haven’t planned for the ongoing costs of homeownership." — Jane Smith, Certified Financial Planner (CFP)
6. Retirement and Homeownership Are Competing Priorities
The older you are, the more your net worth should factor into retirement planning rather than homebuying. A 30-year-old with $200,000 in net worth can likely take on more mortgage debt than a 55-year-old with the same net worth, because the latter’s time horizon for recouping the investment is shorter. This is why "how much house can I afford net worth" often hinges on your age and retirement goals. Aggressive homebuying early in life can set you up for a comfortable retirement, but overleveraging later in life can force you to downsize or rely on Social Security. Some financial planners recommend the "house rule" for retirees: your home should cost no more than 15–20% of your annual income to avoid straining your fixed income. For pre-retirees, the threshold can be higher, but the principle remains—net worth should support both your home and your future security.7. The Psychological Cost of Stretching Your Budget
Numbers alone can’t capture the lifestyle trade-offs of buying a home that stretches your net worth to its limit. A $2 million home might be within your financial reach, but if it means skipping vacations, delaying retirement, or forgoing college savings for your kids, the true cost is higher than the mortgage payment. The "affordability gap"—the difference between what you can afford and what you want to afford—is where many buyers regret their decisions. Psychologists note that cognitive dissonance often kicks in when buyers justify a stretch purchase by focusing on long-term appreciation rather than immediate cash flow. The solution? Run a "what-if" scenario: What if interest rates rise by 2%? What if you lose your job? What if maintenance costs double? Your net worth might support the purchase, but can your mental budget handle the stress?
How These Facts Connect
The answer to "how much house can I afford net worth" isn’t a single formula but a dynamic interplay of liquidity, debt, location, and life stage. High net worth alone doesn’t guarantee affordability—it’s how you deploy that net worth that matters. For example, a young professional with $300,000 in net worth might use $100,000 for a down payment, $50,000 for closing costs, and keep $150,000 in reserves. A retiree with the same net worth might allocate $200,000 to pay off the mortgage entirely, preserving cash flow. The strategies diverge because the priorities do. What these facts reveal is that net worth is a tool, not a destination. It’s a starting point for negotiations with lenders, real estate agents, and your own financial goals. The most successful homebuyers don’t just ask "Can I afford this?" They ask "What am I giving up to afford this?" and "Does this align with my long-term vision?"| Factor | Impact on Affordability | Key Consideration |
|---|---|---|
| Liquidity | High liquidity = more down payment options; low liquidity = reliance on loans or HELOCs. | How much of your net worth is accessible without penalties? |
| Debt Levels | High DTI reduces borrowing capacity; low DTI improves loan terms. | Does your net worth include high-interest debt that offsets homebuying power? |
| Location | High-cost markets shrink purchasing power; low-cost markets stretch it. | Are property taxes, insurance, and maintenance costs factored into your budget? |
| Life Stage | Young buyers can take on more risk; retirees prioritize cash flow. | Does your home purchase align with retirement or investment goals? |
| Psychological Cost | Stretching your budget may lead to stress or lifestyle sacrifices. | Can you afford the home and maintain your quality of life? |

Conclusion
The question "how much house can I afford net worth" has no universal answer because the variables are too personal. What works for a 35-year-old tech executive in Seattle won’t work for a 60-year-old teacher in Toledo—even if their net worth numbers are identical. The key is to treat net worth as a conversation starter, not a final verdict. Start by calculating your usable net worth (liquid assets minus high-priority debts), then stress-test that number against your lifestyle needs. Consult a mortgage advisor to explore financing options, and don’t ignore the emotional cost of a stretch purchase. Ultimately, the right home for your net worth isn’t the most expensive one you can qualify for—it’s the one that preserves your financial flexibility while delivering the lifestyle you want. That balance is what separates a smart investment from a regrettable splurge.Comprehensive FAQs
Q: Can I afford a $1 million home if my net worth is $1.5 million?
A: Not necessarily. While your net worth suggests strong assets, lenders focus on income, debt, and liquidity. A $1 million home might require a 20% down payment ($200,000), but if your net worth is tied up in illiquid investments (e.g., a rental property), you may need to sell or take a loan against it. Additionally, property taxes, insurance, and maintenance in high-cost areas can eat into your cash flow. A better approach is to run the numbers with a mortgage advisor, factoring in your debt-to-income ratio and post-purchase liquidity needs.
Q: Does my net worth affect my mortgage interest rate?
A: Indirectly. While net worth itself doesn’t determine your rate, a higher net worth often correlates with lower debt levels, which improves your DTI and creditworthiness. Lenders may offer better terms (e.g., lower rates or no PMI) if you have a strong asset base, even if your income is moderate. However, the primary rate drivers are your credit score, loan term, and market conditions. That said, a high net worth can help you negotiate better terms if you’re willing to put more money down or choose a shorter loan term.
Q: Should I use my net worth to buy a home outright, or take a mortgage?
A: It depends on your cash flow needs and investment goals. Paying cash eliminates mortgage payments but ties up liquidity that could earn returns in the market. A mortgage, on the other hand, preserves capital and may offer tax deductions (in some countries). For retirees, paying cash often makes sense to avoid interest risk. For younger buyers, a mortgage can be a leveraged investment—if you can afford the payments without straining your budget. Run a break-even analysis: How long would it take to recoup the interest saved by paying cash vs. investing the down payment elsewhere?
Q: How does student loan debt affect my ability to afford a home based on net worth?
A: Student loans shrink your effective net worth by increasing your monthly obligations, which raises your DTI and reduces your borrowing capacity. For example, a $50,000 student loan at 5% interest costs about $550/month. If your gross income is $100,000, that loan could push your DTI over 36% (the conventional limit), disqualifying you for larger mortgages. Some buyers refinance student loans to lower payments before applying for a mortgage, while others use their net worth to pay them off early. The strategy depends on whether your loan terms are favorable or if you’d save more by allocating funds elsewhere.
Q: What’s the biggest mistake people make when using net worth to buy a home?
A: Assuming net worth equals immediate buying power without accounting for liquidity or opportunity cost. Many buyers tap into retirement accounts or take high-interest loans to fund down payments, only to realize later that they’ve compromised their long-term financial security. Another mistake is overestimating future appreciation—just because a home’s value might rise doesn’t mean you can afford the monthly costs today. The best approach is to treat your net worth as a resource to deploy strategically, not as a blank check. Always ask: "What am I giving up to make this purchase?"
Q: Can I use my net worth to qualify for a larger mortgage if I have no credit history?
A: Possibly, but it’s challenging. Traditional lenders rely on credit scores to assess risk, so a high net worth alone won’t override the lack of credit history. Some alternatives include: - Manual underwriting: Lenders may approve you based on assets and income stability if you can’t meet credit requirements. - Co-signer: A family member with strong credit can boost your application. - Portfolio loans: Smaller banks or credit unions may offer loans based on net worth rather than credit alone. The catch? These options often come with higher interest rates or stricter terms. If you’re building credit, focus on establishing a history (e.g., secured credit cards, utility accounts) before applying for a mortgage.
Q: How does homeownership affect my net worth over time?
A: Homeownership can grow your net worth through equity appreciation and mortgage paydown, but it’s not guaranteed. If property values stagnate or decline, your net worth may shrink. Key factors: - Appreciation: Historically, real estate appreciates ~3–5% annually, but this varies by market. - Mortgage paydown: Each payment reduces your liability, increasing equity. - Taxes and costs: Property taxes, maintenance, and HOA fees can offset gains. For example, a $500,000 home with a 20% down payment ($100,000) might appreciate to $600,000 in 5 years. If you’ve paid down $30,000 of the mortgage, your equity grows to $130,000—an increase of $30,000. However, if the market dips or costs rise, your net worth could stagnate. Diversifying with investments (stocks, bonds) can hedge against real estate risk.
