
The Short Answers
- 15%-20% of U.S. households have negative net worth due to debt exceeding assets, primarily driven by student loans, medical bills, and credit card debt.
- The group skews younger and lower-income, but includes older Americans with reverse mortgages or underwater home loans.
- Negative net worth suppresses economic mobility, as these households lack collateral for loans or investments, perpetuating cycles of debt.
- Policy responses—like student debt relief or medical bankruptcy reform—could alleviate pressure, but structural issues remain unresolved.
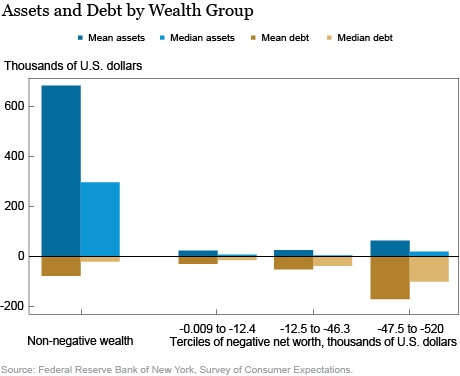
Deep Dive: The Full Picture
The 15%-20% with negative net worth aren’t a monolith. They’re a fractured cohort bound by one common thread: their debts outstrip their assets by a margin that, in many cases, can’t be closed without external intervention. The Federal Reserve’s Survey of Consumer Finances paints a clear picture—though the exact percentage fluctuates with economic cycles, the trend is undeniable. In 2022, roughly 1 in 5 households fell into this category, a figure that ballooned during the pandemic as eviction moratoriums ended and unemployment benefits expired. The composition of this group is as telling as the numbers themselves. Consider the 25-year-old with $50,000 in student loans but no home equity, no retirement savings, and a credit card balance that’s 80% of their annual income. Or the 55-year-old whose home, once a source of wealth, now carries a second mortgage taken out to cover medical expenses. Even the self-employed aren’t immune—small business owners with unpaid loans or liens on equipment find themselves in the same precarious position. The 15%-20% figure isn’t just a statistic; it’s a snapshot of how debt, when unchecked, can erode the very foundation of financial stability.The Context You Need
To understand why 15%-20% of Americans operate with negative net worth, you have to look at three interlocking factors: the cost of essentials, the erosion of wage growth, and the design of debt itself. Healthcare is the most glaring example. A single hospital stay can wipe out a family’s savings, leaving them with medical debt that, in many states, is impossible to discharge in bankruptcy. Meanwhile, wages have stagnated for decades, with real median income growth nearly flat since the 1970s. When housing costs rise faster than salaries, homeownership—traditionally the primary wealth-building tool—becomes a liability for those who can’t keep up with payments or refinance. Then there’s the debt ecosystem. Student loans, once seen as an investment in human capital, now function as a wealth drain for millions. The average borrower takes decades to repay, during which time they’re locked out of other financial opportunities—like buying a home or starting a business—because their debt-to-income ratio is too high. Credit cards, too, have become a tool of the desperate rather than the discretionary. The 15%-20% with negative net worth aren’t reckless spenders; they’re people who’ve been priced out of stability by forces beyond their control.The Mechanics
Negative net worth isn’t a static condition—it’s a feedback loop. The moment a household’s liabilities exceed assets, the options for escape narrow dramatically. Without home equity, they can’t tap into a line of credit. Without a strong credit score, they’re denied loans for education or entrepreneurship. Even if they manage to pay down debt, the damage lingers: a poor credit history can follow them for years, limiting future opportunities. This isn’t just a personal finance problem; it’s an economic one. The data shows that households with negative net worth are less likely to invest in stocks, real estate, or small businesses—activities that historically drive wealth accumulation. Instead, they’re forced into high-interest debt cycles, where every payment chips away at principal but rarely reduces the total balance. The 15%-20% figure isn’t just about individuals; it’s about a system that incentivizes debt over asset-building. And when that system fails, the consequences aren’t just personal—they’re societal.Details That Change the Picture
Not all negative net worth is created equal. A 30-year-old with $30,000 in student loans but no other debt may eventually dig out, whereas a 60-year-old with medical debt and a reverse mortgage faces a far bleaker outlook. The duration of negative net worth varies wildly: some households bounce back within a few years, while others remain trapped for decades. The racial wealth gap plays a critical role here. Black and Hispanic households are twice as likely to have negative net worth as white households, according to the Urban Institute, a disparity driven by historical redlining, lower homeownership rates, and systemic barriers to credit access. The geographic divide is equally stark. In states with high costs of living—like California, New York, or Hawaii—negative net worth rates skew higher, particularly among renters. Meanwhile, in areas with strong union presence or lower housing costs, the figure drops, though never to zero. Even education levels matter: those with some college but no degree are more likely to be in this category than those with advanced degrees, who can leverage their credentials for higher-paying jobs or professional licenses."Negative net worth isn’t a personal failure—it’s a systemic one. When you can’t build wealth because the cost of living outpaces your income, and debt is the only tool available, you’re not just poor; you’re trapped in a cycle designed to keep you there."
—Darrick Hamilton, economist and professor at The New School
| Demographic Factor | Impact on Negative Net Worth Risk |
|---|---|
| Age 25–34 | Highest risk due to student loans and entry-level wages. |
| Households with medical debt | 3x more likely to have negative net worth, per Federal Reserve data. |
| Black and Hispanic households | Disproportionately affected by wealth gaps and predatory lending. |
| Renters | No home equity means all debt is "bad debt"—credit cards, auto loans, etc. |
| Self-employed or gig workers | Lack of steady income streams exacerbates debt repayment struggles. |

Conclusion
The 15%-20% with negative net worth aren’t a blip—they’re a symptom of an economy that’s increasingly rigged against the middle and working classes. The problem isn’t laziness or poor decision-making; it’s a combination of predatory debt structures, stagnant wages, and a lack of safety nets. Ignoring this reality has consequences. When large swaths of the population can’t build wealth, consumer demand weakens, inequality deepens, and political instability grows. The solution isn’t simple, but it starts with acknowledging the scale of the issue and demanding systemic changes—from student debt relief to medical bankruptcy reform. The conversation around wealth in America has long focused on the top 1% or even the top 10%. But the 15%-20% with negative net worth represent a different kind of crisis—one where the absence of wealth is just as damaging as its concentration at the top. Addressing it requires more than personal budgeting advice; it demands a reckoning with how debt, wages, and opportunity intersect in the modern economy.Comprehensive FAQs
Q: Can someone with negative net worth still qualify for a mortgage?
A: Unlikely. Lenders typically require a debt-to-income ratio below 43% and proof of assets. With negative net worth, most conventional loans are off the table unless the borrower can secure a co-signer or government-backed program like an FHA loan, which has more lenient standards but still demands a down payment and income verification.
Q: Does negative net worth affect credit scores?
A: Indirectly. While negative net worth itself isn’t reported to credit bureaus, the debts contributing to it—like missed payments on credit cards or student loans—will. A high debt-to-income ratio can also make lenders hesitant to approve new credit, creating a vicious cycle where poor credit limits financial options further.
Q: Are there states where negative net worth is more common?
A: Yes. States with high living costs—California, New York, and Florida—see higher rates, particularly among renters. Conversely, states with strong union presence (like Michigan or Ohio) or lower housing costs (like Iowa or Nebraska) report lower percentages, though the 15%-20% national average still holds in most regions.
Q: Can negative net worth be "fixed" without drastic measures?
A: In rare cases. For those with manageable debt (e.g., a single credit card balance), aggressive repayment plans or debt consolidation loans might help. However, for most in this category—especially those with student loans or medical debt—the path to positive net worth requires external intervention, like debt forgiveness, wage increases, or asset-building programs.
Q: How does negative net worth impact retirement planning?
A: Devastatingly. Households with negative net worth are far less likely to contribute to retirement accounts, and those who do often divert funds to debt repayment instead of savings. The result? A generation facing retirement with no assets, relying on Social Security alone—a system already under strain.
Q: Is negative net worth a new phenomenon?
A: No, but its scale is. The concept dates back to economic downturns, but the 15%-20% figure has persisted since the 2008 financial crisis, with only temporary dips during economic booms. The pandemic exacerbated it, but the roots lie in decades of wage stagnation, rising costs, and debt-fueled consumption.
