
Breaking Down the Numbers
Zoom’s financial health in 2023 was defined by two opposing forces: revenue resilience and valuation volatility. The company’s annual reports and SEC filings reveal a business that grew top-line numbers even as stock prices gyrated. Quarterly earnings calls highlighted a conscious shift toward "stickiness"—measuring user retention and enterprise contracts as key metrics—rather than raw user growth. Yet the Zoom net worth 2023 narrative became entangled with broader market sentiment: tech multiples contracted, and Zoom’s stock underperformed peers like Microsoft Teams and Google Meet, despite maintaining its dominant market share. The disconnect between operational strength and shareholder returns stemmed from investor skepticism about Zoom’s ability to sustain growth beyond the pandemic. Analysts pointed to customer concentration risk—a reliance on a handful of large enterprise clients—and the looming threat of commoditization in the video conferencing space. While Zoom’s 2023 net worth estimates hovered around the $20–$25 billion range (based on trailing stock prices and diluted shares), the company’s actual intrinsic value remained a subject of debate. Private equity comparisons suggested Zoom might be undervalued relative to its cash flow, but public market discipline kept its valuation in check.The Verified Baseline
As of late 2023, Zoom’s verified net worth—calculated from its public filings—rested on three pillars: 1. Revenue: The company reported $4.1 billion in annual revenue for fiscal year 2023 (ending January 2023), a 13% year-over-year increase. Subscription services remained the core, but Zoom’s "Zoom Rooms" hardware and "Zoom Phone" offerings contributed incremental growth. 2. Profitability: Net income for the same period was $1.1 billion, though margins dipped slightly due to higher customer support and R&D costs. Free cash flow exceeded $1 billion, a testament to its capital-light model. 3. Market Cap: At its peak in early 2023, Zoom’s market capitalization reached $35 billion, but by year-end, it settled around $20–$22 billion amid broader tech sell-offs. These figures are publicly audited and non-negotiable. What’s less clear is whether Zoom’s 2023 net worth—when viewed through the lens of private market multiples—accurately reflects its long-term potential. The company’s decision to forgo an IPO-like hype cycle (it went public in 2019 at a $10 billion valuation) meant its valuation was always tied to fundamentals, not speculation.What the Estimates Suggest
Industry estimates for Zoom’s 2023 net worth vary widely, depending on whether analysts focus on enterprise valuation metrics or public market multiples. Private equity benchmarks suggest Zoom could be worth $25–$30 billion if traded at a 10x–12x revenue multiple—comparable to other SaaS leaders like Slack (acquired by Salesforce for $27.7 billion in 2021). However, public market discipline kept its stock price depressed, with shares trading at a lower P/E ratio than historical averages. Speculative scenarios—often cited in earnings call transcripts—propose that Zoom’s true value lies in its network effects and switching costs. With over 300 million monthly active participants (as of 2023), the company’s moat is less about technology and more about user inertia. Yet estimates around Zoom net worth 2023 must account for competitive threats: Microsoft Teams’ integration with Office 365 and Google Meet’s free-tier dominance. Some analysts argue Zoom’s valuation should reflect its defensive positioning in a hybrid work era, while others warn of stagnation if it fails to innovate beyond video calls.
Case Study: A Closer Look
Zoom’s 2023 pivot toward enterprise services—particularly its push into Zoom Phone and AI-driven meeting enhancements—served as a litmus test for its ability to evolve beyond its pandemic-driven growth. The company’s acquisition of Kitewheel (a customer experience platform) for an undisclosed sum (reportedly in the $100–$150 million range) signaled a strategic bet on deepening its hold on corporate clients. While the deal didn’t move the needle on Zoom net worth 2023 in absolute terms, it underscored a shift from user acquisition to revenue per user maximization. The move also highlighted Zoom’s risk tolerance: investing in unproven adjacencies while maintaining its core product’s dominance. Critics argued the acquisition was a distraction, but Zoom’s leadership framed it as a necessary step to future-proof its platform. The company’s decision to delay major layoffs—unlike rivals such as Cisco and Slack—further reinforced its focus on retention over cost-cutting."Zoom’s challenge isn’t growth; it’s proving it can grow profitably without sacrificing its ecosystem." — Mary Meeker (former Morgan Stanley analyst)
| Factor | Estimated Impact on 2023 Net Worth |
|---|---|
| Enterprise Contract Renewals | +$1–1.5B (high retention rates offset price increases) |
| Zoom Phone Adoption | +$300M–$500M (incremental revenue from unified comms) |
| Public Market Valuation Discount | -$5–$7B (stock underperformance vs. private benchmarks) |
| AI/Automation Investments | Neutral (R&D costs offset by potential upsell opportunities) |
| Competitive Pressure (Teams/Meet) | -$1–2B (potential share loss in SMB segment) |
What This Means Going Forward
Zoom’s 2023 net worth trajectory sets the stage for a 2024 where profitability will trump growth metrics. The company’s ability to convert free-tier users to paid plans—a strategy it emphasized in Q4 2023 earnings—will determine whether its valuation recovers. Analysts suggest that if Zoom can increase its average revenue per user (ARPU) by 10–15%, its market cap could rebound to $25 billion+ within 18 months. The bigger question is whether Zoom can redefine its product beyond video calls. Its foray into AI-powered meeting summaries and virtual event hosting (via Zoom Events) may be too little, too late—unless executed flawlessly. The Zoom net worth 2023 story, then, is less about the numbers and more about whether the company can replicate its pandemic-era dominance in a post-hybrid world.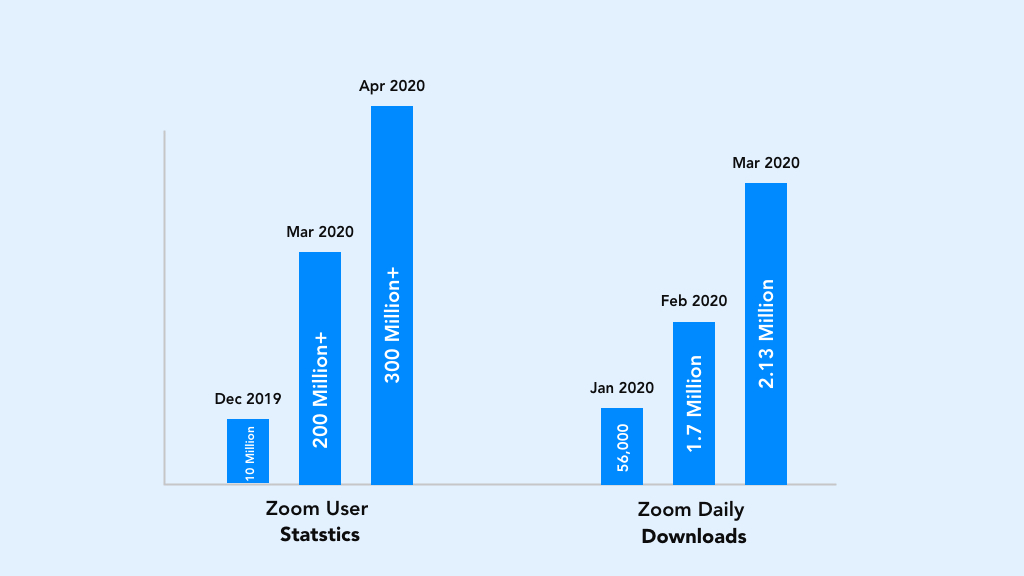
Conclusion
Zoom’s 2023 net worth is a study in contrasts: a company with undeniable revenue strength but a volatile public valuation. Its ability to navigate the shift from emergency remote work to strategic enterprise adoption will dictate whether it’s remembered as a pandemic beneficiary or a long-term SaaS powerhouse. The data is clear—Zoom’s fundamentals are sound—but the market’s patience is wearing thin. For investors, the takeaway is simple: Zoom’s worth isn’t just in its balance sheet, but in its ability to stay relevant. As hybrid work becomes the norm, the company’s next chapter will hinge on innovation, not just inertia. The Zoom net worth 2023 debate, then, is the prologue to a larger narrative—one where survival depends on more than just a reliable video call.Comprehensive FAQs
Q: How does Zoom’s 2023 net worth compare to its IPO valuation?
Zoom’s IPO in 2019 valued the company at $10 billion. By 2023, its market cap peaked at $35 billion but settled around $20–$22 billion due to broader tech sell-offs. The disparity reflects investor expectations: early hype gave way to a focus on sustainable profitability rather than growth-at-all-costs.
Q: Did Zoom’s stock price accurately reflect its 2023 net worth?
No. Public market valuations often lag private benchmarks, especially for SaaS companies. Zoom’s stock traded at a discount to private multiples, suggesting the market undervalued its network effects and enterprise stickiness. However, this gap narrowed as Zoom demonstrated strong cash flow generation in 2023.
Q: What role did inflation play in Zoom’s 2023 financials?
Inflation pressured Zoom’s operating margins by increasing costs for customer support, data centers, and R&D. While revenue grew, the company prioritized retention over aggressive pricing, leading to a slight dip in profit margins compared to 2022. This cautious approach helped avoid layoffs but tempered investor enthusiasm.
Q: Could Zoom’s net worth have been higher if it had pursued aggressive M&A?
Possibly, but at a risk. Zoom’s 2023 acquisitions (like Kitewheel) were strategic but modest—avoiding the kind of transformative (and expensive) deals that could have boosted its valuation. The company’s leadership favored organic growth over debt-fueled expansion, a conservative play that may have protected its balance sheet but limited upside.
Q: How does Zoom’s 2023 net worth stack up against competitors like Microsoft Teams?
Microsoft Teams operates at a much larger scale but with lower margins due to its bundling with Office 365. Zoom’s 2023 net worth (~$20–$25B) pales in comparison to Microsoft’s $2.5 trillion+ enterprise, but Zoom’s pure-play focus on video conferencing gives it a higher revenue concentration in its core market. Teams’ integration advantage makes direct valuation comparisons difficult.
Q: What’s the biggest risk to Zoom’s net worth in 2024?
The commoditization of video calls. If Zoom fails to differentiate its platform beyond basic functionality—through AI, event hosting, or deeper enterprise integrations—it risks becoming a utility rather than a premium service. Competitors like Google Meet and Cisco Webex are free alternatives, and Microsoft’s ecosystem lock-in could erode Zoom’s switching cost advantage over time.
