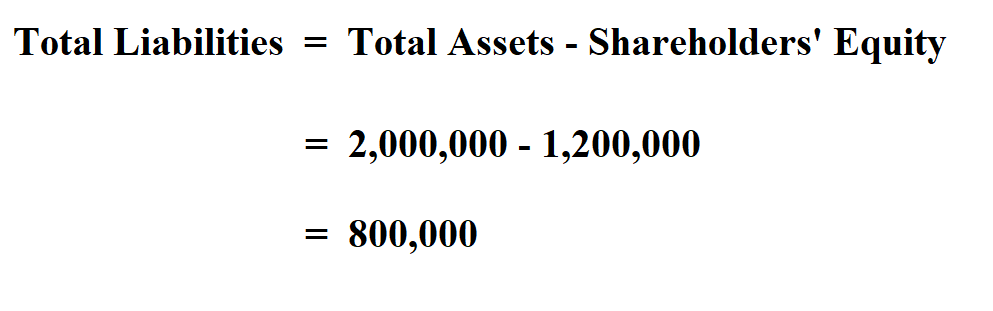
Common Myths About Negative Net Worth
The first myth is that a negative net worth is rare or only affects those who’ve made reckless financial decisions. In reality, life events—medical emergencies, job losses, or economic downturns—can push even disciplined individuals into this territory. For example, a teacher with $800 in savings and $1,500 in student loans might find themselves in this position after an unexpected car repair. The second misconception is that negative net worth is permanent. While it’s true that recovering from it requires strategy, many people bounce back by restructuring debt or increasing income. The third myth, perhaps the most damaging, is that negative net worth means you’re a financial failure. In truth, it’s a data point—not a verdict. Another persistent belief is that creditors will immediately seize assets if net worth turns negative. This isn’t how secured debt works; lenders typically target specific collateral (like a home or car) before going after general assets. Unsecured debt, however, can lead to collections or legal action if left unaddressed. The final myth is that negative net worth is only a problem for individuals. Businesses, too, can find themselves in this position, where liabilities exceed assets on paper—but remain operational through cash flow or future revenue. The key takeaway? Context matters far more than the raw number.Myth 1: Negative net worth means you’re broke
The idea that a negative net worth equates to being destitute ignores the role of liquidity. You could have $750 in cash but owe $1,250 on credit cards or loans—yet still cover essential expenses for months. The term net worth is a snapshot, not a real-time balance. For instance, a freelancer with $500 in a checking account and $1,000 in unpaid invoices might have a negative net worth on paper, but their actual spending power depends on when those invoices are paid. The confusion arises because people equate assets with immediate cash, but assets can include illiquid items like a home or retirement accounts that aren’t easily converted to spending money. Financial advisors often emphasize that net worth is a tool, not a life-or-death metric. If your total liabilities are $1,250 and total assets are $750, your net worth is negative—but your ability to meet obligations depends on cash flow, not just the balance sheet. Someone with a negative net worth could still afford rent, groceries, and debt payments if their income exceeds monthly expenses. The danger lies in assuming the negative figure reflects current solvency, when in fact it’s a lagging indicator of past financial stress.Myth 2: You can’t recover from negative net worth
The assumption that a negative net worth is a dead end overlooks the fact that many people have reversed this situation through targeted strategies. For example, a small business owner with $900 in assets and $1,300 in debt might negotiate lower interest rates, extend payment terms, or secure a short-term loan to bridge the gap. The key is to distinguish between strategic debt (like a mortgage) and toxic debt (high-interest credit cards). If your total liabilities are $1,250 and total assets are $750, the path to recovery often starts with prioritizing secured debts and negotiating with creditors. Recovery also depends on income growth. Someone earning $3,000/month with a negative net worth may struggle less than someone earning $2,000/month. The net worth figure alone doesn’t account for cash flow, which is why some financial experts argue that monthly surplus (income minus expenses) is a more immediate concern than net worth. That said, addressing the root cause—whether it’s overspending, lack of savings, or unexpected expenses—is essential to breaking the cycle.Myth 3: Negative net worth is always your fault
Blame is rarely productive in financial discussions. External factors—medical bills, divorce, natural disasters, or economic recessions—can push anyone into negative territory. Even those with strong financial habits can face setbacks. For instance, a couple with $1,000 in savings and $1,500 in medical debt after a car accident isn’t at fault for the accident itself. The stigma around negative net worth often ignores systemic issues, like predatory lending or wage stagnation, which disproportionately affect certain groups. If your total liabilities are $1,250 and total assets are $750, the question shouldn’t be how did this happen? but how do I stabilize my situation? That said, avoiding preventable mistakes—like maxing out credit cards for non-essentials—can mitigate future risks. The goal isn’t shame but solutions. Many who’ve faced negative net worth credit disciplined budgeting, side income, or debt consolidation as turning points. The focus should be on actionable steps, not recrimination.
What Holds Up to Scrutiny
The core truth is that net worth is calculated as assets minus liabilities, period. If your total liabilities are $1,250 and total assets are $750, the math is straightforward: $750 – $1,250 = –$500. Where the complexity lies is in defining assets and liabilities accurately. For example, a car worth $5,000 but financed with a $4,000 loan contributes only $1,000 to net worth (asset value minus loan balance). Similarly, a retirement account counts as an asset, but its liquidity varies. The challenge isn’t the formula but the precision of the inputs. What’s often overlooked is that net worth is a relative measure. A negative net worth might be sustainable for a young professional with growing income but unsustainable for someone near retirement. Context—age, income, debt type, and financial goals—shapes the interpretation. For instance, a student with $2,000 in assets and $3,000 in student loans has a negative net worth, but their long-term earning potential may offset this in years. The same figure for a retiree with fixed income is far more alarming."Net worth is a temperature gauge, not a thermostat. It tells you where you are, not where you’re going—but ignoring it is like driving with your eyes closed." — Harvey Mackay, business author and speaker
| Common Belief | What the Evidence Says |
|---|---|
| Negative net worth means you’re insolvent. | Insolvency requires inability to pay debts as they come due, not just a negative balance sheet. |
| You must pay off all debts to improve net worth. | Prioritizing high-interest debt or negotiating terms often yields faster improvements. |
| Assets must be liquid to count. | Illiquid assets (e.g., a home) still contribute to net worth, though their value may fluctuate. |
| Negative net worth is a permanent state. | Many recover by increasing assets (savings, investments) or reducing liabilities (debt payoff, refinancing). |
Why the Confusion Persists
The primary reason for misunderstanding lies in how net worth is taught—or not taught. Many financial literacy programs focus on saving rates or credit scores, leaving net worth as an afterthought. Even those who track it often misclassify items: counting a financed car’s full value as an asset, for example, inflates net worth artificially. Additionally, cultural taboos around discussing debt or financial struggles discourage open conversations about negative net worth. If your total liabilities are $1,250 and total assets are $750, admitting this publicly can feel like failure, even though it’s a common phase in many financial journeys. Another factor is the lack of standardized reporting. Unlike credit scores, which are widely understood, net worth lacks a universal framework. Some include future income potential, while others stick to hard assets and debts. This ambiguity leads to inconsistent advice, from "ignore it until you’re positive" to "declare bankruptcy immediately." The truth is nuanced: negative net worth is a signal, not an emergency—unless it’s accompanied by unmanageable cash flow or legal threats.
Conclusion
The answer to if your total liabilities are $1,250 and total assets are $750, what is your net worth? is simple: –$500. The challenge is what to do with that number. It’s neither a death sentence nor a cause for celebration—it’s a call to assess your financial strategy. The first step is accuracy: audit your assets and liabilities to ensure the figures are current. A car appraisal might reveal your vehicle is worth less than you think, or an old credit card debt could have been discharged. Small adjustments can sometimes bridge the gap. Beyond the numbers, the real work lies in aligning your financial habits with your goals. If your negative net worth stems from high-interest debt, consolidation or balance transfer offers might help. If it’s due to insufficient savings, even small monthly contributions to an emergency fund can rebuild a cushion. The key is progress, not perfection. Many who’ve faced this scenario credit their recovery to a single pivot—whether it’s a side hustle, a budget overhaul, or a conversation with a financial advisor. The negative net worth isn’t the end; it’s the first chapter of a rewrite.Comprehensive FAQs
Q: Can I still qualify for loans with a negative net worth?
It depends on the lender and loan type. Secured loans (e.g., mortgages) focus on collateral, while unsecured loans (e.g., personal loans) may require proof of income and debt-to-income ratio. Some lenders ignore net worth if your cash flow covers payments. Always check with the specific institution.
Q: Does negative net worth affect my credit score?
Not directly—but unpaid debts or collections tied to your liabilities will harm your score. Net worth is a balance-sheet concept; credit scores track payment history, utilization, and other factors. Addressing delinquent accounts is critical to protecting your credit.
Q: Should I sell assets to improve my net worth?
Only if the asset isn’t essential and the proceeds will reduce liabilities. For example, selling a car to pay off a loan improves net worth, but selling a home for a down payment might not be wise if you need stable housing. Weigh liquidity needs against long-term stability.
Q: How often should I calculate my net worth?
Quarterly is ideal, especially if your financial situation is volatile. For those with stable income and few liabilities, annually may suffice. The goal is to spot trends—like rising debt or growing assets—before they become crises.
Q: Can I have a negative net worth and still invest?
Yes, but prioritize low-risk, high-liquidity options (e.g., index funds, CDs) over speculative investments. The priority should be stabilizing your finances before aggressive growth strategies. Some advisors recommend waiting until net worth turns positive before heavy investing.
Q: Will negative net worth prevent me from renting an apartment?
Landlords typically check credit scores and income, not net worth. If your rent-to-income ratio is reasonable (e.g., ≤30%) and you have no eviction history, negative net worth alone shouldn’t disqualify you. Some landlords may ask for a larger deposit, though.
Q: Does negative net worth mean I can’t build wealth?
Absolutely not. Many wealthy individuals started with negative net worth. The focus should be on increasing assets (savings, investments, skills) and reducing liabilities (debt payoff, refinancing). Time, discipline, and smart decisions matter more than the starting point.
Q: How do I explain negative net worth to a lender or landlord?
Be honest but strategic. Frame it as a temporary phase due to specific circumstances (e.g., medical bills, career transition) and highlight your plan to improve it. Providing documentation (budget, debt repayment schedule) can build trust. Avoid vague excuses—transparency reduces perceived risk.
