
7 Things Worth Knowing About Will Your Total Assets Be the Same as Your Total Liabilities and Net Worth
At first glance, the relationship between assets, liabilities, and net worth seems straightforward: subtract what you owe from what you own, and you’re left with your net worth. But the reality is far more nuanced. The seven insights below dismantle the myth that these figures are interchangeable—and explain why their interplay defines financial strategy.1. Net Worth Is the Difference, Not the Sum
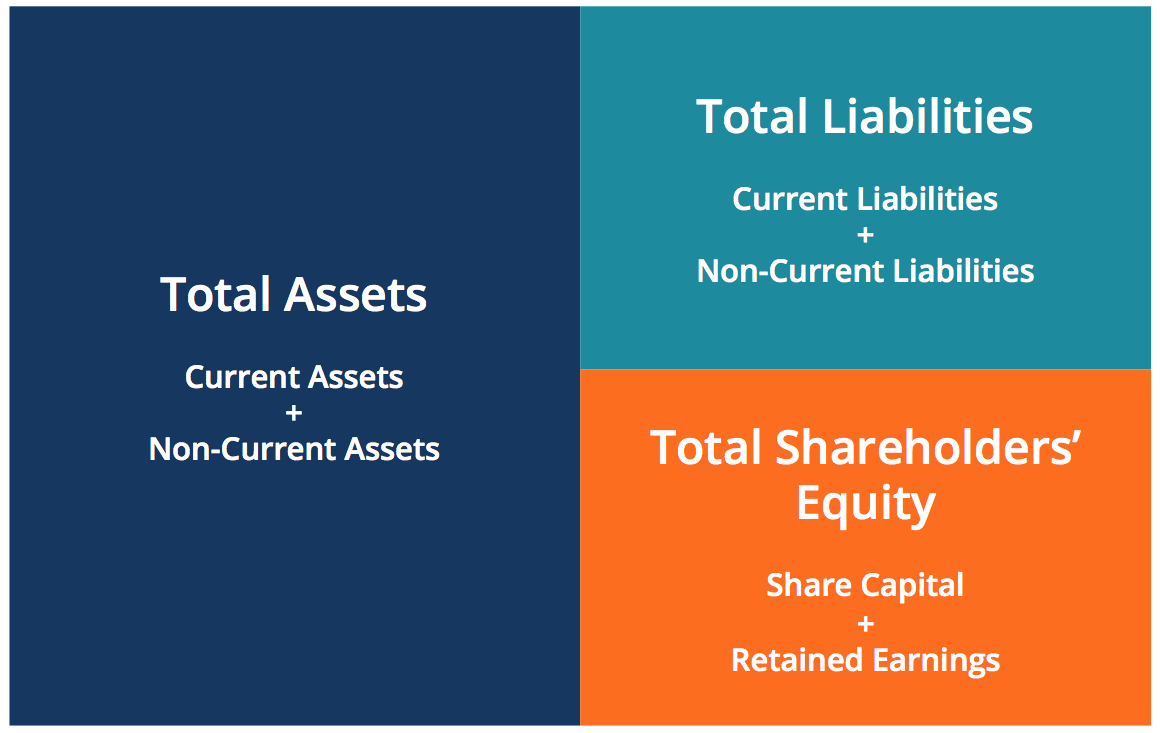
The core confusion stems from a fundamental misreading of the accounting identity: Assets = Liabilities + Net Worth. This isn’t a suggestion; it’s a mathematical truth embedded in double-entry bookkeeping. When someone asks whether their total assets will equal their total liabilities plus net worth, the answer is always yes—but only if you rearrange the equation correctly. The mistake lies in assuming net worth is an independent variable. It’s not. It’s the byproduct of the other two. Consider a freelancer with $150,000 in savings, a $100,000 mortgage, and $50,000 in client receivables. Their total assets (cash + receivables) sum to $200,000, while their liabilities are $100,000. The net worth—$100,000—emerges only after subtracting liabilities from assets. The question "Will your total assets be the same as your total liabilities and net worth?" thus becomes a test of whether you recognize net worth as a derived value, not a standalone figure.2. Liabilities Can Be Both a Burden and a Lever
Not all debt is created equal, and this distinction is critical when evaluating whether assets and liabilities will ever align in a meaningful way. A high-interest credit card balance is a liability that drags net worth down, while a low-interest mortgage might actually increase it over time—if the property appreciates. The key lies in opportunity cost: a liability that funds an asset (like a business loan for equipment) can, in theory, generate returns that offset its cost. For example, a small business owner might have $300,000 in assets but $250,000 in debt—yielding a $50,000 net worth. Yet if that debt finances inventory or machinery generating $100,000 in annual revenue, the liability isn’t just a subtraction; it’s an investment. The question "Will your total assets be the same as your total liabilities and net worth?" then becomes irrelevant, because the focus shifts to cash flow and return on investment, not static balance sheet numbers.3. Inflation and Time Distort the Equation
A net worth statement frozen in time is a snapshot, not a strategy. Inflation, market cycles, and even personal spending habits ensure that the relationship between assets and liabilities evolves. A $200,000 home purchased in 2010 might now be worth $400,000, but if the mortgage balance remains at $150,000, the net worth has grown—not because of new savings, but because the asset appreciated. Conversely, a student loan taken out at 6% interest in 2005 might now feel like an anchor, even if the principal hasn’t changed. This dynamic explains why the answer to "Will your total assets be the same as your total liabilities and net worth?" depends entirely on the time frame. Over a decade, a homeowner’s equity (net worth) might swell as the property value rises, even if the mortgage balance ticks downward slowly. The equation isn’t static; it’s a living calculation where time is the silent variable.4. Hidden Assets and Off-Balance-Sheet Liabilities Exist
Not everything valuable shows up on a traditional balance sheet. Human capital—skills, reputation, or professional networks—isn’t quantified in dollar terms, yet it can be the most liquid asset of all. Similarly, off-balance-sheet liabilities, like unrecorded legal obligations or informal loans, can skew the perception of net worth. A freelancer might list $80,000 in savings but owe $20,000 to a partner for unpaid consulting—creating a net worth of $60,000 that doesn’t account for the intangible value of their expertise. This discrepancy is why the question "Will your total assets be the same as your total liabilities and net worth?" often yields different answers depending on what’s included. A comprehensive financial picture requires acknowledging both tangible and intangible components, as well as obligations that might not appear in formal statements.5. Net Worth Doesn’t Measure Liquidity
A high net worth doesn’t guarantee access to cash. A retiree might own a $1 million home with no mortgage, but if selling it would trigger capital gains taxes or require a lengthy sale process, that asset isn’t liquid. Meanwhile, their emergency fund might be depleted, leaving them with a net worth that doesn’t translate to immediate financial security. The question "Will your total assets be the same as your total liabilities and net worth?" ignores this critical gap: liquidity is a function of time, not just numbers. This is why ultra-high-net-worth individuals often maintain separate liquidity buffers—even if their balance sheets suggest otherwise. A net worth of $5 million might look robust, but if $4 million is tied up in illiquid assets like art or private equity, the real financial flexibility is far lower. The equation only tells part of the story.6. Behavioral Biases Skew Perceptions of the Equation
People tend to overvalue assets they own and undervalue liabilities they’ve taken on. This endowment effect leads to cognitive dissonance when evaluating net worth. A homeowner might fixate on their property’s appreciated value while downplaying the mortgage’s true cost, creating a distorted view of their financial health. Similarly, investors often focus on portfolio gains while ignoring the opportunity cost of debt used to finance those investments. This psychological gap explains why the answer to "Will your total assets be the same as your total liabilities and net worth?" varies so widely among individuals. A real estate investor might see their portfolio as an asset, while a lender views the same property as collateral—a liability in disguise. The perception of the equation is as important as the numbers themselves."Net worth is a lagging indicator, not a leading one. It tells you where you’ve been, not where you’re going." — Carolyn McClanahan, MD, CFP, and author of Practical Finance for Your Life
7. The Zero Net Worth Paradox
A net worth of zero isn’t financial failure—it’s a starting point. Someone with $100,000 in assets and $100,000 in liabilities has a net worth of zero, but their position could be far more strategic than someone with $50,000 in cash and no debt. The first person might own a rental property generating $12,000 annually, while the second has no income streams. The question "Will your total assets be the same as your total liabilities and net worth?" misses the point entirely when applied to this scenario. Zero net worth can signal leverage at work. A young professional with student loans and a starter home might have a net worth of zero, but if their income covers living expenses and debt payments, they’re in a stronger position than someone with no debt but no assets either. The equation’s balance isn’t the goal; cash flow and growth potential are.
How These Facts Connect
The seven insights above reveal that the question "Will your total assets be the same as your total liabilities and net worth?" is less about arithmetic and more about context. Net worth isn’t an endpoint; it’s a snapshot of a larger financial ecosystem where assets and liabilities interact dynamically. The traditional balance sheet treats net worth as a residual, but in practice, it’s a tool for assessing risk, opportunity, and long-term strategy. What these facts expose is that financial health isn’t determined by a single number. A high net worth might mask illiquidity, while a zero net worth could hide untapped potential. The real value lies in understanding how liabilities can be structured to enhance assets, how inflation alters perceptions of wealth, and why behavioral biases lead people to misjudge their own financial positions. The answer to the original question isn’t a yes or no—it’s a framework for better decision-making.| Key Insight | What It Reveals | Strategic Implications |
|---|---|---|
| Net worth is derived, not independent | Assets – Liabilities = Net Worth | Focus on optimizing the equation, not chasing static targets |
| Liabilities can be levers | Debt used for income-generating assets may not reduce net worth long-term | Evaluate debt in terms of ROI, not just principal |
| Inflation distorts time-based comparisons | A fixed asset may gain value while liabilities remain constant | Adjust for inflation when setting financial goals |
Conclusion
The question "Will your total assets be the same as your total liabilities and net worth?" is less about solving for an unknown and more about reframing how you think about wealth. The answer isn’t a simple equation—it’s an invitation to consider the fluidity of financial positions. Assets and liabilities are in constant motion, shaped by market forces, personal choices, and even psychological biases. Net worth, then, isn’t just a number; it’s a reflection of how well you’ve navigated that motion. For most people, the goal shouldn’t be to make the two sides of the ledger equal in a static sense. Instead, the focus should be on structuring liabilities to amplify assets, ensuring liquidity when needed, and recognizing that net worth is just one metric among many. The real question isn’t whether the sums will align—but whether the alignment serves your long-term objectives.Comprehensive FAQs
Q: If assets equal liabilities plus net worth, why does it feel like my net worth is separate?
The confusion arises because net worth is often treated as a standalone metric in personal finance discussions, when in reality it’s the result of the assets-liabilities relationship. Think of it like a seesaw: if you add weight to one side (liabilities), the other side (net worth) must adjust accordingly. The perception of separation comes from focusing on net worth in isolation, rather than as part of the dynamic equation.
Q: Can my net worth ever be negative?
Yes. If your total liabilities exceed your total assets, your net worth becomes negative. This isn’t uncommon for businesses, startups, or individuals with high levels of debt relative to assets. For example, a small business with $50,000 in equipment (assets) but $70,000 in loans (liabilities) has a net worth of -$20,000. While this may seem alarming, it’s not necessarily a crisis—it depends on whether the business generates enough revenue to service the debt.
Q: Does a high net worth always mean financial security?
No. Net worth is a measure of wealth, not liquidity or income stability. Someone could have a net worth of $2 million tied up in a single property, but if they can’t sell it quickly or access the funds easily, they might still face financial strain. Conversely, a lower net worth with diversified, liquid assets could provide more security. The question "Will your total assets be the same as your total liabilities and net worth?" ignores this critical distinction.
Q: How often should I review my net worth to ensure the equation stays balanced?
At least annually, or whenever major life events occur—such as buying a home, taking on significant debt, or receiving a large inheritance. Quarterly reviews are ideal for those with volatile income or investments. The key is to track changes in both assets and liabilities, not just the net worth figure. This ensures you’re not caught off guard by shifts in the underlying equation.
Q: Can I artificially inflate my net worth by taking on more debt?
Technically, yes—but it’s a risky strategy. If you take out a loan to buy an asset (like a rental property), your net worth might increase if the asset appreciates. However, this assumes the asset generates enough income to cover the debt’s cost. If it doesn’t, you’re left with higher liabilities and stagnant or declining assets. The answer to "Will your total assets be the same as your total liabilities and net worth?" in this case depends on whether the debt is productive or speculative.
Q: What’s the difference between net worth and cash flow?
Net worth is a snapshot of your financial position at a given time, calculated by subtracting liabilities from assets. Cash flow, on the other hand, is a measure of movement—the difference between income and expenses over a period. Someone could have a high net worth but poor cash flow (e.g., relying on asset sales to cover living costs), while another might have a modest net worth but strong cash flow (e.g., steady income with controlled spending). The two are related but not interchangeable.
Q: Should I aim for a net worth that matches my age?
While the "net worth by age" rule of thumb (e.g., half your age in net worth by 30) is a useful benchmark, it’s not a strict target. Factors like salary, cost of living, and financial goals vary widely. More important than hitting a specific number is ensuring your assets and liabilities are aligned with your long-term objectives. The question "Will your total assets be the same as your total liabilities and net worth?" is less relevant than whether your financial structure supports your lifestyle and aspirations.
