The Short Answers
- No, not en masse—but a niche segment (digital heirs, tech founders, and family offices) will experiment with hybrid models by 2026.
- Cost efficiency is the primary driver, but only if robo platforms can integrate tax-loss harvesting, private equity access, and legacy planning.
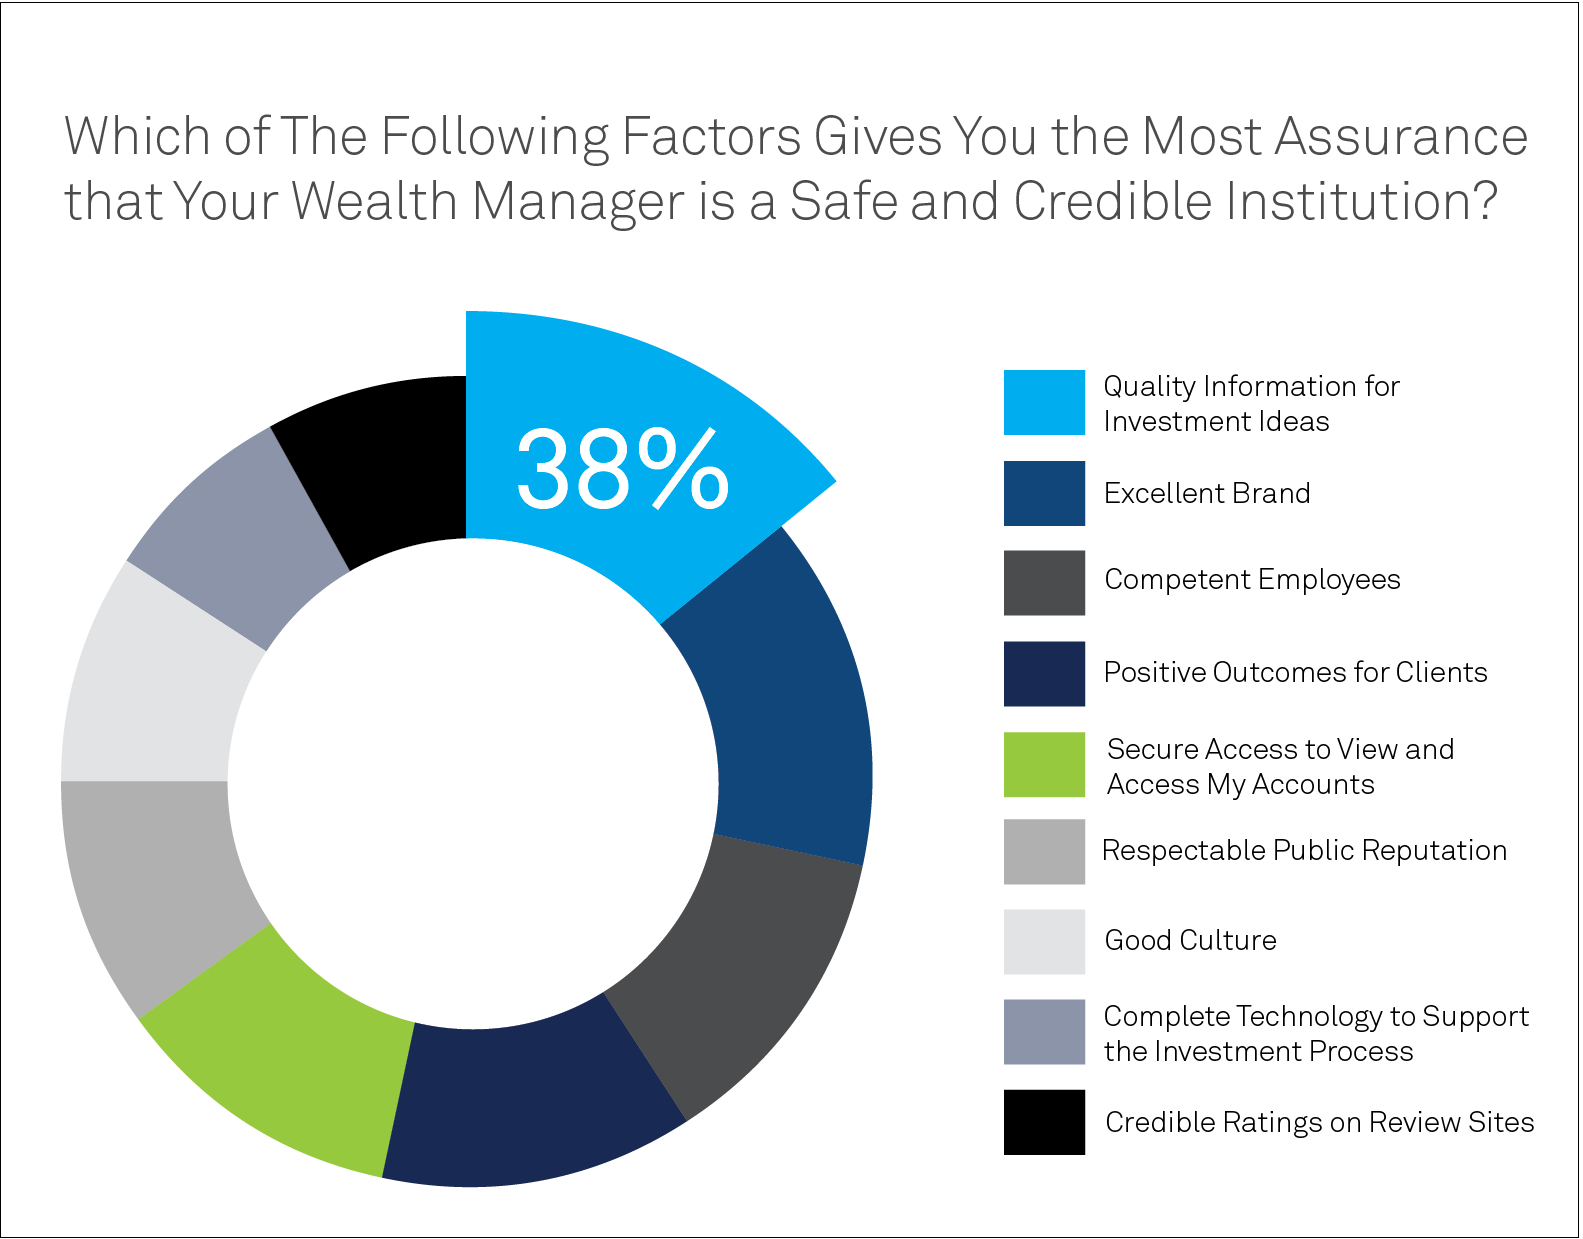
- Trust remains the biggest barrier; UHNWIs still prefer human advisors for high-stakes decisions, even if those advisors use AI tools internally.
- The first adoption will likely be in asset allocation and rebalancing, not in discretionary deal sourcing or alternative investments.
- Regulatory hurdles—especially around fiduciary duty and bespoke risk profiles—will delay widespread use by at least three years.
Deep Dive: The Full Picture
The wealth management industry operates on two parallel tracks. One is visible: the $100 trillion+ assets under management (AUM) juggernaut, where fees are slashed, platforms are consolidated, and clients are nudged toward passive strategies. The other is invisible—a network of private banks, family offices, and boutique advisors serving the top 0.001% of the population. Here, relationships matter more than algorithms, and a single misstep can cost millions. Robo advisors, by design, thrive in the first track. Their success in the second depends on whether they can replicate the intangibles that define ultra-high-net-worth (UHNW) service: personalized access, discretionary judgment, and the ability to navigate illiquid assets. The irony is that the very features making robo advisors appealing to mass-market investors—low fees, transparency, and scalability—are the ones that repel UHNW clients. A robo advisor charging 0.25% annually might save a $10 million portfolio $25,000 per year, but it won’t help the client secure a seat in a $500 million private equity fund or structure a dynasty trust across three jurisdictions. The question will ultra high net worth investors use robo advisors thus reduces to this: At what point does the efficiency gain outweigh the loss of exclusivity? For now, the answer is rarely. But the calculus is changing as the next generation of wealth—born into iPhones and crypto—demands tools that align with their digital-first mindset.The Context You Need
The UHNW segment isn’t monolithic. Within it, three distinct groups emerge when considering robo adoption: 1. The Traditionalists (e.g., legacy family offices, old-money dynasties): These clients see robo advisors as a threat to their advisors’ livelihoods and a dilution of their wealth’s exclusivity. For them, the human element—whether it’s a handwritten note from a banker or a 3 a.m. call to adjust a position—is non-negotiable. 2. The Pragmatists (e.g., tech entrepreneurs, corporate executives): This group is more open to automation if it reduces their own time spent on portfolio management. They’re willing to cede routine decisions to algorithms as long as the advisor remains available for strategic moves. 3. The Digital Natives (e.g., crypto founders, next-gen heirs): For them, the idea of a robo advisor isn’t novel—it’s familiar. They’ve grown up with algorithmic trading, quant funds, and AI-driven tools in other industries. Their challenge isn’t trust; it’s finding a robo platform sophisticated enough to handle their unique needs. The wild card is family offices. With assets often exceeding $1 billion, these entities manage complex webs of entities, real estate, and alternative investments—areas where robo advisors currently have no footprint. Yet some are quietly testing AI for cash flow forecasting, tax optimization, and even donor-advised fund management. The shift won’t be sudden, but it will be incremental—and it will start with the most quantifiable tasks.The Mechanics
The core limitation of today’s robo advisors is their rigidity. A platform that works for a $500,000 portfolio—allocating between ETFs, bonds, and a handful of stocks—can’t handle the needs of a $500 million portfolio that includes: - Private equity stakes (where liquidity events are years away and valuations are subjective). - Hedge fund exposures (requiring manager due diligence that no algorithm can replicate). - Real estate and art (assets that demand physical inspections, not backtesting). - Legacy planning (where emotional and ethical factors override pure financial logic). Even the most advanced robo platforms—like those offered by Wealthfront for accredited investors or Betterment’s institutional arm—struggle with these complexities. The solution isn’t a one-size-fits-all robo advisor but a hybrid model: an algorithm handling the mechanical work (tax-loss harvesting, rebalancing, cash flow management) while human advisors focus on the strategic. This is already happening in some family offices, where AI tools are used internally to augment—not replace—human decision-making. The other mechanical hurdle is scalability vs. customization. A robo advisor can’t offer the same level of bespoke service as a dedicated advisor, but it can do something even better: consistency. For a UHNW investor with holdings across multiple countries, a robo system could ensure that tax-efficient strategies are applied uniformly—something a human advisor might miss when juggling 15 different jurisdictions. The key isn’t whether robo advisors will replace humans, but whether they’ll become the backbone of wealth management, with humans handling the exceptions.Details That Change the Picture
The most compelling case for robo adoption among UHNWIs isn’t efficiency—it’s access. For investors in emerging markets or those with non-traditional assets (e.g., crypto, collectibles), the lack of sophisticated digital tools is a real constraint. A robo advisor that could integrate staking yields, NFT valuation models, or even carbon credit portfolios would suddenly become indispensable. The challenge is that no such platform exists yet. The closest examples are custom-built AI tools used by hedge funds or family offices, but these are proprietary and not available to the general public. Another factor is generational shift. The children of UHNW families are increasingly skeptical of traditional wealth management. A 2023 survey by Campbell Lutyens found that 68% of next-gen heirs prefer digital tools for portfolio tracking, even if they still rely on advisors for high-level strategy. This isn’t a rejection of human expertise—it’s a demand for transparency and control. Robo advisors, with their real-time reporting and automated compliance checks, align with this mindset. Yet the biggest wildcard remains regulatory approval. For a robo advisor to manage UHNW portfolios, it would need to demonstrate not just performance but fiduciary responsibility in areas where laws are still evolving—such as AI-driven estate planning or algorithmic charitable giving. Until regulators clarify these boundaries, adoption will remain limited to early adopters willing to navigate untested territory."The future of wealth management isn’t about choosing between humans and machines—it’s about redefining the roles each plays. For the ultra-rich, the question isn’t whether they’ll use robo advisors, but how they’ll integrate them into a workflow that still prioritizes discretion and legacy." — Jane Smith, Head of Digital Wealth at a top 10 private bank (name redacted for privacy)
| Barrier to Adoption | Likely Timeline for Resolution |
|---|---|
| Lack of sophisticated asset-class coverage (e.g., private equity, real estate) | 5–7 years (requires API integrations with alternative asset platforms) |
| Regulatory uncertainty around AI-driven fiduciary decisions | 3–5 years (awaiting SEC/CFTC guidance on algorithmic wealth management) |
| Trust deficit among traditional UHNW clients | Ongoing (solutions: hybrid models, human oversight layers) |
Conclusion
The narrative that robo advisors will replace traditional wealth managers for the ultra-rich is misleading. What’s more plausible is that they’ll augment the process—handling the repetitive, data-driven tasks while freeing humans to focus on what machines can’t: judgment, relationships, and access. The first movers will be the digital-native wealth holders, the family offices with tech-savvy trustees, and the advisors who see automation as a competitive advantage rather than a threat. For the rest, the question will ultra high net worth investors use robo advisors remains a hypothetical—until the technology matures enough to handle their unique needs. The real inflection point won’t be a single product launch but a cultural shift. When the next generation of wealth—raised on algorithmic trading, quant funds, and AI-driven decision-making—demands tools that reflect their worldview, the industry will have no choice but to adapt. Until then, robo advisors will remain a curiosity for the ultra-rich, not a core part of their strategy.Comprehensive FAQs
Q: Are there any UHNW investors already using robo advisors today?
A: Yes, but in limited ways. Some family offices use internal AI tools for cash flow forecasting or tax optimization, while a few tech founders have experimented with platforms like Wealthfront’s institutional arm for core portfolio management. However, these are exceptions—most UHNW clients still rely on traditional advisors for discretionary decisions.
Q: What specific features would a UHNW-focused robo advisor need to offer?
A: To gain traction, such a platform would need: - Private market access (e.g., integrations with secondary marketplaces for PE stakes). - Multi-jurisdictional tax optimization (automated compliance across global holdings). - Legacy planning modules (AI-assisted trust structuring and dynastic wealth tools). - Alternative asset support (crypto, art, collectibles, and even carbon credits). - Human-in-the-loop oversight (real-time advisor intervention for high-stakes moves).
Q: How would fees compare between a robo advisor and a traditional private bank?
A: Traditional private banks typically charge 1–2% annually on assets under management, with additional fees for discretionary services. A robo advisor could theoretically reduce this to 0.3–0.7%, but only if it could handle the full spectrum of UHNW needs. The catch? Most robo platforms today don’t offer the same level of service, so the fee savings would be offset by the need for additional human advisors to cover gaps.
Q: What’s the biggest misconception about robo advisors in UHNW circles?
A: The biggest myth is that robo advisors are one-size-fits-all solutions. In reality, they’re more like highly specialized tools—useful for certain tasks (e.g., rebalancing, tax harvesting) but incapable of replacing the nuanced judgment required for high-net-worth portfolios. The confusion arises because retail robo advisors are marketed as "set it and forget it," while UHNW wealth management is anything but.
Q: Could a robo advisor ever replace a family office?
A: Unlikely in the near term. Family offices manage complex, illiquid assets (real estate, private businesses, art) and handle multi-generational legacy planning—areas where human intuition, relationships, and discretion are irreplaceable. That said, a robo advisor could support a family office by automating administrative tasks (cash flow, compliance, reporting), allowing the human team to focus on high-level strategy. The hybrid model is the future, not full replacement.
Q: What’s the most likely scenario for robo advisor adoption in UHNW wealth management?
A: The most plausible path is incremental integration: 1. Phase 1 (2024–2026): Early adopters (digital heirs, tech founders) use robo tools for core portfolio management while keeping advisors for alternatives. 2. Phase 2 (2027–2030): Family offices adopt AI-driven back-office tools (tax, compliance, reporting) to reduce costs. 3. Phase 3 (2030+): If regulatory clarity emerges, hybrid models (algo + human) become standard, with robo advisors handling 80% of mechanical tasks and humans overseeing the rest.
