The Short Answers
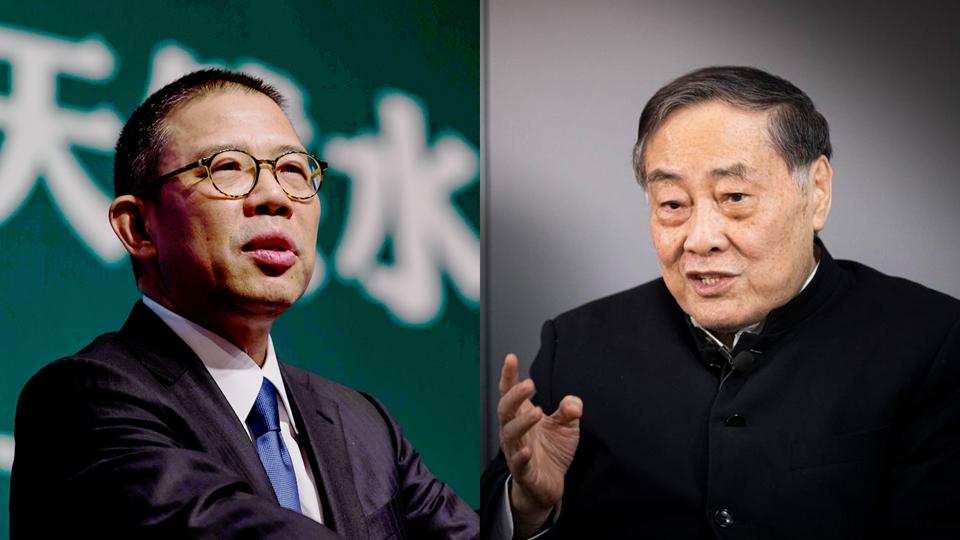
- The richest person in China as of 2024 is Zhong Shanshan, with a net worth estimated around $60 billion, primarily from Nongfu Spring and pharmaceutical ventures.
- His wealth strategy revolves around diversification—avoiding over-reliance on any single sector (e.g., property or tech) while leveraging China’s healthcare and consumer trends.
- Unlike earlier billionaires (e.g., Wang Jianlin or Ma Huateng), Zhong’s rise reflects a post-regulatory era where state tolerance is earned through subtlety and social contribution.
- Critics argue his fortune is underreported due to offshore structures and indirect holdings, making precise valuations difficult.
Deep Dive: The Full Picture
Zhong Shanshan’s empire is a study in asymmetric growth. While Western observers fixate on China’s tech wars or property crises, his companies—Nongfu Spring, Watsons Holdings (pharmacies), and Trinity (medical supplies)—operate in sectors that align with state priorities. The beverage giant, for instance, markets itself as "China’s answer to Coca-Cola," but its real power lies in localized branding: ads that avoid celebrity endorsements (a risk post-scandals) and instead focus on "pure mountain water," tapping into nationalist sentiment. This isn’t just a business; it’s a cultural rebranding of Chinese consumption.
The mechanics of his wealth are less about flashy innovations and more about operational leverage. Nongfu Spring’s profit margins hover around 15–20%, far healthier than peers, thanks to vertical integration—controlling everything from bottling plants to distribution. His pharmacy chain, Watsons, dominates urban markets by offering subscription-based healthcare services, a model that aligns with China’s aging population and rising medical costs. Even his foray into space tourism (via a joint venture) isn’t about moon shots but about securing early-mover advantage in a sector the government is quietly encouraging.
The Context You Need
Understanding the richest person in China requires grasping two paradoxes. First, wealth in China is never absolute—it’s relative to the state’s whims. Zhong’s fortune ballooned during COVID-19, but only because masks and vaccines were in short supply; had the government stockpiled early, his profits would’ve been capped. Second, diversification isn’t just a strategy—it’s survival. The property crash that toppled figures like Evergrande left Zhong untouched because his assets were in consumer staples and essential services, not leveraged real estate.
The rise of the richest person in China also mirrors broader trends. As tech moguls like Pony Ma face restrictions, consumer-facing and healthcare-related wealth is becoming the new gold standard. Zhong’s ability to pivot—from medical equipment to bottled water to pharmacies—shows how China’s elite hedge against risk. His companies don’t just sell products; they sell resilience.
The Mechanics
The alchemy of Zhong’s wealth lies in three layers:
1. Asset Recycling: His companies frequently spin off subsidiaries into separate entities, then relist them at higher valuations. Nongfu Spring’s Hong Kong IPO in 2018, for example, raised $1.1 billion—part of a pattern where core assets are monetized without diluting control.
2. Regulatory Arbitrage: By operating in non-discretionary sectors (healthcare, beverages), he avoids the scrutiny that dooms tech or gaming firms. Even when state media criticizes "unfair pricing" in his pharmaceutical ventures, the backlash is muted because his products are essential.
3. Global Play: While his base is China, his companies expand via overseas listings and joint ventures. Watsons, for instance, has stores in Singapore and Malaysia, diversifying revenue streams beyond China’s volatile domestic market.
The result? A fortune that appears static but is constantly reinvented. Unlike the fixed assets of a property tycoon, Zhong’s wealth is liquid and adaptable—able to shift with policy winds.
Details That Change the Picture
The richest person in China today is often overshadowed by narratives about tech billionaires or property kings, but his story reveals deeper truths. For one, his wealth is less about innovation and more about execution. Nongfu Spring didn’t invent bottled water; it perfected distribution and trust in a market where counterfeit goods are rampant. His pharmacies don’t sell the latest drugs; they sell accessibility, offering same-day delivery in a system where public hospitals are overburdened.
Another layer is philanthropy as PR. Zhong has donated hundreds of millions to education and disaster relief—moves that soften public perception. In China, wealth without social contribution is seen as extractive; his donations are a calculated hedge against populist backlash. Yet even this is strategic: his charity focuses on STEM education, aligning with state priorities for technological self-sufficiency.
"In China, the richest person isn’t the one with the biggest factory or the fanciest skyscraper. It’s the one who understands that wealth is a conversation with the state—and knows when to listen." — Shanghai-based private equity analyst (2023)
| Key Holding | Role in Wealth |
|---|---|
| Nongfu Spring | Beverage giant; ~$10B revenue annually; dominates rural/urban markets with nationalist branding. |
| Watsons Holdings | Pharmacy chain; 3,000+ stores; pivoted to telemedicine during COVID-19, boosting margins. |
| Trinity Biomed | Medical supplies; profited from pandemic shortages; later diversified into vaccines. |
| Offshore Investments | Estimated 20–30% of net worth held via Hong Kong/overseas entities; exact figures classified. |

Conclusion
The richest person in China today is a case study in controlled ambition. Zhong Shanshan’s fortune isn’t built on disruption but on mastering the art of the possible—expanding where others retreat, diversifying where others specialize. His story reflects a China where state capitalism is the only capitalism, and wealth is measured not just in dollars but in political endurance.
Yet his dominance also raises questions. If the richest person in China can thrive by playing by the state’s rules, what does that say about the system? His rise suggests that true wealth in China isn’t about defying the state—it’s about anticipating its moves. As long as he avoids the pitfalls of overreach, his empire will endure, proving that in China, fortunes are made not by breaking rules, but by knowing which ones to bend.
Comprehensive FAQs
#### Q: How does Zhong Shanshan’s wealth compare to China’s other billionaires?
As of 2024, Zhong surpasses figures like Wang Jianlin (property) and Dong Mingzhu (home appliances), but trails Ma Huateng (Tencent) in peak valuations. His advantage lies in asset diversification—unlike tech or property tycoons, his wealth isn’t tied to a single volatile sector.
####Q: Are there rumors about Zhong’s wealth being underreported?
Yes. Analysts note that offshore holdings (via Hong Kong-listed entities) and indirect stakes in private companies likely inflate his true net worth. Unlike Ma Huateng, who lists Tencent shares openly, Zhong’s assets are opaque by design—a common trait among China’s elite.
####Q: How has China’s regulatory crackdown affected his business?
Unlike tech moguls, Zhong has avoided direct conflicts with regulators. His sectors (healthcare, beverages) are non-discretionary, so even when state media critiques "excessive profits," his operations continue. His strategy: compliance through obscurity—expanding quietly rather than aggressively.
####Q: What’s next for Zhong’s empire?
Industry watchers speculate on three fronts: 1) Global expansion of Nongfu Spring (targeting Southeast Asia); 2) Deepening healthcare tech (AI diagnostics, telemedicine); and 3) Strategic investments in green energy, aligning with China’s carbon-neutral goals.
####Q: Could Zhong’s wealth be at risk from future policies?
Any fortune in China is policy-dependent. His biggest risks are: 1) Anti-monopoly probes (if Nongfu Spring’s market share grows too dominant); 2) Capital controls tightening on offshore transfers; and 3) Shift in state priorities (e.g., if healthcare privatization faces backlash). His resilience lies in having no single point of failure—a lesson from China’s regulatory wars.
