
Breaking Down the Numbers
Jay Cooke’s financial empire was built on numbers—precise, audacious, and ultimately unsustainable. By the early 1870s, his firm had underwritten $200 million in railroad bonds (a staggering figure in an era when the U.S. GDP hovered around $10 billion). These weren’t just loans; they were bets on the future, with Cooke selling bonds to farmers, clerks, and small-town investors who believed in the promise of the transcontinental railroad. The strategy worked—until it didn’t. When Northern Pacific’s construction costs ballooned and Cooke’s firm overextended, the withdrawal of confidence became a panic. Depositors rushed to cash out, and within months, Jay Cooke & Company—once the most powerful financial institution in the country—filed for bankruptcy. The numbers don’t lie: Cooke’s rise was meteoric, his fall precipitous, and the lessons he left behind are still debated in economic circles. The irony of Cooke’s story lies in the scale of his ambition versus the fragility of his model. His firm had $40 million in deposits at its peak, a sum that dwarfed competitors. Yet when Northern Pacific’s stock plummeted, Cooke’s overleveraged position became a liability. The Panic of 1873 wasn’t just Cooke’s failure; it was the collapse of a system that had grown too dependent on speculative growth. Historians still dissect whether Cooke’s downfall was a personal flaw or an inevitable consequence of an unregulated market. What’s clear is that his numbers—once celebrated—became the template for understanding financial contagion.The Verified Baseline
Jay Cooke was born in 1821 in Sandusky, Ohio, into a family of modest means. His father, a carpenter, instilled in him a work ethic that would define his career. Cooke’s early years were spent in Philadelphia, where he apprenticed under bankers and quickly mastered the mechanics of finance. By 1851, he had founded Jay Cooke & Company, initially as a wholesale business before pivoting to securities underwriting. His breakthrough came in 1863, when he secured a $50 million loan for the Union Pacific Railroad—a deal that catapulted his firm into the national spotlight. Cooke’s reputation was built on two pillars: innovative bond sales and an unshakable belief in America’s industrial future. He marketed securities directly to the public, bypassing traditional elite investors, and in doing so, democratized access to capital—albeit with devastating consequences when the market turned. Cooke’s personal life was equally disciplined. He married Mary Elizabeth Garber in 1845, and the couple had seven children. Unlike many of his contemporaries, Cooke avoided the excesses of Gilded Age ostentation; his wealth was reinvested in his firm and philanthropic causes, including education and public works. His downfall in 1873 was swift: after Northern Pacific’s stock crashed, Cooke’s firm could no longer meet withdrawal demands. He fled to Europe to avoid creditors, returning only after the bankruptcy proceedings were concluded. The scandal tarnished his name, but his methods—particularly the use of mass-market bond sales—proved too useful to abandon entirely.What the Estimates Suggest
Industry estimates place Cooke’s personal fortune at $5–10 million at its peak—equivalent to $150–300 million today—a sum that would have made him one of the wealthiest men in America. However, these figures are speculative, as Cooke’s assets were liquidated during bankruptcy proceedings. His firm’s collapse wiped out $100 million in investor funds, a sum that, adjusted for inflation, would exceed $2.5 billion in modern terms. The economic ripple effects were immediate: 18,000 businesses failed in the ensuing depression, and unemployment spiked to 14%. While Cooke’s personal losses were severe, the broader impact on the financial system was seismic, forcing regulators to reconsider leverage and liquidity risks. Speculation also surrounds Cooke’s post-collapse influence. Some historians argue that his techniques were later refined by J.P. Morgan, who avoided Cooke’s fatal flaw—overdependence on a single asset class. Others claim Cooke’s mass-marketing of bonds laid the groundwork for 20th-century investment banking. What’s certain is that his firm’s bankruptcy was the second-largest in U.S. history until the 2008 financial crisis. The estimates may vary, but the consensus is clear: Cooke’s experiment in scaling finance proved that growth without guardrails leads to collapse.
Case Study: A Closer Look
No single decision defines Jay Cooke’s legacy more than his $50 million loan to Northern Pacific Railroad in 1869. The deal was a gamble on America’s westward expansion, and for years, it paid off. Cooke’s firm sold bonds to thousands of small investors, framing the railroad as a patriotic endeavor. The strategy worked—until it didn’t. By 1873, Northern Pacific’s construction costs had spiraled, and Cooke’s firm was left holding $30 million in unsold bonds. When the market soured, panicked investors demanded withdrawals, and Cooke’s liquidity crisis became a full-blown run on the bank. The Northern Pacific loan wasn’t just a financial miscalculation; it was a systemic failure of confidence. The domino effect was immediate. Banks across the Northeast froze lending, railroads halted construction, and the stock market plunged. Cooke’s attempt to stabilize the situation—by offering $5 million in cash to depositors—only accelerated the panic. Within weeks, his firm was insolvent. The Northern Pacific loan wasn’t just Cooke’s undoing; it exposed the vulnerabilities of a financial system that had grown too interconnected. His case remains a textbook example of how overleveraging a single asset can unravel an entire economy."Cooke’s genius was in selling the future as if it were already here. His tragedy was that the future never arrived in time." — Edward J. Perkins, The Great Gatsby of Finance
| Factor | Estimated Impact |
|---|---|
| Overleveraging on Northern Pacific | Direct cause of $30M in unsold bonds; triggered liquidity crisis. |
| Mass-market bond sales | Increased investor base but amplified panic when confidence faltered. |
| Lack of regulatory oversight | No deposit insurance or capital requirements—exacerbated bank runs. |
| Economic contraction | Panic spread to Europe; 18,000+ U.S. businesses failed within months. |
What This Means Going Forward
Jay Cooke’s story is a warning about the dangers of unchecked financial innovation. His methods—selling complex securities to the masses, betting heavily on a single sector, and assuming growth would continue indefinitely—were replicated in later crises, from the 1929 stock market crash to the 2008 housing bubble. The lesson is clear: when confidence becomes the primary collateral, the system is only as strong as its next supporter. Cooke’s firm’s collapse forced a reckoning with risk, leading to early forms of deposit insurance and capital requirements. Yet his legacy persists in the shadow of every financial boom: the moment when euphoria replaces caution. Today, Cooke’s name is rarely invoked in mainstream finance, but his fingerprints are everywhere. The securitization of assets, the retailization of investing, and the systemic risks of interconnected markets all trace back to his era. His story is a reminder that finance is not just about numbers—it’s about psychology. When who is Jay Cooke is asked in the context of modern crises, the answer isn’t just about the past; it’s a mirror held up to the present.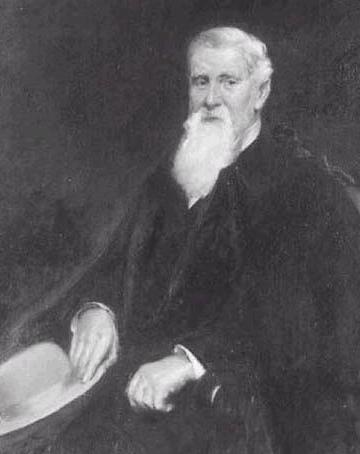
Conclusion
Jay Cooke was a man of his time—a financier who believed in America’s boundless potential and acted accordingly. His rise was a masterclass in scaling ambition, and his fall was a masterclass in the fragility of unchecked optimism. The question of who is Jay Cooke isn’t just about a failed banker; it’s about the birth of modern financial risk and the enduring tension between innovation and stability. His story forces us to confront uncomfortable truths: that confidence can be a currency, that growth often outpaces prudence, and that the greatest empires in finance are built on the thinnest of margins. Cooke’s legacy is a cautionary tale, but it’s also a foundational one. His methods reshaped how capital moves, how risks are calculated, and how markets react to panic. To ignore his story is to risk repeating it. In an era where financial systems are more interconnected than ever, Cooke’s warning remains relevant: the moment you assume the future will always arrive, you’ve already lost.Comprehensive FAQs
Q: Was Jay Cooke’s bankruptcy the sole cause of the Panic of 1873?
A: No. While Cooke’s firm was the largest casualty, the panic was triggered by a confluence of factors: overbuilding of railroads, European financial strains, and speculative excess across multiple sectors. Cooke’s collapse accelerated the crisis but was not its sole cause.
Q: Did Jay Cooke’s methods influence later financial crises?
A: Absolutely. His use of mass-market bond sales and overleveraging on a single asset class foreshadowed later bubbles, including the 1929 stock market crash and the 2008 housing crisis. Regulators today still study Cooke’s failures in designing safeguards.
Q: How did Jay Cooke’s personal life affect his business decisions?
A: Cooke was known for his frugality and discipline, unlike many Gilded Age tycoons. He reinvested profits into his firm and avoided personal extravagance, which may have delayed his recognition of the Northern Pacific’s financial distress. However, his overconfidence in the railroad’s success ultimately blinded him to risks.
Q: Are there any modern financial firms that resemble Jay Cooke & Company?
A: Some argue that regional investment banks or specialized asset managers share Cooke’s profile—particularly those that concentrate risk in a single sector (e.g., tech, real estate). However, modern regulations (like Dodd-Frank) aim to prevent the kind of systemic collapse Cooke’s firm experienced.
Q: What was Jay Cooke’s post-collapse life like?
A: After fleeing to Europe to avoid creditors, Cooke returned to the U.S. in 1876 and spent his remaining years in relative obscurity. He died in 1905 in Philadelphia, having never fully recovered his former status. His reputation endured as a tragic visionary rather than a reckless gambler.
