The Short Answers
- Illiquid assets (e.g., private company stakes, real estate) inflate net worth but don’t translate to spendable cash.
- Debt structure matters—high-leverage liabilities can turn a high net worth into a solvency risk.
- Inflation and market volatility distort the real value of assets over time.
- Human capital (earning potential) and behavioral biases (e.g., overconfidence in asset values) are excluded.
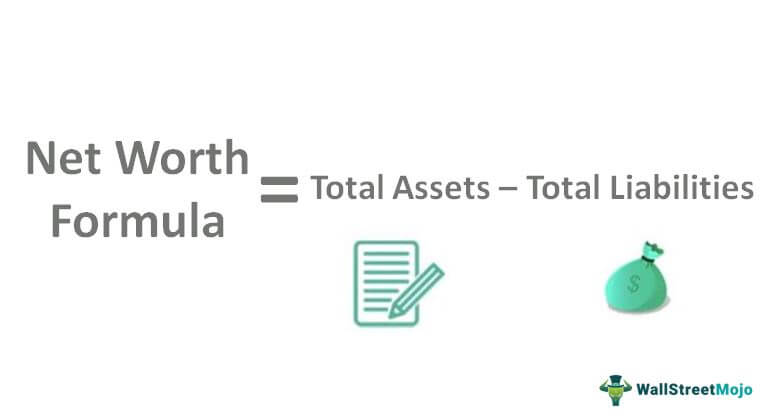
Deep Dive: The Full Picture
The net worth method’s core flaw is its assumption of liquidity equivalence. A balance sheet treats a $10 million private equity stake the same as $10 million in cash, but in practice, selling that stake could take years—and at a discount. For ultra-high-net-worth individuals, up to 70% of their wealth may be tied to illiquid assets, according to Credit Suisse’s Global Wealth Report. This isn’t just a theoretical issue: during the 2008 financial crisis, many wealthy families discovered their paper wealth evaporated when forced to sell assets at fire-sale prices. The method also ignores opportunity cost. A $5 million art collection might be worth $5 million on paper, but if the owner needs to liquidate it to cover a $2 million tax bill, the after-sale proceeds could drop to $3 million due to transaction costs and market timing. Another critical blind spot is debt composition. Net worth calculations treat all debt equally—whether it’s a low-interest mortgage or a high-yield credit card—but the cash-flow impact differs dramatically. A family with a $3 million home and a $2 million mortgage might have a $1 million net worth, yet their monthly obligations could absorb 60% of their income. Conversely, someone with a $1 million net worth but no debt might have far greater financial flexibility. The method fails to capture leverage risk, where borrowed money amplifies volatility. During the dot-com bubble, many entrepreneurs saw their net worth surge as stock options vested, only to plummet when the market corrected—yet the nominal figures never adjusted for risk exposure.The Context You Need
The net worth method’s limitations become glaring in cross-generational comparisons. A 25-year-old with a $1 million net worth—mostly in stocks and a primary residence—may be on track for long-term growth, while a 75-year-old with the same figure could face liquidity constraints if their assets are locked in annuities or illiquid trusts. The method doesn’t account for time horizons: a young professional’s wealth is forward-looking (earning potential), while a retiree’s is backward-looking (asset preservation). This is why financial advisors increasingly use liquidity-adjusted net worth (LANW) for clients over 50, which deducts illiquid assets and adds a buffer for healthcare or long-term care costs. Cultural and regulatory factors also skew the method’s accuracy. In some jurisdictions, offshore accounts or trusts may not be fully disclosed in net worth statements, creating hidden liabilities or unreported assets. Meanwhile, in countries with high inflation (e.g., Argentina, Venezuela), nominal net worth figures can be misleadingly high when adjusted for local currency depreciation. Even in stable economies, tax deferral strategies—like qualified retirement accounts—can inflate reported net worth while restricting access to funds. For example, a $2 million 401(k) might boost net worth, but early withdrawals trigger penalties, effectively reducing liquidity.The Mechanics
At its core, the net worth method is a snapshot, not a movie. It captures a moment in time but ignores the velocity of money. A hedge fund manager with a $100 million net worth might see that figure fluctuate by $50 million in a single quarter due to market swings, yet the underlying cash flow remains stable. Meanwhile, a small business owner with a $5 million net worth could face a cash crunch if receivables are slow to convert. The method also overlooks embedded options: a founder with unvested equity might have a low net worth on paper but high potential upside if the company succeeds. The psychological dimension is equally critical. Anchoring bias leads individuals to fixate on net worth figures without considering volatility. A family might feel secure with a $10 million net worth, only to discover that $8 million is tied to a single property—leaving them vulnerable to a single bad tenant or market shift. Conversely, someone with a modest net worth but diversified, liquid assets (e.g., ETFs, cash) may have greater resilience. The method’s rigidity also ignores behavioral finance: overconfidence in asset valuations, herd mentality in investments, or failure to hedge against black swan events can turn a high net worth into a liability.Details That Change the Picture
The most glaring inefficiency arises when net worth is used for benchmarking across unequal contexts. Comparing a real estate tycoon’s net worth to a tech entrepreneur’s is apples-to-oranges: the former’s wealth is tied to a single asset class with cyclical risks, while the latter’s may be diversified across stocks, options, and intellectual property. Even within the same industry, net worth can be a poor predictor of success. Two private equity partners might both report a $50 million net worth, but one could have $40 million in carried interest (illiquid, performance-dependent) while the other holds $40 million in cash and publicly traded securities—leading to vastly different financial outcomes. Another critical oversight is non-financial liabilities. Net worth calculations typically exclude intangible costs like: - Caregiving obligations (e.g., supporting aging parents). - Legal or reputational risks (e.g., a CEO’s net worth could plummet due to a lawsuit). - Opportunity costs of wealth preservation (e.g., foregoing higher-risk investments to protect a legacy). These factors can erode real financial security without showing up on a balance sheet. For instance, a family with a $30 million net worth might allocate $10 million to a trust for heirs, leaving only $20 million for current needs—a scenario the net worth method doesn’t flag as a risk."Net worth is like a photograph of a storm: it shows the damage after the fact, but tells you nothing about the winds that caused it."
— James Grant, financial historian and author of Money of the Mind
| Scenario | Why Net Worth Fails |
|---|---|
| Private company ownership | Valuation relies on subjective multiples; forced sales often occur at 30–50% discounts. |
| Highly leveraged real estate | Debt service can consume 70%+ of cash flow, turning "wealth" into a liability. |
| Art or collectibles | Market liquidity is low; insurance and storage costs reduce real returns. |
| Retirement accounts | Early withdrawals trigger penalties; RMDs create cash-flow constraints. |
| Offshore structures | Tax and legal risks may not be reflected in reported net worth. |

Conclusion
The net worth method’s ineffectiveness isn’t a flaw in the concept but in its one-size-fits-all application. It works for broad comparisons—like tracking a family’s progress over decades—but breaks down when precision matters. Professionals now supplement it with liquidity stress tests, cash-flow analysis, and scenario modeling to paint a fuller picture. The key takeaway? Which of the following makes the net worth method ineffective in some situations? The answer is context. A net worth of $50 million might be exceptional for a 40-year-old but precarious for a 70-year-old with healthcare costs looming. The solution isn’t to abandon net worth but to layer it with other metrics—because wealth isn’t just a number; it’s a system. For individuals, the lesson is clear: don’t confuse net worth with financial health. A high figure on paper doesn’t guarantee stability, and a lower one doesn’t preclude resilience. The most sophisticated wealth managers now use multi-dimensional frameworks—combining net worth, liquidity ratios, debt-to-income, and behavioral risk profiles—to assess true financial standing. The net worth method remains useful, but only as one piece of a far larger puzzle.Comprehensive FAQs
Q: Can net worth be adjusted to account for illiquid assets?
A: Yes, but it requires liquidity discounts. Advisors apply haircuts (e.g., 20–40%) to private company stakes, real estate, or art based on market data. For example, a $10 million private equity holding might be valued at $6–8 million in a liquidity-adjusted net worth calculation. Tools like the Wilshire Associates Liquidity Model help standardize these adjustments.
Q: How does inflation distort net worth over time?
A: Nominal net worth figures don’t account for purchasing power erosion. A $1 million portfolio in 1990 might equate to $2.5 million today in real terms, depending on inflation. To adjust, use the Consumer Price Index (CPI) or Treasury Inflation-Protected Securities (TIPS) as benchmarks. Some high-net-worth families track inflation-adjusted net worth alongside nominal figures to monitor true growth.
Q: Why do some ultra-high-net-worth individuals prefer cash-flow analysis over net worth?
A: Because cash flow reveals what net worth hides. A family with a $100 million net worth might have $20 million in annual expenses, leaving $80 million in surplus—but if $60 million of that is tied to illiquid assets, their real disposable income could be just $20 million. Cash-flow analysis also exposes hidden drains, like private jet maintenance, charitable giving, or tax liabilities, which net worth doesn’t capture.
Q: Are there industries where net worth is a worse metric than others?
A: Absolutely. In creative industries (e.g., music, film), net worth can be misleading because income is often project-based and assets (e.g., royalties) are long-term. In private equity, carried interest inflates net worth but may not be realizable for years. Even in tech, unvested stock options or restricted shares can create a paper wealth illusion. Industries with high fixed costs (e.g., manufacturing) also see net worth fluctuate wildly with inventory cycles, making it a poor stability indicator.
Q: How do estate planners use net worth differently?
A: Estate planners focus on transferable net worth—the portion that can be passed to heirs without triggering taxes, legal fees, or liquidity crises. They often exclude: - Non-transferable assets (e.g., a spouse’s separate property in community-property states). - Assets with high estate taxes (e.g., large IRAs over the $1.3 million exemption limit). - Liabilities that survive death (e.g., mortgages on inherited property). The result is a legacy-adjusted net worth, which can differ sharply from the standard calculation.
