The Short Answers
- Your net worth isn’t included in standard corporate financial statements (balance sheet, income statement, or cash flow statement).
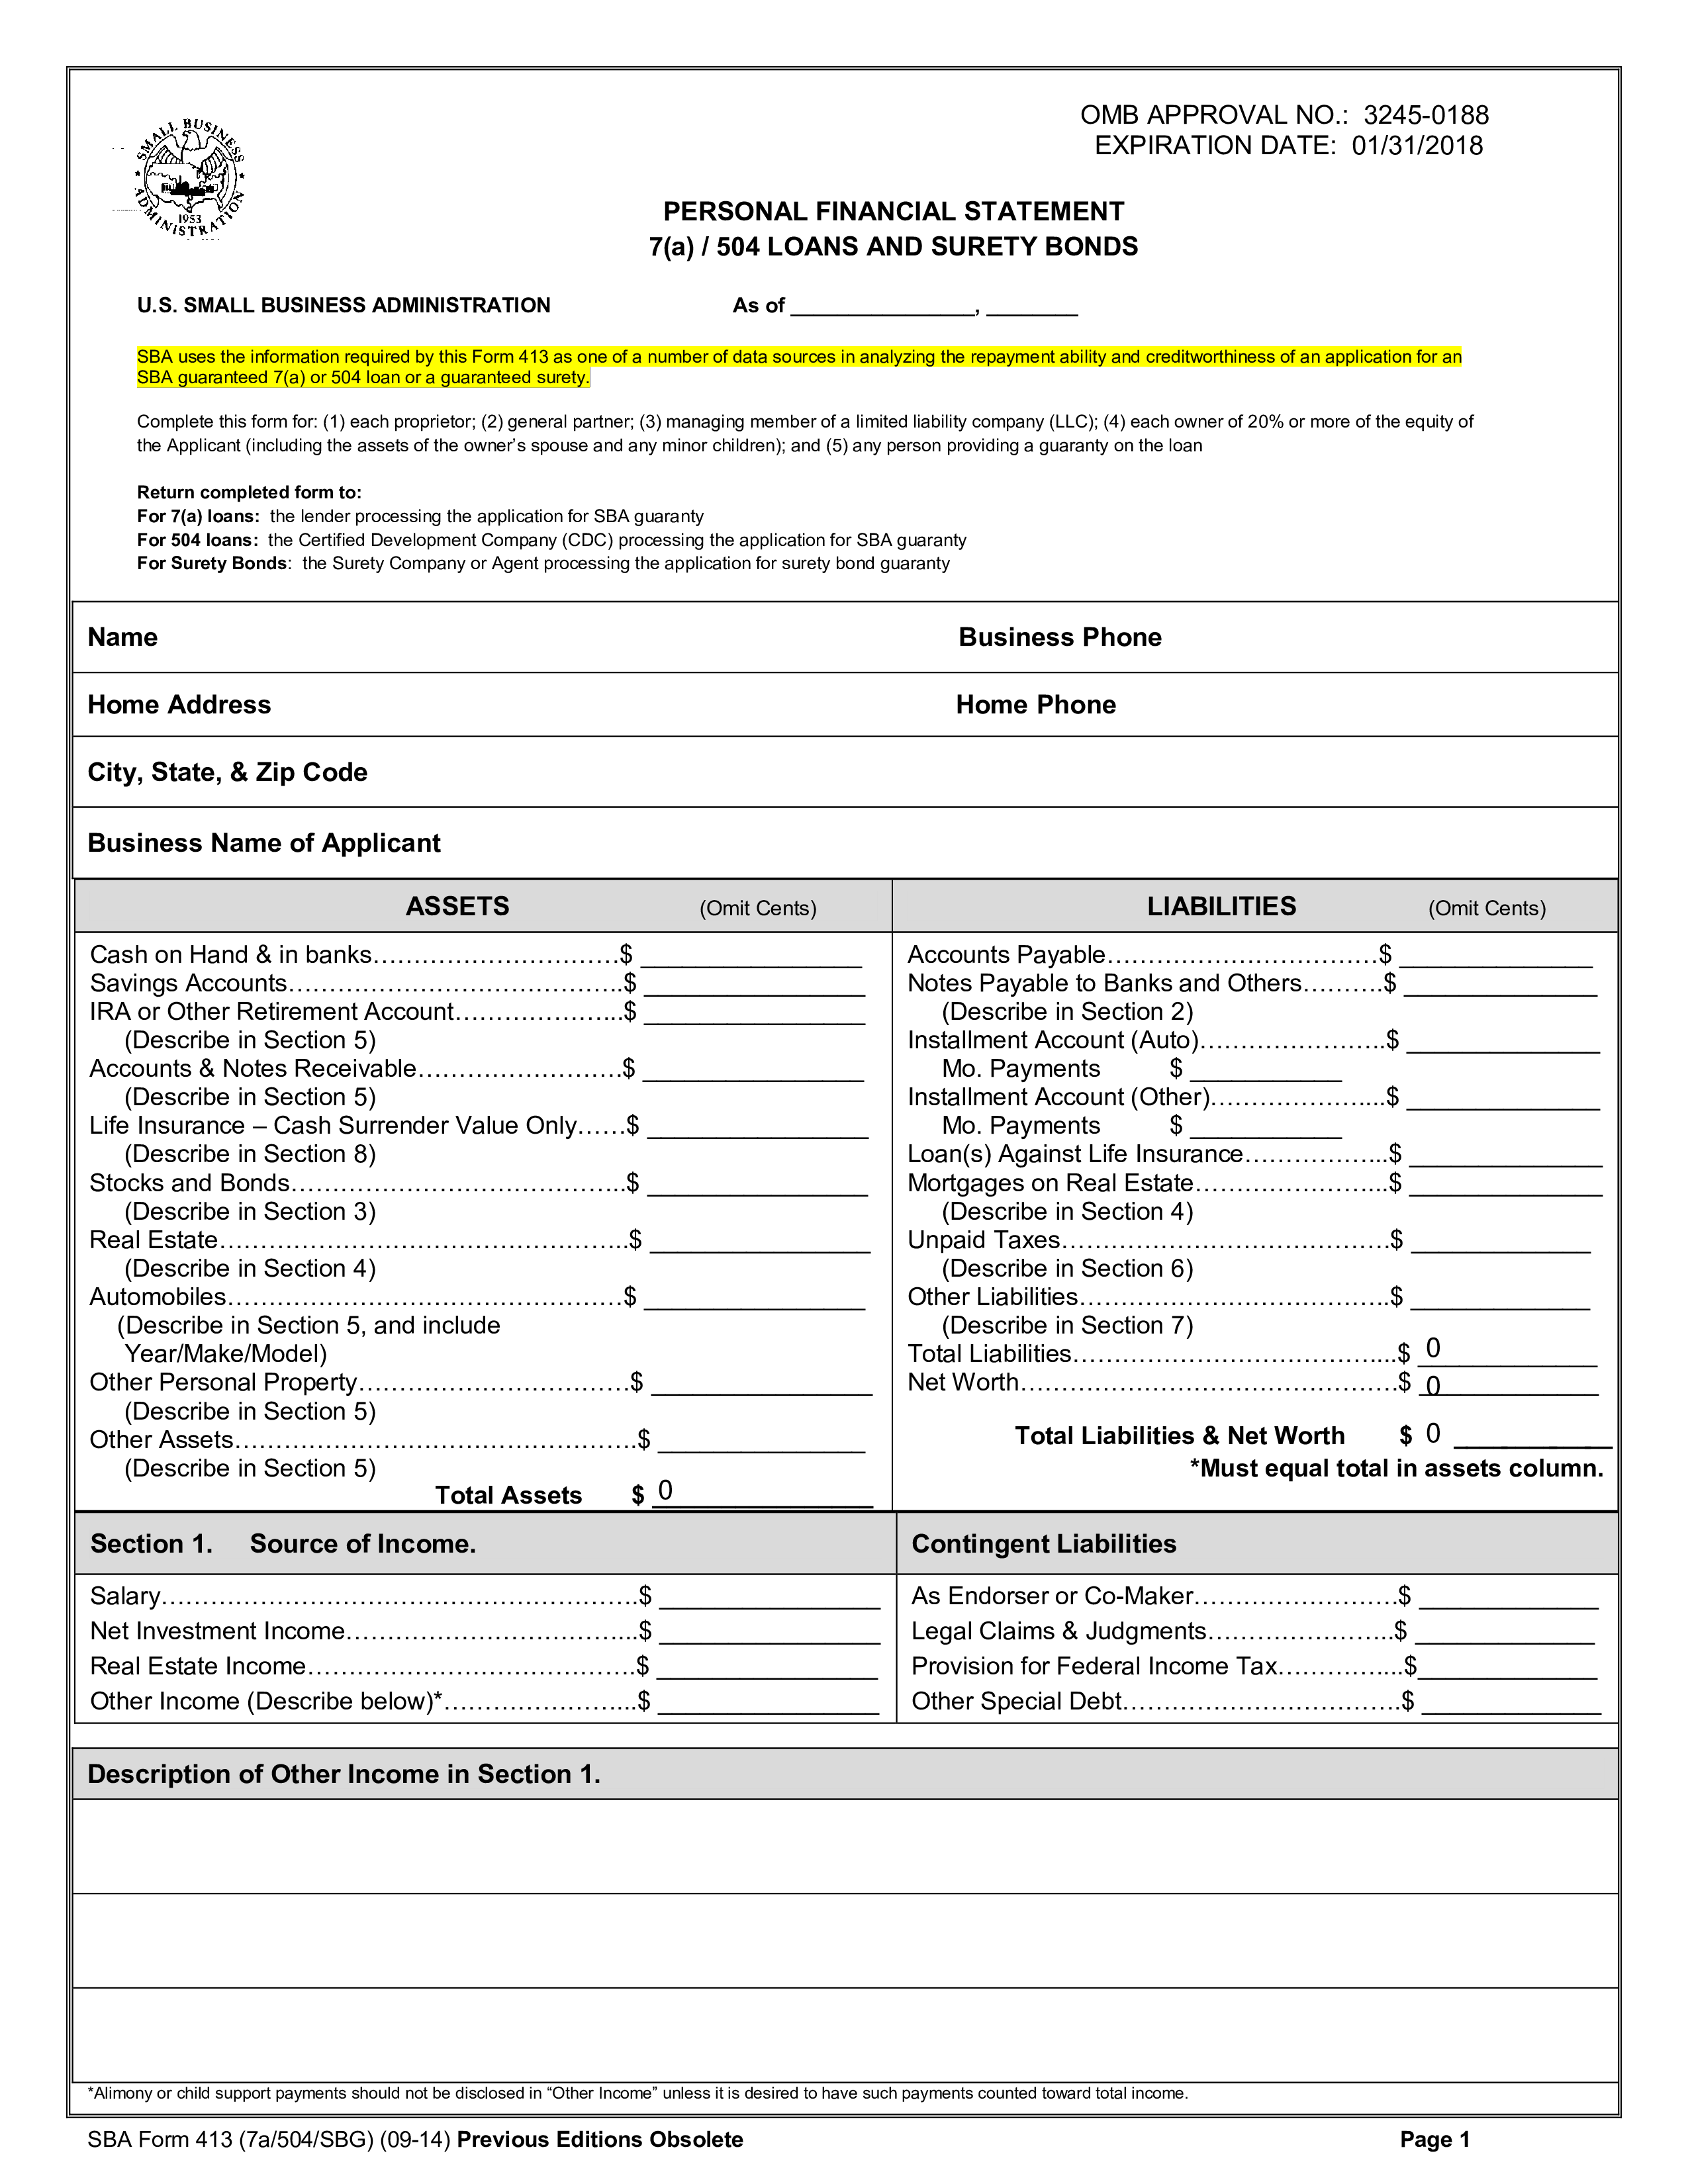
- The correct document is a personal net worth statement, which compares your assets (cash, investments, property) against liabilities (debts, loans).
- While balance sheets share structural similarities, personal net worth statements adjust for non-monetary wealth (e.g., pension vesting, intellectual property).
- Businesses use net worth internally, but it’s not reported in external filings like 10-Ks or annual reports.
- Tracking net worth requires recalculating it periodically—unlike static financial statements, which reflect a single point in time.

Deep Dive: The Full Picture
The question "which financial statement includes your net worth?" exposes a critical blind spot in financial education. Most people learn accounting through the lens of businesses—where net worth (equity) is buried in the balance sheet as shareholders’ equity. But personal finance operates on different rules. Your net worth isn’t an accounting line item; it’s a rolling snapshot of your financial ecosystem, one that evolves with market conditions, lifestyle choices, and even inflation. Here’s the irony: the very term net worth was borrowed from corporate accounting, yet its application in personal finance is far more fluid. A company’s net worth is a fixed number at year-end, derived from audited assets minus liabilities. Yours? It’s a living document, subject to daily fluctuations—stock market swings, real estate appreciation, or a new credit card balance. The statement that captures this isn’t a GAAP-compliant report. It’s a custom tool, often maintained in spreadsheets, financial apps, or even handwritten ledgers.The Context You Need
To answer "which financial statement includes your net worth?" correctly, you must first dismantle two myths: 1. Myth 1: Net worth = Savings. This is the equivalent of confusing a company’s retained earnings with its total equity. Your net worth includes all assets—cash, investments, your home’s equity, even the value of a side business—minus all debts, from student loans to credit card balances. 2. Myth 2: Financial statements and personal net worth are interchangeable. They’re not. A balance sheet lists assets and liabilities at a specific date, while a net worth statement is a dynamic assessment of your financial position, often updated monthly. The confusion arises because personal finance borrows terminology from accounting but repurposes it. In corporate terms, net worth is equity—what’s left after selling all assets and paying off debts. For individuals, it’s the same concept, but the assets and liabilities are far more diverse: a trust fund, a collectible, or even the future value of a pension plan. No standard financial statement accounts for this.The Mechanics
So if not a balance sheet, income statement, or cash flow projection—which financial statement includes your net worth? The answer lies in a personal net worth statement, a document that: - Lists assets (cash, securities, real estate, personal property) at current market value. - Lists liabilities (mortgages, loans, credit card debt) as outstanding balances. - Calculates the difference (Assets – Liabilities = Net Worth). This isn’t a GAAP requirement. It’s a personal finance best practice, often recommended by financial planners as the single most important metric for tracking progress. Unlike a corporate balance sheet—where assets and liabilities are categorized by function (current vs. non-current)—a personal net worth statement prioritizes liquidity and personal relevance. For example: - A company lists "inventory" as an asset. A personal net worth statement might list "furniture" or "jewelry" instead. - A business reports "accounts payable." An individual tracks "personal loans" or "medical debt." The key difference? Flexibility. A personal net worth statement can—and should—adapt to your life stage. A 30-year-old might focus on student loans and a 401(k). A 50-year-old might include a business ownership stake or a trust fund.Details That Change the Picture
The gap between corporate accounting and personal finance widens when you consider non-financial assets. A balance sheet can’t capture the value of: - Human capital (your earning potential over a career). - Social capital (networks that could lead to opportunities). - Intellectual property (patents, royalties, or a personal brand). These factors influence net worth but won’t appear in any standard financial statement. That’s why the personal net worth statement isn’t just a tool—it’s a philosophy. It forces you to confront questions like: - Is my home’s equity liquid? (Selling takes time.) - How much of my 401(k) can I access without penalties? (Not all assets are equal.) - What’s the real cost of my lifestyle? (Liabilities aren’t just debts—they’re also opportunity costs.)"Net worth is the silent partner in your financial life. It doesn’t scream like a stock market crash or whisper like a rising interest rate—it simply sits there, accumulating or eroding, while you focus on the wrong metrics." — Morgan Housel, The Psychology of Money
| Corporate Financial Statement | Personal Net Worth Statement |
|---|---|
| Balance Sheet (Assets = Liabilities + Equity) | Assets – Liabilities = Net Worth |
| Static snapshot (audited annually) | Dynamic, updated as often as needed |
| Focuses on business operations | Focuses on personal financial health |
| Regulated by GAAP/IFRS | No formal standards—customizable |

Conclusion
The question "which financial statement includes your net worth?" isn’t just about semantics—it’s about owning your financial narrative. Corporations use net worth internally, but they don’t report it publicly because it’s not actionable for investors. For individuals, however, net worth is the most actionable metric you have. It tells you whether you’re building wealth or just treading water. Here’s the hard truth: Most people don’t track net worth correctly. They rely on bank balances, ignore illiquid assets, or treat it as a static number rather than a living benchmark. The personal net worth statement isn’t a replacement for financial statements—it’s a complement, one that fills the gaps left by traditional accounting. By mastering it, you’re not just answering a technical question. You’re taking control of your financial future.Comprehensive FAQs
Q: Is a personal net worth statement the same as a balance sheet?
A: No. A balance sheet is a corporate accounting tool that follows strict rules (GAAP/IFRS) and categorizes assets/liabilities by function. A personal net worth statement is flexible, prioritizing personal relevance over accounting standards. For example, a balance sheet might list "prepaid expenses," while a net worth statement lists "vacation funds."
Q: Can I use a balance sheet to track my net worth?
A: Technically, yes—but it’s inefficient. A balance sheet is designed for businesses, not individuals. You’d have to manually adjust for personal assets (e.g., a car’s depreciation) and exclude non-business liabilities (e.g., personal loans). A dedicated net worth statement is far clearer and more practical.
Q: Do financial advisors recommend tracking net worth?
A: Absolutely. Every major financial planning framework—from the "Bucket List" approach to the "Rule of 100" for retirement—relies on net worth as a baseline. Advisors use it to assess risk tolerance, retirement readiness, and even insurance needs. Without it, you’re flying blind.
Q: How often should I update my net worth statement?
A: At least quarterly, but ideally monthly if your financial situation changes frequently (e.g., stock market volatility, new debts, or large purchases). The more you update it, the more accurate—and motivating—your financial picture becomes.
Q: What’s the biggest mistake people make when calculating net worth?
A: Overvaluing assets and undervaluing liabilities. For example: - Listing a home’s purchase price instead of current market value. - Ignoring future liabilities (e.g., college tuition for kids). - Excluding "soft" assets like a side hustle’s potential earnings. This can inflate net worth by 20–50%, leading to false confidence.
