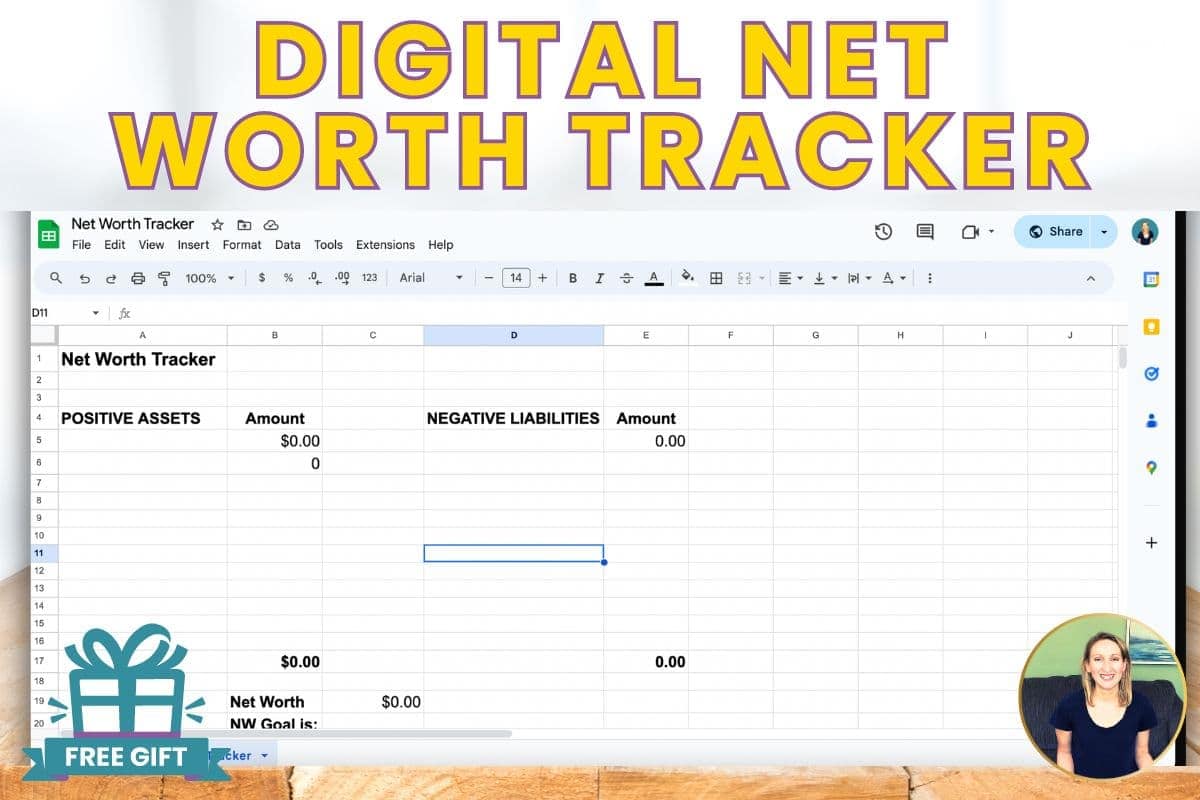
Net worth is a snapshot of financial health, but not all assets are created equal. Whole life insurance policies—often marketed as both a death benefit and an investment—create a unique accounting dilemma. The policy’s cash value grows tax-deferred, yet surrendering it early triggers penalties. Meanwhile, the death benefit itself is typically excluded from net worth calculations, creating a tension between liquidity and legacy planning. For high-net-worth individuals or those with complex estates, misclassifying whole life insurance can skew financial strategies, understate risk exposure, or even trigger unintended tax consequences.
The confusion stems from how these policies straddle two roles: insurance and investment. Traditional assets like stocks or real estate are straightforward—you own them, they have a market value, and you can sell them. Whole life insurance, however, operates differently. Its value isn’t liquid until surrendered, and the death benefit isn’t an asset you can access during your lifetime. Yet its cash value accumulates over decades, often becoming a significant portion of an individual’s wealth. When tracking net worth, how do you treat whole life insurance? The answer depends on whether you’re assessing liquidity, tax efficiency, or estate planning needs.
Industry professionals debate whether to include whole life cash value at all. Some advisors treat it as an illiquid asset, others as a forced savings vehicle, and a few argue it should be excluded entirely unless the policyholder has a clear surrender strategy. The lack of standardization means even sophisticated investors may overlook critical nuances—like how policy loans or dividends affect net worth, or how surrender charges erode value. Without a clear framework, the policy’s true financial impact remains obscured.
6 Things Worth Knowing About Whole Life Insurance in Net Worth Calculations
Understanding how whole life insurance fits into net worth requires parsing its dual nature: insurance protection and cash accumulation. Below are six critical factors that determine whether—and how—to include it in financial statements.
####
1. Cash Value Is an Asset, But Not a Liquid One
Whole life insurance policies build cash value over time, which can be accessed through withdrawals or loans. However, this value isn’t as liquid as a bank account or investment portfolio. Surrendering a policy early often triggers surrender charges, which can reduce the cash value significantly. When tracking net worth, how do you treat whole life insurance? Most financial advisors recommend including the current cash value—adjusted for any outstanding loans or fees—but treating it as a non-liquid asset. This reflects its restricted accessibility while acknowledging its contribution to wealth.
The challenge lies in valuation. Unlike stocks, which have daily market prices, whole life cash value is determined by the insurer’s internal models, which may not align with external market conditions. Some high-net-worth individuals use a
conservative estimate (e.g., 70-80% of the stated cash value) to account for potential surrender penalties, while others rely on the insurer’s projected value. The key is consistency—whether you’re comparing year-over-year net worth or planning for estate distribution.
####
2. The Death Benefit Is Not Part of Net Worth (But Should It Be?)
The death benefit in a whole life policy is intended to pass wealth to beneficiaries, not to be part of the policyholder’s liquid assets. Traditional net worth calculations exclude death benefits because they’re not accessible during the insured’s lifetime. However, this creates a philosophical question: Should the death benefit’s potential value influence how you treat whole life insurance when tracking net worth?
Some wealth managers argue that the death benefit’s
economic value—what it could provide to heirs—should be considered in estate planning, even if not in net worth calculations. For example, a policy with a $1 million death benefit might offset future tax liabilities or provide liquidity to heirs. Others counter that including it would inflate net worth artificially, since the policyholder can’t access those funds. The consensus? Exclude the death benefit from net worth unless you’re using a modified approach that accounts for estate liquidity needs.
####
3. Policy Loans and Dividends Complicate the Ledger
Whole life policies often allow policyholders to take loans against their cash value or receive dividends from participating policies. Both can distort net worth if not tracked carefully. A policy loan, for instance, isn’t a traditional debt—it’s a reduction in the death benefit and cash value. Yet, if left unpaid, it can trigger a taxable event when the policy lapses.
When tracking net worth, how do you treat whole life insurance
with outstanding loans? The safest method is to deduct the loan balance from the cash value before including it in net worth. Dividends, meanwhile, should be treated like investment income—either reinvested (increasing cash value) or taken as cash (adding to liquid assets). Failing to account for these transactions can lead to an overstated net worth, especially if dividends are used to pay premiums or loans.
####
4. Surrender Charges and Fees Eat Into Realized Value
One of the most overlooked aspects of whole life insurance is the surrender charge schedule, which typically declines over 10-20 years. Early surrender can wipe out years of cash value accumulation. When tracking net worth, how do you treat whole life insurance if the policyholder plans to surrender it? The answer depends on timing:
-
Short-term surrender (first 5-10 years): Subtract surrender charges from cash value before including it in net worth.
- Long-term surrender (after charges expire): The full cash value can be included, but tax implications (e.g., gain on surrender) must be considered.
- No surrender plans: Treat cash value as an illiquid asset, but note that future access may be restricted.
Some advisors recommend
stress-testing the policy’s value under different surrender scenarios to see how it impacts net worth projections.
####
5. Tax Implications Can Turn an Asset Into a Liability
Whole life insurance cash value grows tax-deferred, but withdrawals or surrenders beyond the policy’s cost basis become taxable income. This creates a paradox: When tracking net worth, how do you treat whole life insurance if its value is partially unrealized until accessed? The solution is to account for potential tax liabilities as a hidden deduction.
For example:
- If a policy’s cash value is $100,000 but the cost basis (premiums paid minus dividends) is $50,000, a full surrender could trigger a taxable gain of $50,000.
- Policy loans reduce the death benefit but aren’t taxable—unless the policy lapses with an outstanding loan.
- Dividends are typically not taxable if reinvested, but cash dividends may be subject to income tax.
Ignoring these tax dynamics can lead to overestimating net worth. Some ultra-high-net-worth individuals use
tax-equivalent net worth adjustments to reflect the true after-tax value of the policy.
#### 6. Estate Planning Context Often Dictates Treatment
For many, whole life insurance’s primary role is estate equalization or wealth transfer. In this case, the policy’s value isn’t just about cash value—it’s about how it integrates with other assets. When tracking net worth, how do you treat whole life insurance in an estate plan?

- Irrevocable life insurance trusts (ILITs): The policy is removed from the insured’s taxable estate, so its value shouldn’t be included in personal net worth.
- Second-to-die policies: Often used to offset estate taxes; their value may be excluded if structured properly.
- Charitable remainder trusts: If the policy is donated to a charity, its value is removed from net worth but may qualify for tax deductions.
In these scenarios, the policy’s net worth impact is secondary to its estate planning role. Some advisors maintain separate "estate net worth" and "personal net worth" calculations to distinguish between liquid assets and legacy tools.
How These Facts Connect
The six factors above reveal that whole life insurance defies simple classification in net worth tracking. It’s neither purely an asset nor purely a liability—its treatment depends on intent, timing, and structure. The tension between cash value (an asset) and death benefit (a future liability) forces investors to ask:
Is this policy a wealth-building tool, an insurance safety net, or both?
The table below compares the most critical considerations when determining how to treat whole life insurance in net worth calculations:
| Factor |
Standard Treatment |
Alternative Approach |
Key Risk |
| Cash Value |
Include at stated value (adjusted for loans) |
Discount for surrender charges or illiquidity |
Overstating liquidity if policy can’t be accessed |
| Death Benefit |
Exclude from net worth |
Include as "potential liquidity" for heirs |
Inflating net worth artificially |
| Policy Loans |
Deduct from cash value |
Treat as debt (if policy lapses) |
Taxable event on lapse |
| Tax Implications |
Ignore until withdrawal/surrender |
Adjust net worth for deferred tax liabilities |
Unexpected tax bills eroding value |
The overarching lesson? Whole life insurance’s net worth treatment isn’t one-size-fits-all. A policy that’s ideal for estate planning may distort personal net worth if included at face value. Conversely, excluding it entirely might understate its role as a forced savings mechanism. The optimal approach balances realistic valuation with strategic intent.
Conclusion
Whole life insurance remains one of the most misunderstood components of net worth tracking. Its hybrid nature—part insurance, part investment—demands a nuanced approach. The mistake many make is treating it like a traditional asset: plugging in the cash value without accounting for fees, taxes, or illiquidity. Yet, ignoring it entirely risks overlooking a significant portion of an individual’s wealth, especially for those who’ve held policies for decades.
The solution lies in customization. High-net-worth individuals should work with advisors to define whether the policy’s primary purpose is liquidity, legacy planning, or tax deferral, then adjust net worth calculations accordingly. For most, the safest method is to include cash value at a conservative estimate, exclude the death benefit, and account for loans and fees separately. But for those with complex estates, a modified approach—such as separating "personal" and "estate" net worth—may be necessary. Ultimately, when tracking net worth, how you treat whole life insurance should align with how you intend to use it.
Comprehensive FAQs
#### Q: Should I include the full cash value of my whole life policy in net worth?
A: No. While the cash value is an asset, it’s illiquid due to surrender charges and fees. Most advisors recommend including 70-90% of the stated cash value to account for potential penalties. If you have a clear surrender plan, you can adjust this percentage based on the policy’s surrender charge schedule.
#### Q: Does taking a policy loan affect my net worth?
A: Yes. A policy loan reduces both the cash value and death benefit, so it should be deducted from the policy’s net worth contribution. However, unlike traditional debt, it’s not a liability—it’s a reduction in the policy’s value. If the loan remains unpaid when the policy lapses, it may trigger a taxable event.
#### Q: Can I exclude whole life insurance from net worth entirely?
A: It’s possible, but not recommended unless the policy is held in an irrevocable trust or serves purely as insurance (with negligible cash value). Excluding it entirely ignores its role as a forced savings vehicle, which can distort long-term wealth projections. A better approach is to include a discounted cash value rather than omitting it.
#### Q: How do dividends from a whole life policy impact net worth?
A: Dividends reinvested into the policy increase cash value and should be included in net worth adjustments. If taken as cash, they add to liquid assets but may be taxable. Unlike stock dividends, whole life dividends are not guaranteed and can vary yearly, so they shouldn’t be treated as reliable income.
#### Q: What’s the best way to track whole life insurance in net worth over time?
A: Maintain a separate ledger for the policy, recording:
- Annual cash value changes
- Premiums paid and dividends received
- Outstanding loans or withdrawals
- Surrender charge schedules
Update net worth calculations quarterly or annually to reflect these adjustments. Some wealth management software allows custom tags for insurance assets to automate tracking.
#### Q: Does the type of whole life policy (e.g., universal vs. traditional) change how it’s treated in net worth?
A: Yes. Traditional whole life policies have fixed premiums and cash value growth, making them easier to model. Universal life policies offer flexibility but require tracking cost of insurance (COI) charges, which reduce cash value. Variable universal life adds another layer, as cash value depends on underlying investments. Always review the policy’s illustration and fees to adjust net worth treatment accordingly.