
5 Things Worth Knowing About a Net Worth Statement
A net worth statement is most commonly used in scenarios where financial transparency is non-negotiable. Yet its application varies widely depending on the context. Below are five critical aspects that define its role, from legal enforceability to strategic planning.1. It’s the Gold Standard in High-Stakes Negotiations
When parties with significant assets are involved—whether in divorce proceedings, mergers, or inheritance disputes—a net worth statement is most commonly used to level the playing field. Courts, for instance, often require spouses to disclose their net worth during divorce settlements to ensure equitable distribution. Without this document, one party might conceal assets, leaving the other at a disadvantage. Similarly, in business acquisitions, buyers demand updated net worth statements to verify claims about a company’s financial health before finalizing deals. The statement’s precision reduces the risk of fraudulent misrepresentations, making it indispensable in high-value transactions. Its role extends beyond legal battles. Private equity firms, for example, use net worth statements to assess potential partners or investors. A founder with a net worth in the millions may command different terms than one barely scraping by—even if both report the same revenue. The document’s granularity exposes what balance sheets and profit-and-loss statements often obscure: the true liquidity and hidden liabilities of an individual or business.2. Legal Weight Varies by Jurisdiction
A net worth statement is most commonly used as evidence in court, but its admissibility depends on how it’s prepared and verified. In some jurisdictions, a self-prepared statement carries little weight unless notarized or sworn under oath. Others, like New York or California, may require independent verification—such as a third-party appraisal of assets—to hold up in litigation. This variability means that individuals and businesses must tailor their statements to local legal standards, often consulting financial forensic experts to ensure compliance. Even outside courtrooms, the statement’s credibility hinges on documentation. Lenders, for instance, may reject a net worth statement unless it’s accompanied by bank records, property deeds, or investment account statements. The more rigorous the verification process, the more likely the document will be accepted as a reliable gauge of financial standing. This principle holds true whether the goal is securing a loan or negotiating a settlement—accuracy is non-negotiable.3. It Reveals More Than Just Numbers
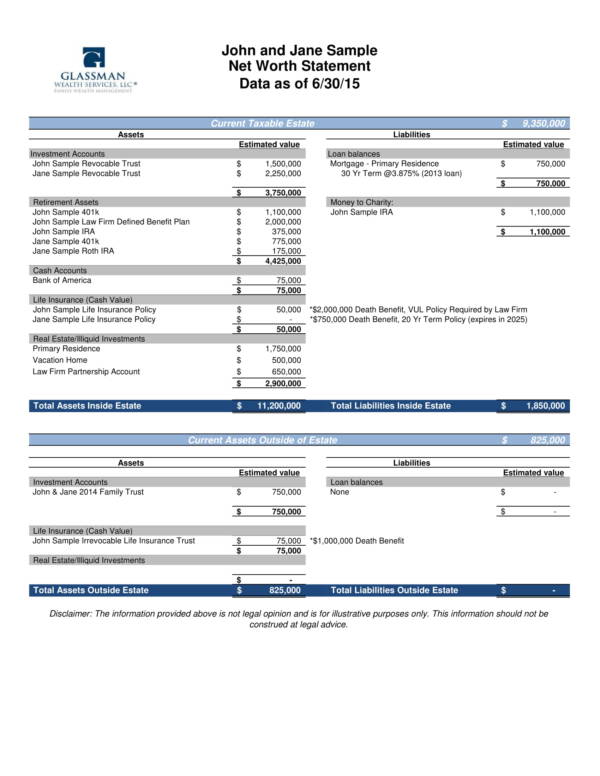
While the primary function of a net worth statement is to quantify assets and liabilities, its secondary value lies in what it doesn’t say. For example, a statement might show a high net worth but fail to account for pending lawsuits, unreported income, or off-balance-sheet obligations. These omissions can have severe consequences. In divorce cases, hidden assets—such as undeclared cryptocurrency or overseas accounts—often surface during discovery, leading to renegotiated settlements. Similarly, business owners may underreport liabilities to attract investors, only to face backlash when financial troubles emerge. Professionals who prepare these statements must anticipate such gaps. A well-constructed net worth statement includes footnotes or appendices detailing assumptions, pending transactions, or contingent liabilities. This transparency not only strengthens the document’s integrity but also protects the preparer from accusations of misrepresentation.4. Timing Matters More Than You Think
A net worth statement is most commonly used at specific junctures—not as a static record but as a dynamic tool tied to critical events. Filing for divorce? The statement’s date could determine asset division. Selling a business? A snapshot taken just before closing ensures buyers aren’t misled by recent depreciation. Even in estate planning, a net worth statement prepared months before a client’s passing might reveal discrepancies if assets were transferred irregularly. The timing of updates is equally critical. A statement frozen mid-year might miss seasonal fluctuations in cash flow or inventory values. For high-net-worth individuals, quarterly reviews are standard practice to reflect changes in market conditions, tax strategies, or personal spending. Neglecting to update the document risks outdated figures being used in high-stakes decisions—figures that could cost thousands or even millions.5. It’s a Strategic Tool for Wealth Preservation
Beyond its reactive uses, a net worth statement is most commonly used proactively to preserve and grow wealth. High-net-worth families, for instance, maintain updated statements to optimize tax planning, identify underperforming assets, or preempt creditor claims. A sudden drop in net worth might trigger a review of insurance policies or investment allocations to mitigate risk. Similarly, entrepreneurs use these statements to pitch to venture capitalists, framing their personal financial health as collateral for business loans. The document also serves as a reality check. Seeing one’s net worth in black and white can prompt difficult conversations—about spending habits, debt management, or the need for professional advice. For those who treat it as a living document rather than a one-time exercise, the net worth statement becomes a compass for financial discipline.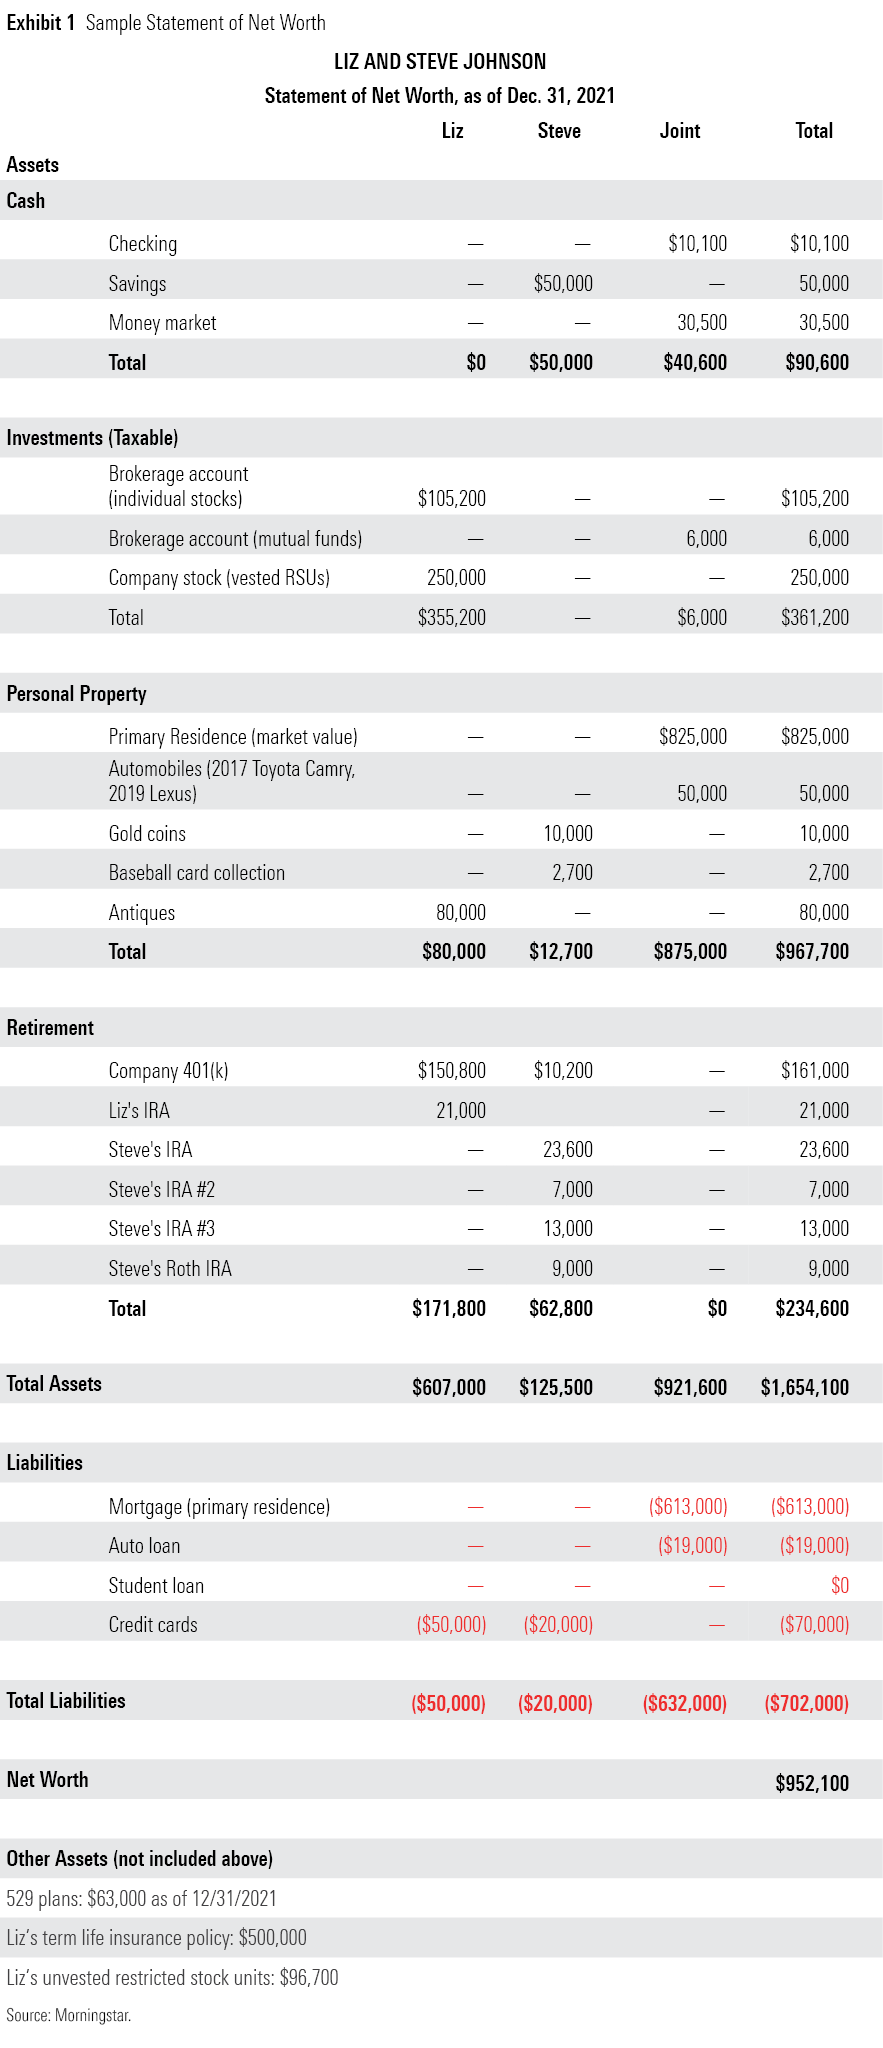
How These Facts Connect
The net worth statement’s power lies in its dual nature: it is both a legal safeguard and a strategic asset. Its role in negotiations and courtrooms underscores its ability to resolve disputes by replacing speculation with verifiable data. Yet its value extends beyond conflict resolution into planning and preservation, where it helps individuals and businesses anticipate challenges before they arise. The interplay between timing, legal standards, and transparency reveals why this document is indispensable in modern finance—whether the goal is to protect assets, secure funding, or navigate personal crises. The most critical insight is that a net worth statement is most commonly used not in isolation, but as part of a broader financial ecosystem. It doesn’t operate in a vacuum; its effectiveness depends on how it’s integrated with tax returns, business records, and legal advice. For example, a statement prepared without consulting an attorney might overlook jurisdictional nuances that could invalidate it in court. Similarly, a business owner who updates their net worth annually but ignores market trends may miss opportunities to rebalance their portfolio. The document’s true strength emerges when it’s treated as one piece of a larger puzzle—one that requires expertise to assemble correctly.| Key Aspect | Legal Context | Strategic Use | Common Pitfall |
|---|---|---|---|
| Negotiation Tool | Admissible in divorce/court cases | Leverage in M&A or partnerships | Outdated figures used in deals |
| Verification Requirements | Notarization or third-party appraisal needed | Builds trust with lenders/investors | Self-prepared statements dismissed |
| Hidden Liabilities | Can void settlements if omitted | Identifies tax or legal risks | Undisclosed debts resurface later |
| Timing Sensitivity | Date affects asset division | Guides investment decisions | Stale data used in critical moments |
Conclusion
A net worth statement is most commonly used when the stakes are high, and the margin for error is slim. Its ability to distill complex financial lives into a single, defensible number makes it a cornerstone of modern wealth management. Yet its utility hinges on preparation—on ensuring the document is accurate, timely, and tailored to its intended purpose. For individuals, this means recognizing when to update it; for businesses, it means understanding how it influences deals. Ignoring these principles risks turning a powerful tool into a liability. The statement’s enduring relevance stems from its adaptability. Whether in private negotiations or public litigation, it serves as a bridge between financial reality and legal or business outcomes. The key to maximizing its value lies in treating it not as a static report, but as a dynamic reflection of one’s financial health—one that evolves alongside life’s changes.Comprehensive FAQs
Q: How often should I update my net worth statement?
A: The frequency depends on your financial activity. High-net-worth individuals or business owners typically review theirs quarterly, while others may update annually. Significant life events—like marriage, divorce, or major purchases—should trigger an immediate update to ensure accuracy.
Q: Can a net worth statement replace a tax return?
A: No. A net worth statement focuses on assets and liabilities at a single point in time, while tax returns track income and deductions over a fiscal year. However, both documents are often used together in legal or financial planning contexts to provide a fuller picture.
Q: What happens if I underreport my assets in a divorce settlement?
A: Courts take asset concealment extremely seriously. If discovered, it can lead to penalties, renegotiated settlements, or even criminal charges for fraud. Financial forensic accountants are often hired to uncover hidden assets, making transparency the safest strategy.
Q: Do lenders require net worth statements for personal loans?
A: Not typically for small personal loans, but high-value lenders—such as those offering private mortgages or business lines of credit—often demand them to assess risk. The more complex the loan, the more likely a net worth statement will be requested to verify collateral or repayment capacity.
Q: Can I prepare my own net worth statement, or should I hire a professional?
A: You can prepare a basic version yourself, but professionals—such as CPAs or financial advisors—ensure compliance with legal standards, especially in disputes. For court cases or high-stakes negotiations, independent verification is strongly advised to avoid challenges to its validity.
Q: How do cryptocurrency holdings factor into a net worth statement?
A: Cryptocurrency must be included if it represents a material portion of your assets. However, its volatile nature may require additional disclosures about market fluctuations or pending transactions. Some jurisdictions treat crypto as property, while others classify it as currency—consulting a tax professional is critical to avoid misclassification.
Q: What’s the difference between a net worth statement and a balance sheet?
A: Both list assets and liabilities, but a balance sheet is a financial accounting tool used by businesses to reflect equity at a specific time. A net worth statement, by contrast, is often personalized and may include non-liquid assets (like art or real estate) that wouldn’t appear on a corporate balance sheet.
