
The Complete Overview of the $97,300 Net Worth American Household
The median net worth of $97,300 for American households isn’t a measure of prosperity—it’s a measure of survival. It represents the point where half of all households have more, half have less, and the divide between those two halves grows wider with each economic cycle. This figure, derived from the Federal Reserve’s triennial survey, is the product of decades of wage stagnation, asset inflation, and policy shifts that favor debt over equity. For policymakers, it’s a warning: the middle class isn’t just shrinking; it’s being redefined downward. For individuals, it’s a reality check: financial security at this level is fragile, dependent on geography, education, and sheer luck. The $97,300 threshold also reveals the limits of traditional wealth-building narratives. Homeownership remains the primary driver of net worth, yet in high-cost cities, that $97,300 might cover only a fraction of a down payment. Meanwhile, the gig economy and contract work—now the norm for 36% of workers—offer no path to asset accumulation. The figure doesn’t account for the 20% of Americans who report skipping medical care due to cost, or the 1 in 5 households that can’t cover a $400 emergency. In short, the $97,300 net worth American household is neither thriving nor failing—it’s existing, in a system where upward mobility is no longer guaranteed.Historical Background and Evolution
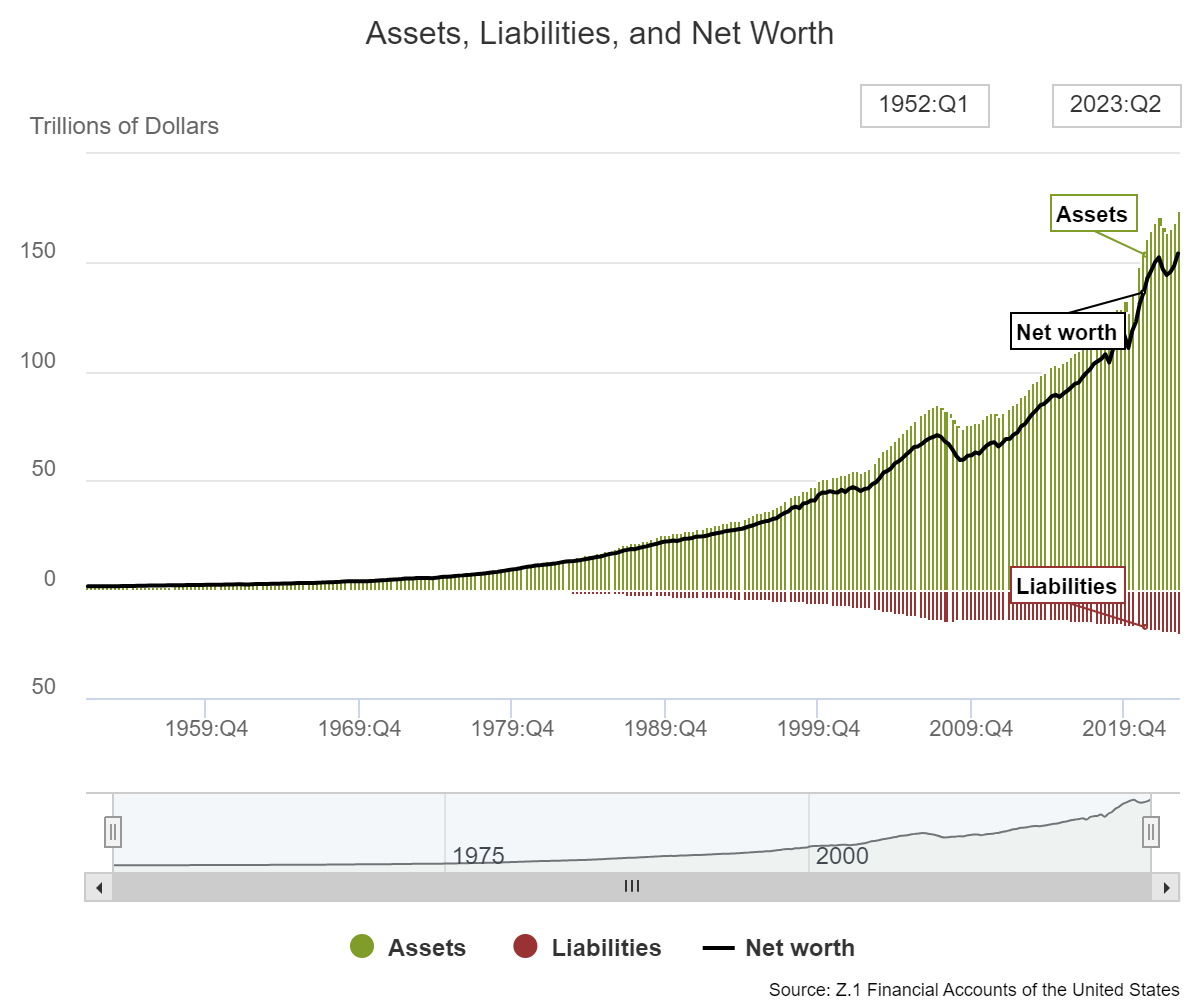
The trajectory of the median household net worth tells a story of two economies. In 1989, the median net worth was $87,900 (adjusted for inflation), a figure that seemed robust at the time. But by 2010, after the Great Recession, it had plummeted to $55,000—a 38% drop. The recovery since then has been uneven. While the S&P 500 and real estate markets rebounded sharply, wage growth lagged. The $97,300 figure today is less a sign of progress than a return to pre-crisis levels, achieved only because asset prices (not incomes) have risen. This disconnect explains why, despite the headline number, 40% of Americans still can’t afford a $400 emergency. What’s often overlooked is how this median masks deeper trends. The top 1% of households now hold 35% of all wealth, up from 25% in 1989. Meanwhile, the bottom 50% hold just 2.6%—a collapse from 12% four decades ago. The $97,300 net worth is thus less a measure of the middle class and more a statistical artifact of extreme inequality. For millennials, the picture is starker: their median net worth is $92,300, but their student debt averages $30,000, leaving little for homeownership or retirement. The figure also ignores the racial wealth gap, where the median white household sits at $188,200 versus $24,100 for Black households—a gap that persists despite identical incomes.Core Mechanisms: How It Works
The $97,300 net worth isn’t distributed evenly—it’s a product of three interlocking systems: asset ownership, debt exposure, and geographic luck. Homeownership is the single biggest factor. A household with a paid-off home in a low-cost state might have a net worth of $200,000, while a renter in a high-cost city could have negative net worth despite similar incomes. Retirement accounts (401(k)s, IRAs) account for 28% of the median net worth, but only 56% of Americans have access to a retirement plan through work. Meanwhile, student debt—now $1.7 trillion nationally—drags down net worth for younger households, even if they earn six-figure salaries. The role of inheritance is often underestimated. The median inheritance for households receiving one is $64,000, a figure that can double or triple net worth overnight. Without it, the $97,300 benchmark becomes a moving target. Tax policy also plays a hidden role: capital gains taxes favor those who own assets (like stocks or homes) over those who rely on wages. The result? A system where wealth begets wealth, and poverty begets debt. Even the $97,300 figure assumes no major financial shocks—one medical emergency or job loss can erase it entirely.Key Benefits and Crucial Impact
On the surface, a $97,300 net worth suggests financial stability. It’s enough to cover six months of expenses for the median household, according to the Federal Reserve. It allows for modest investments in education or small business ventures. It might even qualify a family for certain low-income subsidies in some states. But the benefits are conditional. In a city where the median rent is $1,500, that net worth would last just 13 months if unemployment struck. The figure also obscures the cost of living: in Hawaii, $97,300 is a fraction of what it buys in Mississippi. The impact of this net worth level extends beyond individuals. It shapes local economies, influencing everything from home values to small business lending. Communities with median net worths below $50,000 see higher crime rates, lower educational attainment, and slower job growth. Conversely, areas where the median exceeds $200,000 attract corporate investment and higher wages—but only for those who already own assets. The $97,300 threshold is thus a tipping point: above it, opportunities multiply; below it, they vanish."Wealth isn’t just about money—it’s about access. A $97,000 net worth might get you a loan in one county but not in another. It might buy you a home in Indiana but not in California. The number is meaningless without the zip code." — Darrick Hamilton, economist and director of the Institute on Assets and Social Policy
Major Advantages
- Emergency cushion: The median household can cover ~6 months of expenses without income, though this varies wildly by region.
- Homeownership eligibility: In low-cost markets, this net worth can secure a down payment (often 3-5% of home value).
- Investment access: Brokerage accounts and retirement contributions become feasible, though returns are modest at this scale.
- Credit flexibility: Lower debt-to-income ratios improve chances for loans, refinancing, or small business credit.
- Intergenerational transfer: For older households, this net worth can fund college tuition or care for aging parents.
Comparative Analysis
| Metric | Median Net Worth ($97,300 Household) |
|---|---|
| Top 10% Threshold | $1.1 million+ (11x higher) |
| Bottom 50% Share of Wealth | 2.6% (down from 12% in 1989) |
| Homeownership Rate | 65% (vs. 48% for renters) |
| Student Debt Impact | Reduces net worth by ~30% for millennials |
| Racial Disparity | White: $188,200 | Black: $24,100 | Hispanic: $36,100 |
Future Trends and Innovations
The $97,300 net worth is unlikely to rise significantly in the next decade unless structural changes occur. Wage growth has averaged just 0.5% annually since 2000, while asset prices (homes, stocks) have outpaced inflation. One potential shift: the rise of "asset-light" wealth-building, where side hustles and digital assets (crypto, NFTs) replace traditional savings. However, these are speculative and volatile. Another trend is the growing role of employer-sponsored benefits—student loan repayment assistance, childcare stipends, and 401(k) matches—which could incrementally boost net worth for middle-class workers. The biggest wild card is policy. Proposals like wealth taxes, expanded child tax credits, or student debt forgiveness could reshape the distribution. But given political gridlock, the most likely scenario is stagnation—with the median net worth creeping up only if asset prices continue their upward trajectory. For individuals, the message is clear: the $97,300 household must treat wealth like a business, diversifying income streams and protecting against inflation. The era of passive wealth accumulation is over.
Conclusion
The $97,300 net worth American household is neither rich nor poor—it’s the new normal, a statistical median that hides more than it reveals. It reflects an economy where asset ownership is the primary path to security, where geography dictates opportunity, and where debt is the default for the next generation. The figure is a reminder that financial health isn’t just about income; it’s about inheritance, luck, and the policies that shape both. For those at this threshold, the challenge isn’t just to grow wealth, but to insulate it against the next recession, the next medical crisis, or the next policy shift. The data also serves as a warning to policymakers. If the median net worth stagnates, the middle class will continue to shrink. The question isn’t whether $97,300 is enough—it’s whether it’s sustainable. And at this point, the answer is unclear.Comprehensive FAQs
Q: How does the $97,300 net worth compare to other countries?
The U.S. median is higher than in many European nations (e.g., Germany’s median is ~$60,000) but lower than in Nordic countries (Sweden’s median is ~$150,000). The difference stems from stronger social safety nets abroad and higher U.S. homeownership rates—though American wealth is more concentrated at the top.
Q: Can a household with $97,300 afford a home?
It depends entirely on location. In Mississippi, this net worth could cover a 20% down payment on a median-priced home ($150,000). In California, it might buy just 5% of a starter home ($700,000 median price). Lenders typically require 3-20% down, so the answer varies widely.
Q: Does this net worth include retirement accounts?
Yes, the Federal Reserve’s survey includes retirement accounts (401(k)s, IRAs) as part of net worth. However, these assets are illiquid—withdrawing early incurs penalties—and their value fluctuates with market conditions. For many near retirement, this inclusion is a double-edged sword.
Q: How does student debt affect this net worth?
Student debt reduces net worth significantly. A household with $30,000 in student loans but $127,300 in other assets would still report $97,300 as net worth—but their liquidity is far lower. Millennials with debt are 20% less likely to own homes, directly impacting long-term wealth.
Q: Is $97,300 enough for early retirement?
No, not under traditional rules. The "4% rule" (withdrawing 4% annually) would require $2.4 million to generate $97,000/year in retirement. This net worth might support early retirement only in ultra-low-cost areas or with supplemental income (e.g., Social Security, part-time work).
Q: How does this net worth vary by age?
Net worth rises sharply with age: under 35, the median is $42,000; ages 35-44, it’s $132,000; ages 45-54, $255,000; and 55+, $320,000. The $97,300 figure is a national average—individuals in their 40s or 50s are far more likely to reach this threshold than younger households.
Q: What’s the biggest threat to maintaining this net worth?
Medical expenses and job loss are the top risks. A single $50,000 medical bill can wipe out this net worth, while unemployment lasting more than six months often forces asset liquidation. Inflation also erodes purchasing power—$97,300 today may not cover the same expenses in a decade.
