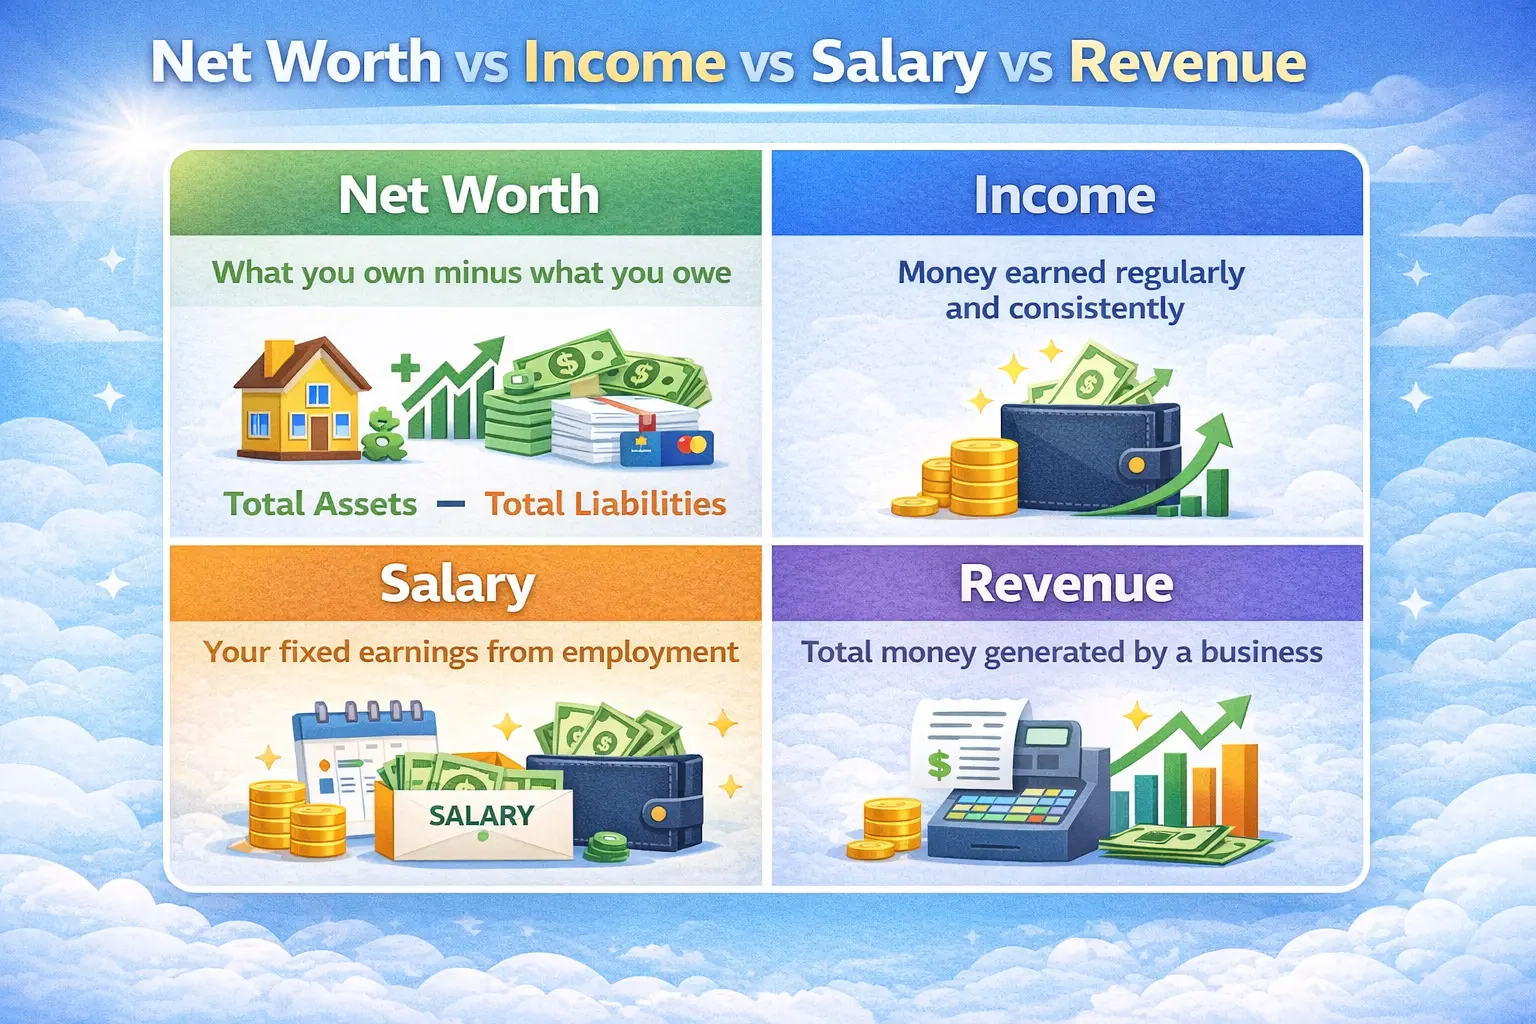
Breaking Down the Numbers
The gap between salary and net worth isn’t just theoretical—it’s structural. A 2023 Federal Reserve report found that the median net worth for U.S. households was $188,200, while the median income was $74,580. The disparity widens with age: a 65-year-old’s net worth is typically 10 times their annual salary, while a 35-year-old’s might only be twice as much. These figures underscore a harsh reality: salary alone doesn’t dictate financial freedom. Someone earning $200,000 a year could be drowning in debt, while a $60,000 earner might own their home outright and have a diversified portfolio. The confusion arises because salary is tangible—it’s the number on the pay stub, the figure used to rent apartments or buy cars. Net worth, by contrast, is abstract until you need to access it. A high salary can mask poor financial habits, while a modest salary can hide generational wealth. The mistake is treating them as interchangeable. A software engineer in Silicon Valley might trade a $150,000 salary for a $120,000 role at a stable firm to reduce living costs and invest the difference. Over a decade, that $30,000 annual sacrifice could add $500,000 to their net worth through compounding. The math isn’t just about the numbers—it’s about the opportunity cost of every decision.The Verified Baseline
Public data confirms that net worth grows far more slowly than salary for most people. According to the U.S. Census Bureau, the top 10% of earners have a median net worth of $1.7 million, while the bottom 50% have just $137,000. Even among high earners, salary doesn’t always translate to wealth. A study by the Economic Policy Institute found that CEOs earn 399 times more than the average worker, yet their net worth often correlates more with stock options and deferred compensation than base salary. The takeaway? Salary is a tool, not a destination. The baseline also reveals that net worth is sticky—it’s harder to lose than salary. A layoff can slash income overnight, but net worth erodes over time through poor decisions. The 2008 financial crisis wiped out $16.4 trillion in household wealth, yet most families recovered within a decade. Salaries, however, bounce back faster. The lesson? Net worth is the buffer; salary is the engine. Neglect one, and the other becomes meaningless.What the Estimates Suggest
Industry estimates paint a nuanced picture. Financial advisors often cite the "salary-to-net-worth ratio" as a health check: for someone under 40, a net worth of 1–2 times their annual salary is considered solid; by 50, it should be 4–7 times. These benchmarks assume disciplined saving, but reality is messier. A 2022 Bankrate survey found that 28% of Americans with incomes over $100,000 had no emergency savings, while 40% of those earning $50,000–$75,000 had six months’ worth. The estimates suggest that what should be more: net worth or salary depends on life stage—but the data also shows that high earners aren’t automatically wealthier. Wealth managers note that the biggest outliers aren’t high salaries but asset allocation and tax efficiency. A doctor earning $300,000 might have a net worth of $1 million if they live frugally and invest wisely, while a Wall Street banker earning $500,000 could have $500,000 in net worth if they spend aggressively and carry debt. The estimates highlight a critical truth: salary is a means to an end, not the end itself. The question then becomes how to optimize the relationship between the two.
Case Study: A Closer Look
Consider the career pivot of Sarah, a 38-year-old marketing director who left a $140,000 role at a Fortune 500 company to join a startup as a fractional CMO for $90,000. On paper, her salary dropped by 36%. But her net worth trajectory shifted dramatically. The startup offered equity, and Sarah reinvested her savings into low-cost index funds. Within three years, her net worth—driven by stock appreciation and reduced living expenses—grew by 120%, even as her salary remained flat. The trade-off wasn’t just financial; it was about control and growth potential. Sarah’s story isn’t unique. Many professionals in creative fields or tech opt for lower salaries to build equity or intellectual property. A freelance designer might take a 40% pay cut to work remotely, but their net worth climbs as they avoid commuting costs and invest the difference. The key variable isn’t the salary itself but how it interacts with spending, saving, and asset accumulation. The table below breaks down the estimated impacts of her decision:| Factor | Estimated Impact |
|---|---|
| Salary Reduction | Immediate 36% drop in annual income, but lower taxable income and flexibility to negotiate future roles. |
| Equity Growth | Startup valuation reportedly tripled in three years; Sarah’s equity stake grew from $50,000 to $300,000 (pre-IPO). |
| Investment Returns | Reinvested savings in S&P 500 index funds yielded ~10% annualized returns, adding ~$80,000 to net worth. |
| Lifestyle Adjustment | Reduced housing costs by 25% through remote work; no car payment after selling her vehicle. |
"She traded a paycheck for ownership. Most people can’t see past the salary number, but she saw the bigger picture—assets, not just income. That’s how you build real wealth."
What This Means Going Forward
The tension between salary and net worth is evolving with remote work, gig economies, and delayed retirement. Traditional career ladders no longer guarantee linear growth. A 2023 McKinsey report found that 40% of workers now prioritize financial flexibility over salary increases, redefining what success looks like. For younger professionals, net worth is becoming the primary metric because it reflects adaptability—something a fixed salary can’t measure. The shift also exposes a generational divide. Millennials and Gen Z are more likely to prioritize net worth over salary because they’ve seen firsthand how economic instability can erase decades of income. The Great Recession taught them that a high salary doesn’t equal security. Meanwhile, older workers often cling to salary as a marker of status, even if it comes at the cost of liquidity. The forward-looking strategy? Align salary with net worth goals, not ego.
Conclusion
The debate over what should be more: net worth or salary isn’t about choosing one over the other—it’s about understanding their roles in a financial ecosystem. Salary is the fuel; net worth is the destination. Ignore one at the expense of the other, and you’re driving with an empty tank. The most successful individuals don’t maximize salary for its own sake; they use it as a tool to build assets, reduce risk, and create options. The answer lies in context. A recent graduate should focus on salary to build experience and credit history. A parent nearing retirement should prioritize net worth to ensure stability. But the underlying principle remains: financial health is a marathon, not a sprint. The numbers don’t lie—net worth is the true measure of progress, while salary is just a milestone along the way.Comprehensive FAQs
Q: Is it better to have a high salary but low net worth?
A: Not necessarily. A high salary can support a lavish lifestyle, but without asset accumulation, it’s unsustainable. Think of it like a fire hose—high pressure is impressive, but if the tank is empty, it won’t last. The goal is to balance income with savings, investments, and debt management so that net worth grows over time.
Q: Can you increase net worth without a high salary?
A: Absolutely. Net worth is determined by assets minus liabilities, not just income. Frugality, strategic investments, and leveraging skills (e.g., freelancing, passive income) can build wealth even on modest salaries. Historically, many millionaires started with average incomes but optimized spending and asset allocation.
Q: Should I take a pay cut for equity or other benefits?
A: It depends on the company’s stability, the equity’s vesting schedule, and your risk tolerance. Equity can be a wealth multiplier if the company succeeds, but it’s illiquid and risky. Always compare the present value of the equity against the salary loss and negotiate for liquidity events (e.g., bonuses tied to milestones) to mitigate risk.
Q: How does debt affect the net worth vs. salary debate?
A: Debt is the wild card. A high salary with manageable debt (e.g., a mortgage) can still build net worth, while a low salary with high-interest debt (e.g., credit cards) will erode it. The rule of thumb: good debt (like a home mortgage) can be an investment; bad debt (consumer debt) is a liability. Prioritize paying off the latter before optimizing salary.
Q: Is net worth more important than salary for early-career professionals?
A: Not initially. Early-career professionals need salary to build skills, credit, and emergency funds. However, even in this stage, small habits—like automating savings, avoiding lifestyle inflation, and investing—can start building net worth. The key is to treat salary as a means to an end, not the end itself.
Q: Can a high net worth hide a low salary, and vice versa?
A: Yes. A retiree with a modest pension but significant home equity and investments might have a high net worth despite a low salary. Conversely, a high earner with no savings, a luxury lifestyle, and debt could have a low net worth. The two metrics tell different stories—one about income, the other about accumulated wealth.
Q: How do taxes play into the net worth vs. salary decision?
A: Taxes can distort the relationship between salary and net worth. A high salary might mean higher tax brackets, reducing take-home pay. Conversely, capital gains (from investments) are often taxed at lower rates than income. Strategies like tax-loss harvesting, retirement contributions, and asset location can optimize how salary translates into net worth growth.
Q: What’s the biggest mistake people make when focusing only on salary?
A: Assuming that higher income equals financial security. Many high earners fall into the "lifestyle creep" trap, where increased spending matches salary bumps, leaving no room for savings or investments. The mistake isn’t earning more—it’s failing to allocate income toward assets that appreciate over time.
