
Where It All Began
The concept of liquidity in wealth measurement predates modern finance, but its formalization as a distinct metric emerged from two parallel crises: the Great Depression and the oil shocks of the 1970s. During the Depression, banks collapsed not because borrowers defaulted, but because assets—stocks, bonds, even real estate—lost their liquidity overnight. A farmer with $100,000 in land might be insolvent if no buyer could be found, even as the land’s theoretical value remained high. Economists like John Maynard Keynes began emphasizing liquidity preference, arguing that money’s true value lies in its convertibility, not its nominal worth. Yet it took decades for this idea to seep into personal finance. The second catalyst was the 1973 oil crisis, which exposed how illiquid assets could strangle even solvent businesses. Companies with vast oil reserves (or contracts) found themselves unable to monetize them fast enough to pay wages or debts. The term "liquid net worth" first appeared in 1975 financial handbooks as a way to distinguish between book value (what assets are worth on paper) and realizable value (what they could fetch in a pinch). Early adopters were commercial lenders, who started requiring borrowers to disclose not just their net worth, but their liquid net worth—the portion they could access within 30–90 days. This wasn’t just a lending tool; it became a filter for financial resilience.The Early Signs
By the 1980s, the distinction between liquid net worth and total net worth became a de facto standard in high-net-worth circles. Wealth managers noticed a pattern: clients with identical total net worths behaved radically differently during downturns. One group, with 70% of their wealth in liquid form, could ride out market volatility; the other, with 90% tied to private equity or real estate, faced forced sales at fire-sale prices. The lesson was simple: Liquidity wasn’t a luxury—it was the difference between recovery and ruin. The 1990s tech boom amplified this divide. Dot-com founders with inflated stock options (illiquid) crashed harder than those with diversified cash reserves. When the bubble burst in 2000, the survivors were those who’d heeded an emerging rule of thumb: Maintain at least 20–30% of your net worth in assets you can access without penalty. This wasn’t just about safety; it was about opportunity. Liquid wealth meant the ability to snap up distressed assets, pivot careers, or weather personal crises without selling at a loss.The Turning Point
The moment liquid net worth stopped being a niche concern and became a mainstream financial obsession was September 15, 2008. When Lehman Brothers collapsed, it wasn’t just a bank failure—it was a liquidity event. Overnight, assets that had been trading at premiums became toxic paper. A hedge fund manager with $1 billion in illiquid private equity found himself staring at a $200 million hole because no buyer would touch his positions. The lesson was brutal: Total net worth is a snapshot; liquid net worth is a stress test. The aftermath saw a quiet revolution in personal finance. Wealth managers began segmenting clients by liquidity tiers, not just by total assets. A family with $50 million in real estate but only $5 million in cash was treated as high-risk, even if their paper net worth was higher than a peer with $40 million in liquid assets. The shift wasn’t just about numbers—it was about behavior. People realized that what "liquid net worth mean" wasn’t just about emergencies; it was about control. You could have a mansion, a yacht, and a portfolio of blue-chip stocks, but if you couldn’t sell any of them without losing 30% of their value, you were financially hostage."We used to tell clients, ‘Don’t worry, your assets will recover.’ Then 2008 happened. Now we say, ‘Your assets might recover, but if you can’t touch them, you’re already lost.’ That’s when we started obsessing over liquid net worth—not as an afterthought, but as the foundation." — Jane Chen, Partner at Blackstone Alternative Asset Management (2010 interview)The turning point wasn’t just institutional. By 2012, robo-advisors and fintech platforms began automatically calculating liquid net worth alongside traditional metrics. Apps like Betterment and Wealthfront started flagging accounts where less than 15% of assets were liquid, prompting users to adjust. The message was clear: If your net worth isn’t liquid, it’s not working for you.
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2008–2012 | Post-crisis, hedge funds and private equity firms began requiring minimum liquidity ratios for new investments. The Liquid Net Worth Rule emerged: No more than 40% of a portfolio could be illiquid without a pre-arranged exit strategy. Meanwhile, individuals started lump-sum withdrawals from 401(k)s to boost liquidity—though this often backfired due to penalties and tax hits. |
| 2013–2017 | The rise of crowdfunding and peer-to-peer lending introduced new liquidity tiers. Assets like real estate crowdfunding shares were marketed as "liquid," but redemption periods of 6–12 months exposed the gap between marketing claims and actual liquidity. During this period, financial advisors coined the term "liquidity pyramid"—ranking assets from cash (most liquid) to collectibles (least liquid). |
| 2018–Present | The COVID-19 pandemic became the ultimate stress test for liquid net worth. Small businesses with low liquid reserves collapsed within months, while individuals with 3–6 months of expenses in cash weathered lockdowns. Post-pandemic, crypto and NFTs introduced new illiquidity risks: assets that traded at $100 million could become worthless overnight. Meanwhile, ESG investing added complexity—green bonds and impact funds often had lock-up periods of 5+ years, forcing investors to rethink liquidity trade-offs. |
Lessons From the Journey
- Liquidity isn’t static. What’s liquid today (e.g., a high-yield savings account) can become illiquid tomorrow if regulations change (e.g., bank freezes during a crisis).
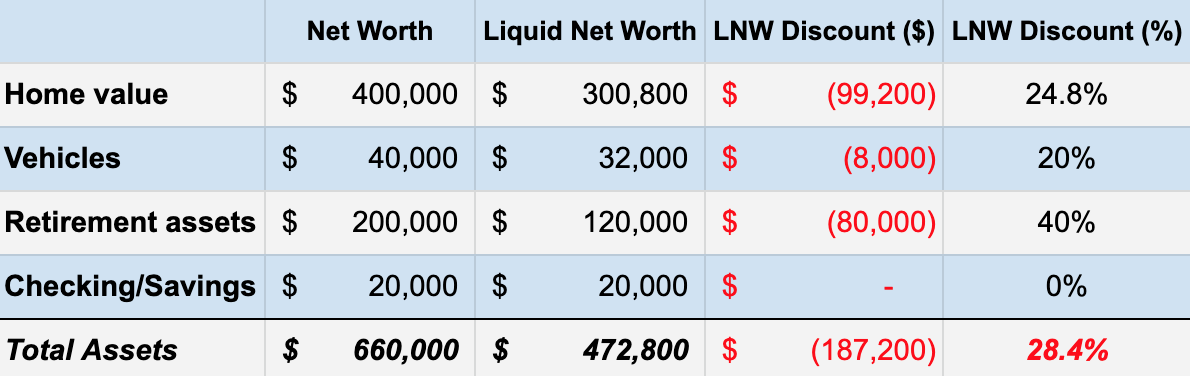
- Illiquid assets aren’t inherently bad—just risky. Real estate, private equity, and art can preserve wealth long-term, but they demand a dedicated liquid buffer (typically 20–40% of total net worth) to absorb volatility.
- Taxes and penalties erode liquidity. Selling a 401(k) early or breaking a CD can turn a $1 million asset into $700,000 after fees. True liquidity accounts for these costs.
- Psychology matters more than math. Many high-net-worth individuals avoid liquidity because it feels "boring." But during crises, cash isn’t boring—it’s survival.
- Liquidity begets opportunity. The ability to act fast—whether buying a distressed asset, funding a new venture, or covering a family emergency—is the real ROI of liquid net worth.
Where Things Stand Today
Today, liquid net worth isn’t just a financial metric—it’s a lifestyle filter. The ultra-wealthy don’t just track it; they engineer it. A $100 million portfolio with $30 million in liquid assets is treated differently than one with $5 million liquid, even if the total is identical. The difference? Optionality. The first can pivot industries, weather lawsuits, or seize opportunities without selling at a loss. The second is one crisis away from a fire sale. The shift has also democratized in unexpected ways. Fintech tools now let middle-class earners simulate liquid net worth scenarios. Apps like Mint and YNAB automatically categorize assets by liquidity, while robo-advisors now offer "liquidity sliders" to adjust risk profiles. Even student debtors are learning that total net worth means little if it’s not liquid—a lesson driven home by COVID-era eviction moratoriums, where homeowners with equity couldn’t access it fast enough to save their businesses. Yet the biggest change is cultural. The stigma around holding cash has faded. Where once liquidity was seen as "missing out on growth," today it’s recognized as the ultimate growth enabler. The question isn’t "How much do I have?" but "How much can I use when it matters?" That’s what liquid net worth mean in 2024—and why it’s reshaping how we think about money, not just how we manage it.
Conclusion
The evolution of liquid net worth reflects a fundamental truth: Wealth isn’t just about owning things—it’s about owning *options. The entrepreneur who lost his fortune in 2008 didn’t fail because he spent too much; he failed because he mistook paper wealth for real wealth. The lesson wasn’t to hoard cash at all costs, but to balance ambition with agility. Illiquid assets build legacies; liquid assets buy time. As markets grow more volatile and personal finances more unpredictable, the real question isn’t "What’s my net worth?" but "What can I actually do with it?" That’s the gap that liquid net worth measures—and the gap that separates financial security from financial fiction.Comprehensive FAQs
Q: How do I calculate my liquid net worth?
To determine what "liquid net worth mean" for you, start by listing all assets you can convert to cash within 30–90 days without penalties. This includes:
- Cash in checking/savings accounts
- Money market funds
- Short-term Treasury bills (4-week to 1-year)
- Highly liquid stocks/ETFs (no restrictions)
- Certificates of deposit (CDs) only if rolling over or breaking early is feasible
- Prepaid expenses (e.g., insurance policies with cash surrender value)
- Real estate (unless you’re selling in a hot market with no contingencies)
- Private equity, venture capital, or restricted stock
- Collectibles (art, cars, wine) unless you have a pre-sold buyer
- Retirement accounts (401(k)s, IRAs) unless you’re over 59½ or face minimal penalties
Q: Why does liquid net worth matter more than total net worth?
Total net worth is a snapshot; liquid net worth is a stress test. Consider two scenarios:
- A doctor with $2 million in a practice (illiquid) and $500K in cash faces a $1M malpractice suit. If the practice sells for $1.2M after fees, they’re underwater—even though their total net worth was $2.5M.
- A freelancer with $1.5M in stocks/ETFs (liquid) and $300K in cash loses their primary income source. They can cover 6 months of expenses without selling assets at a loss.
Q: Can I artificially inflate my liquid net worth before a major expense (e.g., buying a house, starting a business)?
Yes, but strategically—and with caution. Common (and risky) tactics include:
- Selling illiquid assets (e.g., breaking a CD early, liquidating a portion of a 401(k) with penalties).
- Taking a hardship withdrawal from retirement accounts (taxes + 10% penalty apply if under 59½).
- Using a home equity line of credit (HELOC) as a liquidity buffer (but this adds debt risk).
- Delaying tax payments (IRS penalties apply if not repaid within a year).
- Increase liquid assets gradually (e.g., allocate a portion of investment gains to cash).
- Negotiate payment terms (e.g., seller financing for real estate).
- Use a bridge loan (short-term, high-interest but avoids selling assets).
Q: How much of my net worth should be liquid?
There’s no one-size-fits-all answer, but industry benchmarks provide a framework:
- Emergency Fund Baseline: 3–6 months of living expenses (the absolute minimum for most people).
- Moderate Risk Tolerance: 15–25% of total net worth in liquid assets.
- High Net Worth ( HNWI ): 20–40% (to cover taxes, lawsuits, or business opportunities).
- Ultra-High Net Worth (UHNWI): 30–50%+ (often held in liquid alternatives like private credit or hedge funds with quick redemption).
- Entrepreneurs/Investors: 40–60% (to exploit market downturns or fund new ventures).
- Your income volatility (freelancers need more liquidity than salaried employees).
- Your asset concentration (if 80% of your wealth is in one stock or property, boost liquidity).
- Your age and health (older individuals or those with family obligations need higher buffers).
- Your risk appetite (conservative? Aim for 30%+ liquid. Aggressive? 15–20% may suffice if you have diversified illiquid assets with exit strategies).
Q: What are the biggest myths about liquid net worth?
- "More liquidity means lower returns." Reality: While cash earns near-zero interest, true liquidity isn’t just cash—it’s assets you can access without fire-sale penalties. A short-term Treasury bond (liquid) yields ~4–5%, while a long-term bond (illiquid) might yield 3% but lock you in for 10 years. The trade-off isn’t liquidity vs. returns; it’s liquidity vs. risk of being locked in during a downturn.
- "I don’t need liquidity if I have a high-paying job." Reality: Job security is an illusion. A single layoff, industry shift, or health issue can wipe out savings. Even top executives lose jobs—20% of Fortune 500 CEOs are replaced annually. Liquidity isn’t about fear; it’s about optionality.
- "Real estate is liquid if I can sell it quickly." Reality: In most markets, selling a home takes 3–6 months—and that’s without contingencies (inspection failures, appraisal gaps). During a crash, distressed sales can take 1–2 years. If you need cash in 30 days, real estate doesn’t count as liquid.
- "Crypto is highly liquid." Reality: While Bitcoin and Ethereum trade 24/7, exchange collapses (e.g., FTX), regulatory freezes, or network congestion can lock you out. NFTs and altcoins are far less liquid—some haven’t traded in years. If you can’t withdraw your crypto to cash within 48 hours, it’s not liquid.
- "I’ll just borrow against my assets if I need liquidity." Reality: Debt is the opposite of liquidity. A HELOC or margin loan might give you cash today, but interest rates, collateral risks, and repayment terms can turn a temporary fix into a crisis. If you’re relying on debt for liquidity, you’ve already lost the game.
Q: How can I increase my liquid net worth without selling assets?
If you’re reluctant to sell illiquid assets, try these low-impact strategies:
- Reallocate a portion of future income. Example: If you save $5K/month, divert $1K to high-yield savings (currently ~4.5% APY) instead of investing it all.
- Use a "liquidity ladder" with CDs or Treasury bills. Stagger maturities (e.g., 3-month, 6-month, 1-year) so some cash is always available without penalties.
-
Negotiate better terms on illiquid assets. Example:
- Private equity: Request quarterly redemption rights (some funds offer 5–10% liquidity per quarter).
- Real estate: Structure a sell-to-leaseback (sell property but lease it back for income).
- Restricted stock: Check if your company offers early exercise programs (with penalties).
-
Leverage "semi-liquid" assets. Example:
- Whole life insurance policies with cash surrender value (takes 30–60 days to access).
- Prepaid college tuition plans (some states allow partial withdrawals with penalties).
- Peer-to-peer lending platforms (e.g., Prosper, LendingClub) where you can sell notes early (but with fees).
-
Reduce illiquid liabilities. Example:
- Refinance a mortgage to free up cash flow.
- Pay off high-interest debt (credit cards, personal loans) to unlock future borrowing power.
- Downsize real estate (sell a vacation home, move to a cheaper property).
Q: What’s the difference between liquid net worth and cash flow?
Liquid net worth and cash flow are related but distinct:
- Liquid Net Worth = Assets you can access quickly (cash, liquid investments) minus liabilities you can pay quickly (credit cards, short-term loans).
- Cash Flow = Income minus expenses over a specific period (monthly, annually).
