
Common Myths About What Is the Net Worth of Middle Class
The middle-class net worth debate is riddled with oversimplifications. One persistent myth frames it as a universal benchmark, ignoring how cultural norms and economic structures distort the picture. Another assumes net worth grows linearly with income, overlooking the role of inheritance, luck, or systemic barriers. These misconceptions aren’t harmless—they shape everything from tax policy to personal financial goals. Take the idea that the middle class is a monolith with a single net worth threshold. In reality, the range varies wildly. A 2022 Pew Research study found that U.S. households in the middle income tier (defined by income, not assets) had median net worths spanning from $25,000 for Black households to $188,000 for white households. Even within racial groups, regional disparities emerge: a middle-class family in rural Ohio might have a net worth tied to farmland, while one in urban California relies on tech stocks or high-cost real estate. The myth of uniformity obscures how geography, race, and education intersect to define wealth. Another falsehood suggests that middle-class net worth is purely a function of hard work. While discipline matters, structural factors like healthcare costs, tuition hikes, or employer pension cuts can derail even the most diligent savers. A nurse earning $70,000 might have a net worth of $100,000 after decades of service, while a software engineer with the same income could hit $1 million if they started earlier or benefited from stock options. The narrative that wealth is earned equally overlooks the head start granted by family wealth, inheritance, or access to high-paying industries.Myth 1: The Middle Class Has a Single, Universal Net Worth Threshold
The notion that what is the net worth of middle class can be pinned to one number ignores the global variance. In Sweden, where strong social safety nets reduce asset dependence, middle-class households might have net worths clustered around €200,000–€500,000 due to universal healthcare and education. Meanwhile, in India, a middle-class family in Mumbai could have a net worth of ₹50 lakh (about $60,000) while one in a tier-3 city might struggle to cross ₹5 lakh ($6,000). Even within the U.S., the Federal Reserve’s Survey of Consumer Finances shows median net worth for the middle 60% of households ranges from $120,000 in the bottom quartile to $1.2 million in the top quartile of that group. The confusion stems from conflating income with wealth. Income measures annual cash flow; net worth reflects accumulated assets minus debts. A teacher earning $60,000 might have a net worth of $80,000 after saving for a decade, while a salesperson earning $120,000 could have $20,000 in debt and no savings. Policymakers often focus on income when crafting middle-class support, but net worth determines resilience during crises—like the 2008 crash, when middle-class homeowners with high mortgages faced foreclosure while those with equity weathered the storm.Myth 2: Middle-Class Net Worth Grows Steadily with Age
The assumption that what the net worth of middle class looks like follows a predictable arc—peaking in retirement—is outdated. For younger generations, stagnant wages and rising costs have flattened trajectories. A 2023 Brookings Institution report found that Gen Z and Millennials aged 25–34 had median net worths 30% lower than their Gen X counterparts at the same age, adjusted for inflation. Student debt plays a role, but so does the collapse of defined-benefit pensions, which once guaranteed middle-class security. Today, many middle-class workers rely on 401(k)s, whose performance hinges on market volatility—a gamble their parents didn’t face. Even for older cohorts, the picture isn’t linear. The pandemic exposed how middle-class net worth can plummet overnight. A 2021 study by the Urban Institute showed that 40% of middle-income households saw their net worth drop by at least 20% during COVID-19, largely due to job losses or medical expenses. Meanwhile, those who owned homes in booming markets (like Phoenix or Austin) saw net worths surge. The myth of steady accumulation ignores how external shocks—recessions, healthcare crises, or even natural disasters—can reset progress overnight.Myth 3: Homeownership Alone Defines Middle-Class Net Worth
Real estate is often treated as the cornerstone of middle-class wealth, but ownership doesn’t guarantee financial stability. In cities like Los Angeles or New York, a middle-class family might spend 60% of their income on a $800,000 home, leaving little for savings or emergencies. Their net worth might appear high on paper, but liquidity is low. Conversely, renters in the same cities could have higher net worths if they’ve invested in index funds or avoided mortgage debt. A 2022 Harvard Joint Center for Housing Studies report found that 37% of middle-income renters had net worths exceeding those of lower-income homeowners—proof that housing equity isn’t the only path to wealth. The obsession with homeownership also masks regional disparities. In Detroit, a middle-class family might own a $100,000 home outright, giving them a net worth boost. In San Francisco, the same family would need a $1.5 million mortgage to live comparably, leaving them house-poor. The myth that ownership equals security ignores how leverage, maintenance costs, and property taxes can erode net worth over time. For many, the "American Dream" of home equity has become a double-edged sword: a source of wealth for some, a debt trap for others.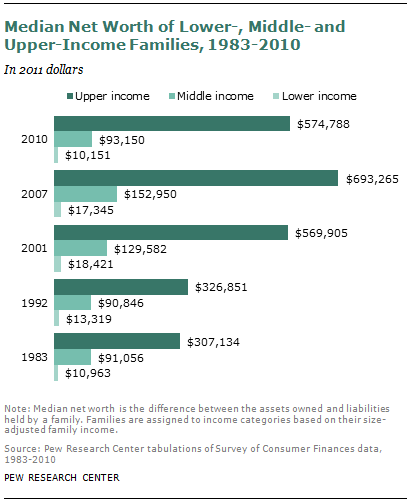
What Holds Up to Scrutiny
When stripping away myths, three verifiable truths emerge about what the net worth of middle class actually represents. First, it’s not a static number but a moving target influenced by inflation, wage growth, and policy changes. Second, asset composition matters more than the total—a family with a paid-off home and no debt is far more secure than one with high-liquidity investments but crushing loans. Third, middle-class net worth is increasingly tied to education and location, with college graduates and urban/suburban residents consistently outpacing their peers. The data also reveals that what the evidence says about middle-class net worth often contradicts popular perception. For example, while many assume the middle class is asset-rich, Federal Reserve figures show that 40% of middle-income households have zero or negative net worth. This isn’t just a U.S. phenomenon; in the UK, the Resolution Foundation reports that one-third of middle-income households have savings below £10,000. The reality is that for a significant portion, middle-class status is more about income stability than wealth accumulation."Middle-class wealth isn’t just about how much you have—it’s about how much you can protect in a crisis. The families who survive economic shocks are the ones who’ve built buffers, not just balances." — Edward N. Wolff, Professor of Economics at NYU and author of The Assets of the American Middle Class
| Common Belief | What the Evidence Says |
|---|---|
| The middle class has a net worth of $100,000–$200,000. | Median net worth varies by age, race, and region—ranging from $25,000 (Black households) to $1.2 million (top middle-income quartile). |
| Middle-class net worth grows predictably with age. | Gen Z/Millennials have 30% lower net worth than prior generations at the same age, due to debt and wage stagnation. |
| Homeownership guarantees middle-class security. | Renters in high-cost areas often have higher net worths than homeowners with leveraged properties. |
| The middle class is uniformly asset-rich. | 40% of middle-income U.S. households have zero or negative net worth, per Federal Reserve data. |
| Net worth and income are closely correlated. | A $100,000 earner could have $50,000 in net worth (debt-heavy) or $500,000 (asset-rich). |
Why the Confusion Persists
The debate over what is the net worth of middle class remains muddled because the term itself is politically charged. Conservatives often tie middle-class status to homeownership and stock portfolios, while progressives highlight stagnant wages and debt burdens. This ideological tug-of-war obscures the data. Meanwhile, institutions like the Census Bureau and Federal Reserve use different methodologies—some focusing on income, others on assets—which creates conflicting narratives. Cultural narratives also play a role. The myth of the "self-made" middle-class family ignores how wealth is often inherited or luck-based. Studies show that 60% of wealth accumulation comes from inheritance or gifts, not salaries. Yet public discourse frames success as purely individual, making it harder to acknowledge systemic barriers. Add to this the rise of "quiet luxury" marketing, which redefines middle-class aspirations upward, and the confusion deepens. What was once considered comfortable—owning a home, saving for retirement—now feels like a minimum, pushing net worth benchmarks higher without corresponding wage growth.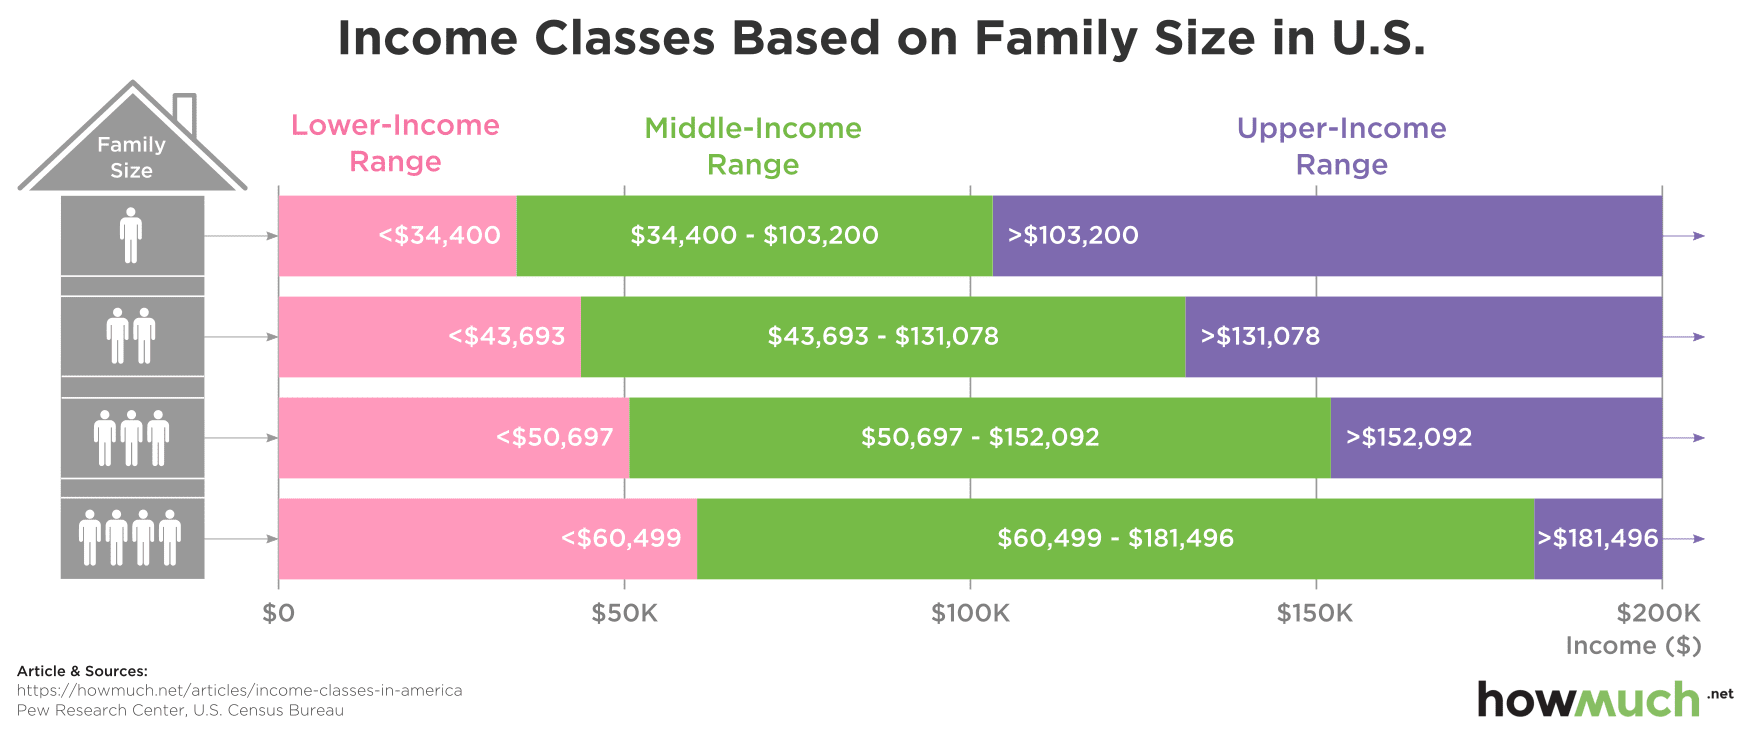
Conclusion
The question of what the net worth of middle class truly is has no single answer, but the data provides a clearer framework. Middle-class wealth is less about a fixed number and more about resilience: the ability to weather job loss, healthcare crises, or market downturns without spiraling into poverty. For some, that means a $150,000 net worth in a low-cost area; for others, it’s a $1 million portfolio in a high-tax state. The key is recognizing that net worth isn’t just a balance sheet—it’s a reflection of opportunity. Moving forward, the conversation must shift from defining middle-class net worth to protecting it. Policies that expand access to education, reduce healthcare costs, and reform student debt could lift millions into sustainable wealth. Individually, middle-class families should focus on liquidity over leverage—prioritizing emergency funds and diversified assets over mortgages or high-risk investments. The goal isn’t to hit an arbitrary number but to build a cushion that outlasts economic cycles. In an era of widening inequality, understanding what is the net worth of middle class isn’t just about personal finance—it’s about collective economic health.Comprehensive FAQs
Q: How does middle-class net worth compare globally?
The U.S. middle-class median net worth is often cited around $120,000–$1.2 million, but in countries like Germany or Japan, it’s tied to social welfare systems, with figures closer to €300,000–€600,000. In emerging markets like Brazil or India, middle-class net worths cluster around $20,000–$100,000, heavily influenced by homeownership and informal savings.
Q: Does student debt significantly lower middle-class net worth?
Absolutely. A 2023 Federal Reserve report found that households with student debt had 40% lower median net worth than those without. For Millennials, student loans reduced their net worth by an estimated $35,000 on average compared to peers without debt. The impact is even sharper for Black and Hispanic borrowers, who face higher default rates.
Q: Can you be middle-class with a negative net worth?
Yes, but it’s precarious. About 15% of middle-income U.S. households have negative net worth due to high debt (mortgages, credit cards, student loans) with little in assets. These families rely on income stability to avoid crisis, making them vulnerable to economic shocks. True middle-class security requires moving into positive net worth territory.
Q: How does homeownership affect middle-class net worth?
Homeownership can boost net worth by 30–40% annually in appreciating markets, but it’s a double-edged sword. Middle-class homeowners with mortgages may see their net worth rise on paper, but high monthly costs can limit other savings. Renters, meanwhile, may invest in stocks or bonds, achieving similar long-term growth without the risk of foreclosure.
Q: Is middle-class net worth higher in rural or urban areas?
Urban areas often have higher median net worths due to higher incomes and investment opportunities, but rural middle-class families may have more stable wealth tied to land or small businesses. A 2022 study found that rural middle-class households had 10–15% lower net worths than urban peers, partly due to lower wage growth and fewer asset diversification options.
Q: How does age impact middle-class net worth?
Net worth typically peaks in the 55–64 age range, with median values around $250,000–$500,000. Younger middle-class adults (under 35) often have net worths below $50,000, while those 35–44 see a sharp increase as mortgages are paid down and careers advance. However, Gen Z and Millennials are bucking this trend due to stagnant wages and debt.
Q: What’s the biggest threat to middle-class net worth today?
Inflation and healthcare costs are the top threats. A 2023 McKinsey report found that 60% of middle-class households spend at least 20% of income on healthcare, leaving less for savings. Meanwhile, inflation erodes purchasing power—wages have grown just 5% since 2000, while housing and education costs have surged 150%+ in the same period.
Q: Can policy changes actually increase middle-class net worth?
Yes, but it requires targeted interventions. Expanding access to employer-sponsored retirement plans, capping student loan interest rates, and reforming healthcare to reduce out-of-pocket costs could collectively add $50,000–$100,000 to middle-class net worths over a decade. Countries like Denmark and Sweden demonstrate how strong social safety nets can stabilize wealth without stifling growth.
