The Complete Overview of What Is the Difference Between Net Worth and Cash Flow
Net worth is the foundational metric of wealth assessment, calculated by subtracting total liabilities from total assets. It’s a static measure—a single data point that answers the question, "What would I have left if I sold everything today and paid off all debts?" This figure is critical for lenders, tax authorities, and individuals evaluating long-term financial standing. However, it ignores how money flows through an economy or a household. A retiree with a $2 million net worth might live comfortably if their investments generate $100,000 annually in dividends and rental income. But if those income streams vanish, the net worth becomes irrelevant without liquidity. Cash flow, by contrast, is dynamic and time-sensitive. It measures the actual inflows and outflows of money over a specific period—daily, monthly, or annually. Positive cash flow means more money is coming in than going out; negative cash flow signals trouble, even if net worth remains high. A startup might have a net worth of zero (no assets, no debt) but still thrive if it generates consistent positive cash flow from pre-sales or subscriptions. Conversely, a mature company with billions in assets can collapse if operating expenses exceed revenue. The distinction between these two metrics explains why some high-net-worth individuals face bankruptcy while others with modest savings build generational wealth.Historical Background and Evolution
The concept of net worth traces back to medieval accounting practices, where merchants recorded assets and debts in ledgers to assess solvency. By the 18th century, personal balance sheets became standard for European aristocracy and early industrialists, evolving alongside the rise of credit systems. The term "net worth" gained prominence in the 19th century as railroads and manufacturing required substantial capital investments, forcing businesses to quantify their financial positions. For individuals, net worth became a marker of social status—visible in property ownership and public records. Cash flow, as a distinct financial metric, emerged later, tied to the industrial revolution’s need for liquidity management. Factories required consistent working capital to pay wages and purchase raw materials, even if long-term assets (like machinery) appreciated over time. The 20th century formalized cash flow analysis with the advent of corporate financial reporting, particularly after the Great Depression exposed the dangers of relying solely on net worth. Modern personal finance, influenced by behavioral economics, now treats cash flow as the true indicator of financial health, not just net worth. The 2008 financial crisis further reinforced this shift, as many households with high net worth (e.g., leveraged real estate) faced liquidity crises when asset values plummeted.Core Mechanisms: How It Works
Net worth is calculated using a straightforward formula: Net Worth = Total Assets – Total Liabilities Assets include cash, investments, real estate, and personal property, while liabilities cover mortgages, loans, credit card debt, and other obligations. The result is a single number that doesn’t change unless assets or debts are adjusted. For example, if someone owns a $500,000 home with a $300,000 mortgage, $100,000 in stocks, and $5,000 in cash, their net worth is $205,000. This figure is useful for estate planning, inheritance calculations, and creditworthiness assessments, but it doesn’t reveal whether they can cover next month’s expenses. Cash flow, however, is a time-based measurement requiring periodic tracking. It’s divided into two primary categories: 1. Operating Cash Flow: Money generated from core business activities or personal income (salaries, freelance work, rental income). 2. Investing Cash Flow: Funds used for or generated by investments (buying/selling assets, capital expenditures). 3. Financing Cash Flow: Cash from borrowing or repaying debt (loans, dividends, stock buybacks). A freelance graphic designer might report $8,000 in operating cash flow (invoices paid) but $6,000 in expenses (software, taxes, personal spending), resulting in a net positive cash flow of $2,000 for the month. Meanwhile, their net worth might be $150,000, but without consistent positive cash flow, they can’t sustain long-term growth or handle emergencies. The key insight is that what is the difference between net worth and cash flow boils down to stock vs. flow: one is a snapshot, the other is a river.Key Benefits and Crucial Impact
Understanding what is the difference between net worth and cash flow transforms how individuals and organizations approach financial planning. For investors, net worth provides a benchmark for portfolio performance, while cash flow dictates whether they can deploy capital when opportunities arise. A family with a net worth of $1 million but negative cash flow may struggle to send children to college or cover medical bills, despite their paper wealth. Conversely, a couple with a net worth of $300,000 but disciplined cash flow management could retire in 10 years by reinvesting surpluses. The interplay between these metrics also shapes economic policy. Governments use net worth data to assess wealth inequality, while monitoring cash flow helps predict recessions. Central banks, for instance, track corporate cash flow to determine liquidity risks in financial markets. At the personal level, the distinction explains why some high-earners go bankrupt: they may have a high net worth but poor cash flow discipline, leading to debt spirals."Wealth is the quantity of things you own. Cash flow is the rate at which those things generate income—or the rate at which they drain your resources." — Robert Kiyosaki, Rich Dad Poor Dad
Major Advantages
- Net worth provides a clear wealth benchmark for long-term goals like retirement or legacy planning.
- Cash flow reveals operational sustainability, critical for businesses and individuals facing recurring expenses.
- Combining both metrics allows for stress testing: Can you maintain cash flow if assets depreciate?
- Net worth is easier to calculate but can be misleading without context (e.g., illiquid assets like art).
- Cash flow is actionable: Improving it requires behavioral changes (budgeting, income streams).
- Investors use net worth to evaluate portfolio growth, while cash flow determines investment capacity.
Comparative Analysis
| Net Worth | Cash Flow |
|---|---|
| Static measurement (single point in time) | Dynamic measurement (over time) |
| Focuses on assets and liabilities | Focuses on income and expenses |
| Used for credit scoring, estate planning | Used for budgeting, liquidity management |
Future Trends and Innovations
The rise of real-time financial tracking tools—like apps that sync bank accounts, investments, and expenses—is blurring the lines between net worth and cash flow monitoring. These platforms now offer predictive cash flow analysis, estimating future liquidity based on spending patterns and asset performance. For businesses, automated cash flow forecasting using AI is becoming standard, allowing companies to anticipate shortfalls before they occur. Another trend is the gig economy’s impact on cash flow volatility. Freelancers and contract workers often have high net worth from asset accumulation but face unpredictable income streams, forcing them to prioritize cash flow management over traditional net worth growth. Meanwhile, cryptocurrency and decentralized finance (DeFi) introduce new complexities: assets like Bitcoin may have high net worth but poor liquidity, while staking yields create irregular cash flow. The future of financial literacy will likely emphasize integrating both metrics into holistic wealth strategies, rather than treating them as separate concerns.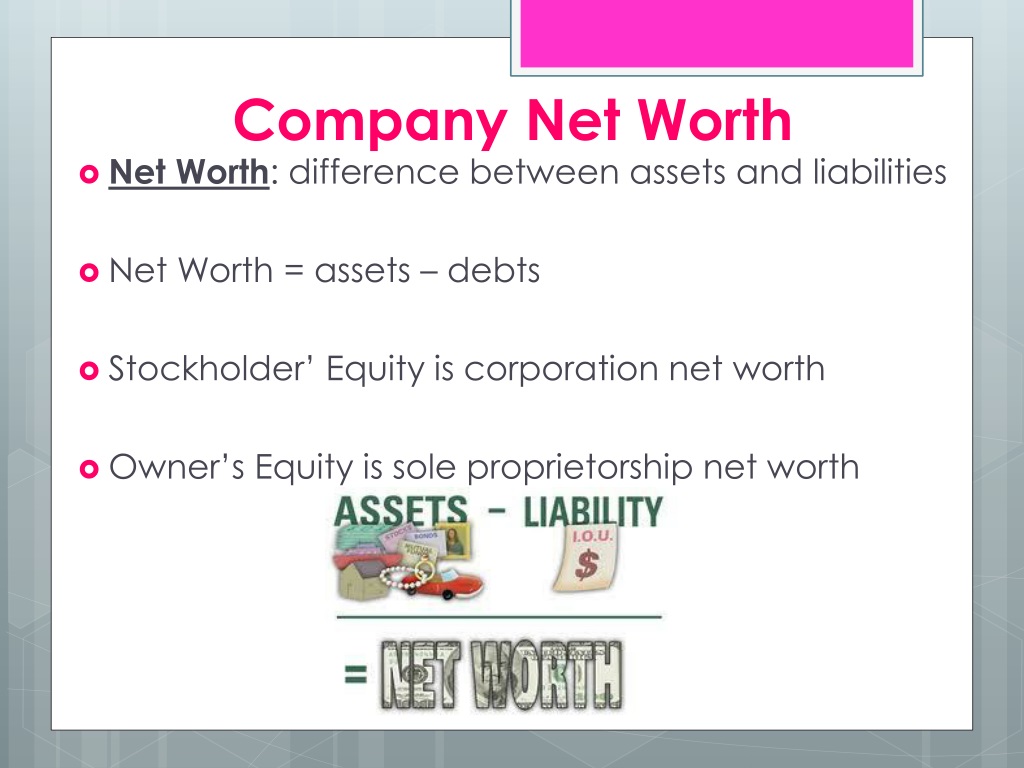
Conclusion
What is the difference between net worth and cash flow? The answer lies in their fundamental roles: one measures what you have, the other measures what you can do with it. A high net worth without positive cash flow is like a castle with no drawbridge—impressive but defenseless. Conversely, strong cash flow without asset growth is like a river without a delta: it keeps moving but never builds lasting value. The most resilient financial strategies balance both, ensuring liquidity today while securing wealth tomorrow. For individuals, this means tracking net worth annually while managing cash flow monthly. For businesses, it requires aligning asset allocation with revenue cycles. The lesson is clear: wealth is not just a number on paper—it’s the ability to convert that number into actionable resources. Ignoring either metric risks financial instability, whether in personal finances or global markets.Comprehensive FAQs
Q: Can someone have a high net worth but negative cash flow?
A: Yes. A classic example is a homeowner with a mortgage who owns expensive assets (e.g., real estate, stocks) but lives beyond their income. Their net worth might be high, but if monthly expenses exceed cash inflows, they face a liquidity crisis. This is common among retirees relying on depreciating assets for income.
Q: How do businesses prioritize net worth vs. cash flow?
A: Startups focus on cash flow to survive, while mature companies optimize net worth for shareholder value. Public firms report both in financial statements: cash flow determines quarterly earnings, while net worth influences stock prices. Private businesses often prioritize cash flow to avoid insolvency, even if assets appreciate slowly.
Q: Does improving cash flow always increase net worth?
A: Not directly. Positive cash flow can fund investments (e.g., buying stocks, paying down debt), which may increase net worth over time. However, cash flow surpluses spent on non-assets (e.g., luxury purchases) won’t boost net worth. The key is reinvesting cash flow into appreciating assets or reducing liabilities.
Q: Why do some financial advisors ignore cash flow?
A: Some advisors, particularly those focused on long-term investing, prioritize net worth because it reflects portfolio growth. However, this approach can lead to over-leveraging or illiquidity risks. Modern advisors increasingly integrate cash flow analysis to assess real-world financial resilience, not just paper wealth.
Q: How can individuals track both metrics simultaneously?
A: Use financial software that syncs accounts (e.g., YNAB, Mint) to monitor net worth and cash flow in real time. For deeper analysis, tools like Personal Capital or Tiller Money categorize transactions while calculating asset valuations. Manual tracking via spreadsheets is also effective for those with complex financial structures.
Q: What’s the biggest mistake people make when focusing only on net worth?
A: Assuming liquidity is guaranteed. A high net worth from illiquid assets (e.g., art, private equity) can’t cover emergencies. Many high-net-worth individuals face crises because they forgot cash flow is the bridge between assets and actual spending power. The 2008 housing crash exposed this flaw when leveraged real estate owners couldn’t sell properties fast enough to meet obligations.
Q: Can cash flow be negative while net worth grows?
A: Yes, if liabilities increase faster than assets. For example, a business taking on debt to expand might report negative cash flow in the short term but see net worth rise if the expansion boosts asset values. However, this strategy is high-risk without a clear path to positive cash flow recovery.
