The Short Answers
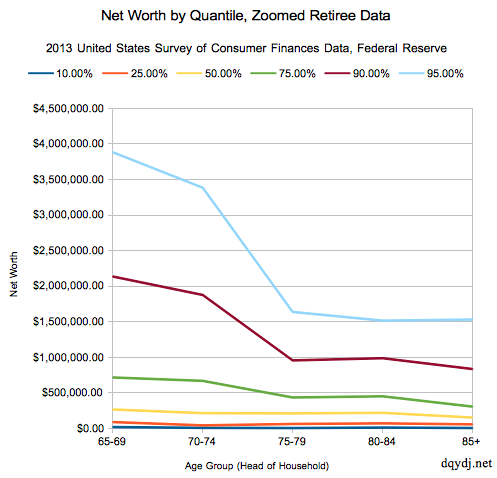
- U.S. retirees: Median net worth is estimated at $280,000 (Fed data), but the top 10% hold over $1.5 million, while the bottom 40% have less than $100,000.
- Home equity inflates averages—excluding it cuts median net worth by nearly 50% for many retirees.
- Public pension systems (e.g., Sweden, Canada) reduce reliance on personal savings, lowering the "average" net worth gap.
- Geography matters: Retirees in high-cost states (California, New York) need significantly more savings than those in low-cost areas.
- Debt in retirement (e.g., medical bills, reverse mortgages) can drag net worth negative, even for those who appeared "prepared."

Deep Dive: The Full Picture
The first mistake in discussing what is the average net worth of retirees is assuming the term "average" means anything useful. Statisticians know this: averages smooth over outliers, hiding the true distribution of wealth. The median—a better measure of central tendency—paints a clearer picture, but even that varies wildly by demographic. For example, retiree couples in the U.S. have a median net worth nearly double that of single retirees, largely because dual incomes and combined Social Security benefits create a financial cushion. Race and ethnicity further skew the data: Black and Hispanic retirees, on average, have net worths less than half those of white retirees, a disparity rooted in historical wealth gaps, wage discrimination, and limited access to homeownership. The second distortion comes from conflating net worth with retirement readiness. A retiree with $500,000 in a tax-deferred IRA may face steep required minimum distributions (RMDs) that push them into higher tax brackets, effectively reducing their liquidity. Conversely, a retiree with $300,000 in cash and bonds might have more flexibility to weather market downturns. The answer to what is the average net worth of retirees thus requires context: Is the question about total assets, spendable income, or resilience against unexpected expenses? The numbers alone don’t tell you whether someone can afford assisted living, travel, or simply cover groceries for 20 years.The Context You Need
To understand what is the average net worth of retirees, you must account for the three-legged stool of retirement income: savings, pensions, and Social Security. In the U.S., defined-benefit pensions—once the backbone of retirement security—have all but vanished for new workers. Today, defined-contribution plans (401(k)s, IRAs) dominate, shifting risk onto individuals. This shift explains why net worth figures for retirees born before 1960 (the "pension generation") look far healthier than those for Millennials, who may never achieve comparable balances. Meanwhile, Social Security replaces only about 40% of pre-retirement income for average earners, leaving a critical gap that savings must fill. Cultural and behavioral factors also distort the averages. For instance, retirees in Japan often live with family, reducing housing costs and inflating net worth figures for those who own homes. In contrast, U.S. retirees frequently downsize or relocate to lower-cost areas, converting home equity into liquid assets. Even lifestyle choices play a role: retirees who prioritize travel or hobbies may deplete savings faster than those who focus on frugality. The "average" retiree, therefore, is less a real person and more a statistical artifact—one that masks the diversity of retirement experiences.The Mechanics
The mechanics of retirement wealth accumulation are simple in theory but complex in practice. Compound interest, tax-advantaged accounts, and consistent contributions over decades are the engines driving net worth. Yet real-world factors—career interruptions, healthcare costs, and inflation—derail even the most disciplined plans. Consider the impact of the 2008 financial crisis: retirees who entered the market in the late 1990s saw their 401(k)s recover, but those who retired in the early 2000s faced severe drawdowns. The answer to what is the average net worth of retirees in 2024 reflects not just current savings but the cumulative effect of economic shocks over 30+ years. Another critical variable is healthcare. In the U.S., retirees spend an average of $6,000 annually on out-of-pocket medical expenses, a figure that rises sharply for those with chronic conditions. Medicare doesn’t cover everything, and long-term care costs can erode savings rapidly. Internationally, countries with universal healthcare (e.g., Germany, Australia) see retirees allocate less of their net worth to medical reserves, freeing up capital for other uses. The bottom line? The "average" retiree’s net worth is less about how much they saved and more about how well they’ve hedged against the biggest financial risks of later life.Details That Change the Picture
The data on what is the average net worth of retirees becomes meaningless without accounting for debt. Many retirees carry mortgages, credit card balances, or student loans into their golden years. A 2022 study found that 20% of retirees aged 65–74 had outstanding student debt, often from children’s education. Even medical debt can linger, with one in five retirees reporting collections accounts on their credit reports. When debt is subtracted from net worth, the picture for lower-income retirees turns stark: what appears as a modest $200,000 in assets may be just $50,000 in spendable wealth after obligations. Geographic disparities further muddy the waters. Retirees in states with high taxes (e.g., California, New Jersey) or expensive housing markets (e.g., Hawaii, Massachusetts) require significantly higher net worths to maintain their lifestyle. Conversely, retirees in states with no income tax (e.g., Texas, Florida) may stretch savings further—but face trade-offs like weaker public services or higher healthcare costs. The "average" retiree in Florida might have a higher net worth on paper than one in Minnesota, yet the Minnesotan could live more comfortably due to lower cost of living. These nuances explain why raw net worth figures are often misleading."The median net worth of retirees is a red herring. What matters isn’t how much you have, but how you structure your income streams to survive the unknowns—market crashes, healthcare inflation, and longevity risks. The retirees who thrive aren’t always the ones with the highest balances." —Dr. Teresa Ghilarducci, Director of the Schwartz Center for Economic Policy Analysis
| Factor | Impact on Net Worth Perception |
|---|---|
| Homeownership status | Owners appear wealthier due to equity, but renters may have higher liquid savings. |
| Public pension access | Countries with strong pensions (e.g., Denmark) show lower reliance on personal savings. |
| Debt burden | Retirees with mortgages or student loans may have negative net worth despite high asset values. |
| Healthcare costs | U.S. retirees spend ~15% of net worth on medical expenses; international peers spend far less. |

Conclusion
The question what is the average net worth of retirees is less about finding a single number and more about recognizing that retirement wealth is a mosaic of personal history, policy, and luck. The averages hide more than they reveal: the retiree who inherited a home, the one who worked in a unionized job with a pension, and the one who retired early only to face a decade of poor market returns. What’s clear is that the traditional metrics—median net worth, 4% withdrawal rules—no longer suffice in an era of rising costs and prolonged lifespans. For individuals, the takeaway is straightforward: net worth alone is a poor predictor of retirement security. A better measure is liquidity—how much cash and easily convertible assets you have—and income stability—whether Social Security, pensions, or part-time work can cover essentials. The retirees who weather downturns aren’t always the richest; they’re often the most adaptable. Policymakers, meanwhile, must confront the reality that retirement security is no longer an individual problem but a collective one, requiring reforms to pensions, healthcare, and wealth-building opportunities for future generations.Comprehensive FAQs
Q: Does home equity count toward retirement net worth?
Yes, but it’s not liquid. Federal Reserve data includes home equity in net worth calculations, which inflates the "average" for retirees who own their homes. However, tapping equity (e.g., reverse mortgages) can deplete other assets or create debt. For true financial flexibility, retirees often need a mix of home equity, savings, and income streams.
Q: How does inflation affect the net worth of retirees?
Inflation erodes purchasing power, especially for retirees living on fixed incomes. Since 2000, healthcare costs have risen over 150%, outpacing general inflation. Retirees who relied on static savings plans may find their net worth shrinking in real terms, even if nominal balances grow. Strategies like annuities or inflation-linked bonds can mitigate this risk.
Q: Are retirees in Europe or Asia wealthier than those in the U.S.?
Not necessarily in terms of personal savings, but differently structured. In Sweden or Germany, retirees depend more on public pensions and universal healthcare, reducing the need for large personal net worths. In Japan, where savings rates are high but returns are low, many retirees have modest net worths but live frugally. The U.S. system, with its reliance on 401(k)s, creates wider disparities but offers more flexibility for those who’ve saved aggressively.
Q: Can retirees with low net worth still retire comfortably?
Yes, but it requires careful planning. Retirees with low net worth often rely on Social Security, part-time work, or government assistance (e.g., Medicaid). Downsizing, relocating to low-cost areas, and minimizing debt can stretch limited resources. The key is aligning expenses with income streams—something the "average" net worth figures rarely capture.
Q: How do market crashes impact retirees’ net worth?
Market downturns hit retirees hardest when they’re forced to sell assets at low prices (e.g., during the 2008 crisis). Those with longer time horizons recover, but retirees in their early 60s may face permanent losses if they need to withdraw funds. Strategies like delaying Social Security benefits or using fixed-income assets first can reduce exposure to market volatility.
Q: Is the average net worth of retirees increasing or decreasing?
It depends on the cohort. For Baby Boomers, net worth has generally risen due to home equity and decades of compounding. However, younger retirees (Gen X, Millennials) face headwinds: stagnant wages, student debt, and housing unaffordability. Long-term trends suggest that without systemic changes, the "average" retiree’s net worth may stagnate or decline for future generations.
