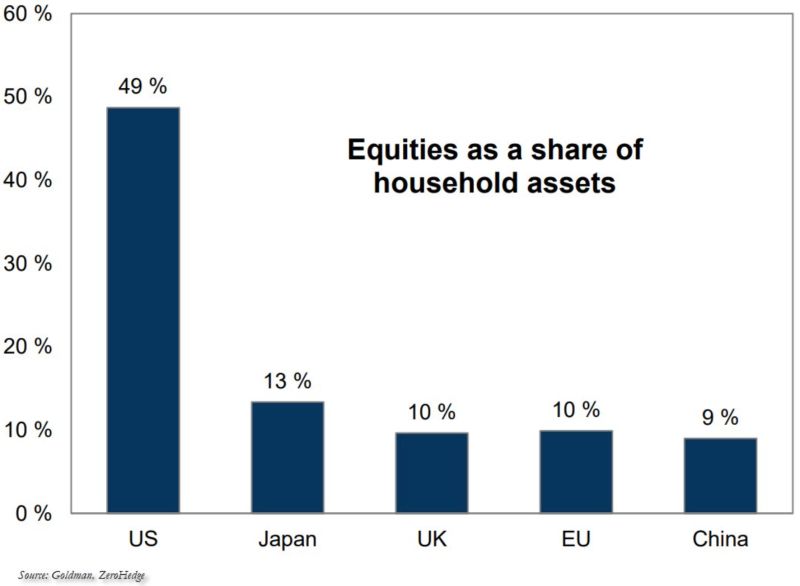
Breaking Down the Numbers
Household asset accumulation isn’t a linear process. It’s shaped by geography, culture, and life stage. In urban centers, for example, the primary asset is often property, while in rural areas, land and livestock may dominate. Even within cities, the mix varies: a young professional in Brooklyn might prioritize a down payment on a co-op, while a retiree in Florida might focus on a paid-off RV and healthcare savings. These differences aren’t just regional—they reflect deeper economic realities. The data confirms this fragmentation. Federal Reserve surveys show that the median net worth of White households is nearly 10 times that of Black households, a disparity tied not just to income but to what is considered an asset in each community. A $50,000 car in a suburban neighborhood might be seen as a liability in a low-income urban area, where public transit is reliable. The same logic applies to education: a college degree is an asset in knowledge economies, but in gig-driven fields, certifications or apprenticeships may hold more weight.The Verified Baseline
Publicly available data offers a starting point. The U.S. Census Bureau’s Survey of Income and Program Participation categorizes household assets into five broad groups: 1. Real estate (primary residence, rental properties) 2. Financial assets (retirement accounts, stocks, savings) 3. Business equity (sole proprietorships, partnerships) 4. Vehicle equity (cars, trucks, boats) 5. Other assets (furniture, jewelry, tools) What’s notable is the omission of human capital—skills, health, or social networks—that economists increasingly recognize as critical. The IRS’s Form 1040 doesn’t account for these, yet they’re often the difference between a household’s resilience and vulnerability. For instance, a plumber’s toolkit isn’t listed as an asset on tax forms, but its value in emergencies is undeniable. Even within verified categories, definitions vary. A primary residence might be an asset to a bank (collateral for a loan) but a liability to a homeowner facing rising property taxes. This duality underscores why what is a household asset depends entirely on the lens: financial, social, or survival-based.What the Estimates Suggest
Industry estimates paint a more nuanced picture. According to the Federal Reserve’s 2022 Report on the Economic Well-Being of U.S. Households, about 30% of households hold no liquid assets beyond retirement accounts. For these families, assets like a reliable car or a fully stocked pantry become lifelines. Meanwhile, wealthier households report non-financial assets—such as art collections or memberships in exclusive clubs—accounting for up to 20% of their total net worth, a figure rarely discussed in mainstream finance. Hedged estimates suggest that informal assets—those not tracked by institutions—could add 15–30% to a household’s true wealth. This includes: - Time savings (e.g., owning a food dehydrator reduces grocery costs) - Community resources (e.g., a neighbor who fixes appliances in exchange for gardening help) - Skill-based equity (e.g., a stay-at-home parent’s ability to manage a household budget) The challenge? These assets defy traditional valuation. A study by the Urban Institute found that households in the bottom 20% of the income spectrum often undervalue their assets by 40% when compared to external appraisals. The reverse is true for the top 10%: they may overestimate the liquidity of illiquid assets like collectibles.
Case Study: A Closer Look
Take the example of the Johnson family in Detroit, who own a 1978 Ford F-150 with an estimated trade-in value of $8,000. On paper, this is a liability—monthly payments, insurance, maintenance. But in their community, the truck is a multi-functional asset: - It serves as a mobile workshop (tools stored in the bed). - It’s used for side gigs (hauling furniture, delivering groceries for neighbors). - Its off-road capability means the family can access hunting grounds without relying on public transit. A bank would classify the truck as debt, but the Johnsons treat it as working capital. Their net worth isn’t just numbers in an account—it’s the flexibility the truck provides."We don’t think of the truck as an expense. It’s our business in metal form. If I lost my job tomorrow, I could still earn money moving stuff or fixing things. That’s an asset no bank will ever count." — Marcus Johnson, Detroit homeowner (paraphrased from 2023 local economic forum)
| Factor | Estimated Impact on Household Stability |
|---|---|
| Truck’s trade-in value | ~$8,000 (liquid if sold, but opportunity cost of losing mobility) |
| Monthly payments saved vs. public transit costs | Estimated $300/month net gain (after gas, insurance, and maintenance) |
| Side gig revenue (hauling, repairs) | Reportedly $1,200–$2,500/year in supplemental income |
| Access to remote work/school locations | Incalculable (reduces reliance on unreliable transit) |
| Resale value in 5 years (hedged estimate) | $5,000–$10,000 (depends on market and truck’s condition) |
What This Means Going Forward
The shift toward recognizing non-traditional assets is gaining traction. Organizations like the Corporation for Enterprise Development now advocate for "asset-building" policies that include: - Tool libraries (like those in Portland, Oregon, where households can borrow power tools for free). - Community land trusts (preserving home equity for low-income families). - Micro-savings programs tied to skill development (e.g., coding bootcamps paired with emergency funds). Policymakers are also waking up. The 2021 American Rescue Plan included provisions for asset-building accounts, though uptake remains uneven. The lesson? What is a household asset is evolving from a static definition to a dynamic, community-specific concept. Yet challenges persist. Financial institutions still prioritize collateralizable assets, leaving out millions who rely on informal wealth. The solution may lie in hybrid valuation models—combining traditional metrics with social and practical measures. For example, a home’s asset value could be calculated not just by its market price but by its energy efficiency, repair history, and community ties (e.g., proximity to family support networks).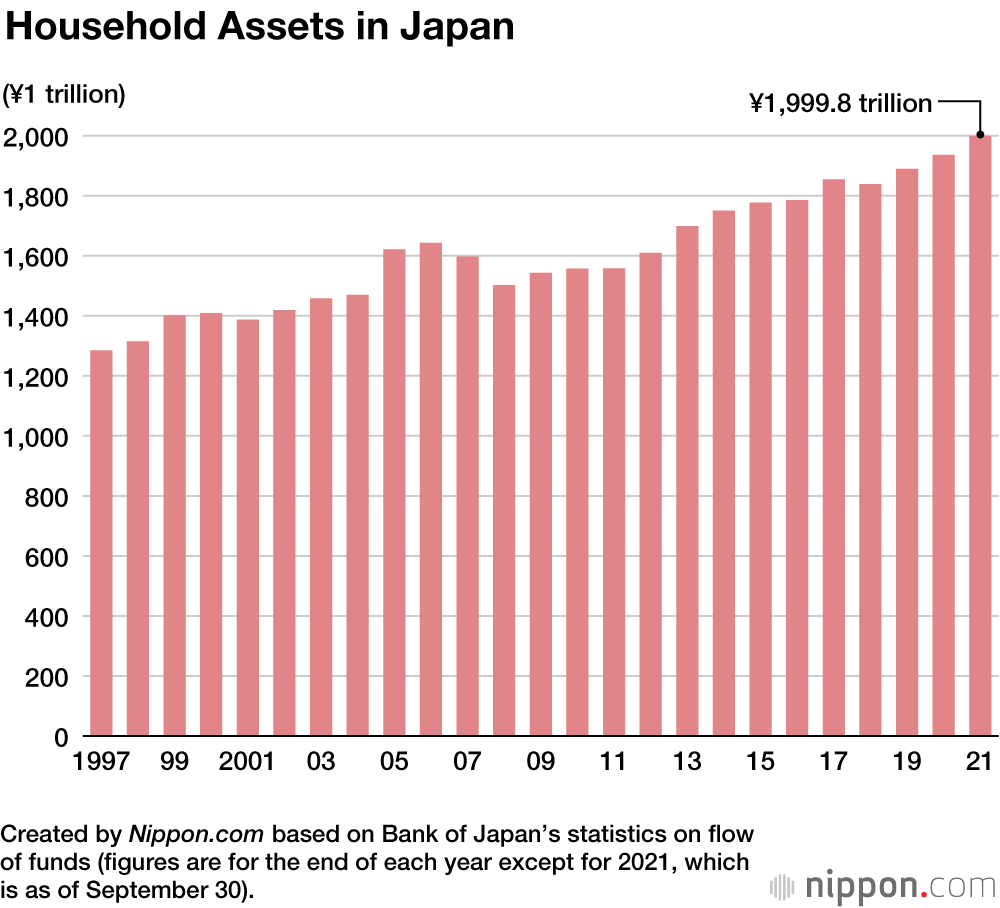
Conclusion
The question what is a household asset isn’t just about balance sheets—it’s about how families survive and thrive. The Johnsons’ truck, a Detroit tool library, or a grandparent’s gardening skills are all part of the equation, even if they don’t appear on a bank statement. Ignoring these elements distorts financial advice, exacerbates inequality, and leaves households unprepared for crises. The future of asset discussion must embrace pluralism. It should account for: - Tangible (property, vehicles, tools) - Intangible (skills, health, social capital) - Contextual (cultural, geographic, and generational factors) Until then, the conversation about wealth will remain incomplete—and so will the security of the millions who depend on assets that don’t fit neatly into a spreadsheet.Comprehensive FAQs
Q: Does a car count as a household asset?
A: Yes, but with caveats. A car with equity (paid-off or partially paid) is an asset, while one financed may be a liability. Its value depends on usage—a work van for a tradesperson is more of an asset than a luxury car for a commuter. Always compare the vehicle’s trade-in value to its monthly cost (insurance, fuel, maintenance) to assess net impact.
Q: Can skills or education be considered assets?
A: Absolutely. Economists classify human capital—skills, certifications, or even health—as assets because they generate future income. For example, a certified nursing assistant’s license increases earning potential, much like a college degree. However, these assets are illiquid (hard to monetize quickly), which is why they’re often overlooked in financial planning.
Q: How do property taxes affect what’s considered an asset?
A: Property taxes can erode asset value over time, especially in high-tax areas. A home might be worth $300,000 on paper, but if taxes eat 3–5% of its value annually, its net asset status declines. Some households mitigate this by: - Investing in energy-efficient upgrades (lowering taxable value). - Renting out space (generating income to offset costs). - Moving to lower-tax jurisdictions (a strategic but disruptive move).
Q: Are household goods (furniture, electronics) ever worth counting as assets?
A: Only in specific contexts. High-value items (e.g., antiques, collectibles) can be assets if appraised and insured. For most families, however, furniture and electronics are consumable assets—their value depreciates quickly. The exception? Multi-use items like a sewing machine (can generate income) or a generator (provides backup power during outages) may hold long-term value.
Q: How do cultural differences shape what’s considered an asset?
A: Dramatically. In collectivist cultures, assets like family land or extended kin networks are prioritized over individual savings. In individualist societies, stocks or retirement accounts dominate. For example: - Latin American households often view home ownership as the ultimate asset, even if it’s mortgaged. - East Asian families may treat education savings (for children) as a higher-priority asset than a primary residence. - Indigenous communities may consider land stewardship rights as an asset, even if it’s not deed-based.
Q: Can debt ever be an asset in disguise?
A: Rarely, but in strategic cases, debt can act as a leveraged asset. Examples: - A mortgage on a rental property (if cash flow covers payments). - Student loans for a high-earning field (if future income outweighs debt). - Business loans that expand revenue streams. The key is return on investment (ROI)—debt must generate more value than it costs. Most consumer debt (credit cards, car loans for personal use) does not qualify.
Q: What’s the biggest misconception about household assets?
A: The assumption that liquidity equals security. Many households treat cash savings as the sole measure of wealth, but illiquid assets (home equity, tools, skills) often provide greater long-term stability. The 2008 crisis proved this: families with diversified, non-liquid assets recovered faster than those reliant on volatile markets. The lesson? Wealth isn’t just about what you can sell tomorrow—it’s about what sustains you in hard times.
