
Common Myths About Accredited Investor Net Worth
The most persistent misconception is that "an accredited investor has a net worth of" exactly $1 million, period. This oversimplification ignores adjustments for inflation, state-specific tax laws, and the SEC’s occasional clarifications. For instance, the $1 million figure was last updated in 1982, when $1 million bought significantly more purchasing power than it does today. Adjusted for inflation, that sum would need to be closer to $3 million in 2024 to maintain the same economic weight. Yet the SEC has resisted major revisions, leaving practitioners to debate whether the rule should be tied to inflation or median household income. Another myth is that net worth alone determines access to private markets. In reality, gatekeepers—platforms like AngelList, Republic, or traditional brokerages—often impose higher minimums for certain offerings. A startup raising capital on a crowdfunding platform might require $25,000 in investments, not just proof of net worth. This creates a two-tiered system: those who meet the legal threshold but lack the capital to participate, and those who exceed it but face additional hurdles like minimum purchase requirements.Myth 1: The $1 Million Threshold Is Set in Stone
The SEC’s $1 million net worth requirement has remained unchanged for decades, but this doesn’t mean it’s immutable. In 2019, the SEC proposed raising the threshold to $5 million, citing concerns about retail investor protection. The proposal stalled amid regulatory backlash, but it proved that the status quo isn’t sacrosanct. Meanwhile, some states, like California, have introduced legislation to adjust thresholds based on local cost of living—though none have succeeded yet. What’s often overlooked is that the SEC’s definition isn’t just about raw numbers. It’s about economic capacity. A $1 million net worth in Wyoming might grant access to oil and gas private placements, while the same sum in Manhattan could struggle to meet the entry fees for a single real estate syndication. The threshold’s rigidity fails to account for regional disparities in wealth accumulation and investment opportunities.Myth 2: Income Alone Can Substitute for Net Worth
The SEC allows individuals with $200,000 in annual income (or $300,000 for couples) to qualify as accredited investors, even if their net worth is below $1 million. This creates a parallel pathway, but it’s not as straightforward as it seems. For one, income must be derived from active sources—salaries, bonuses, or business profits—not passive income like dividends or capital gains. A freelancer with $250,000 in annual revenue might qualify, while a retiree living off $200,000 in dividends might not. The income-based qualification also assumes stability, which isn’t always the case. A hedge fund manager with a $2 million bonus one year could lose 80% of their portfolio the next, leaving them technically ineligible despite their historical earning power. This volatility means that net worth remains the more reliable metric for sustained access to private markets, where offerings often require long-term commitments.Myth 3: Accredited Investor Status Is Universal
The term "an accredited investor has a net worth of" is often used interchangeably across jurisdictions, but the definition varies by country. In the UK, for example, the Financial Conduct Authority (FCA) uses a £100,000 net investable asset threshold (or £250,000 in assets) for high-net-worth individuals, which is roughly equivalent to $125,000–$300,000 depending on exchange rates. Meanwhile, in Australia, the $2.5 million net worth rule for sophisticated investors dwarfs the U.S. standard. These differences highlight that the U.S. definition is an outlier, not a global norm. Even within the U.S., the term isn’t monolithic. The North American Securities Administrators Association (NASAA) has pushed for state-level harmonization, but inconsistencies persist. Some states, like Texas, have adopted the SEC’s definition wholesale, while others impose additional layers of scrutiny. This patchwork approach means that what qualifies an investor in one state may not in another—a reality often ignored in financial literature.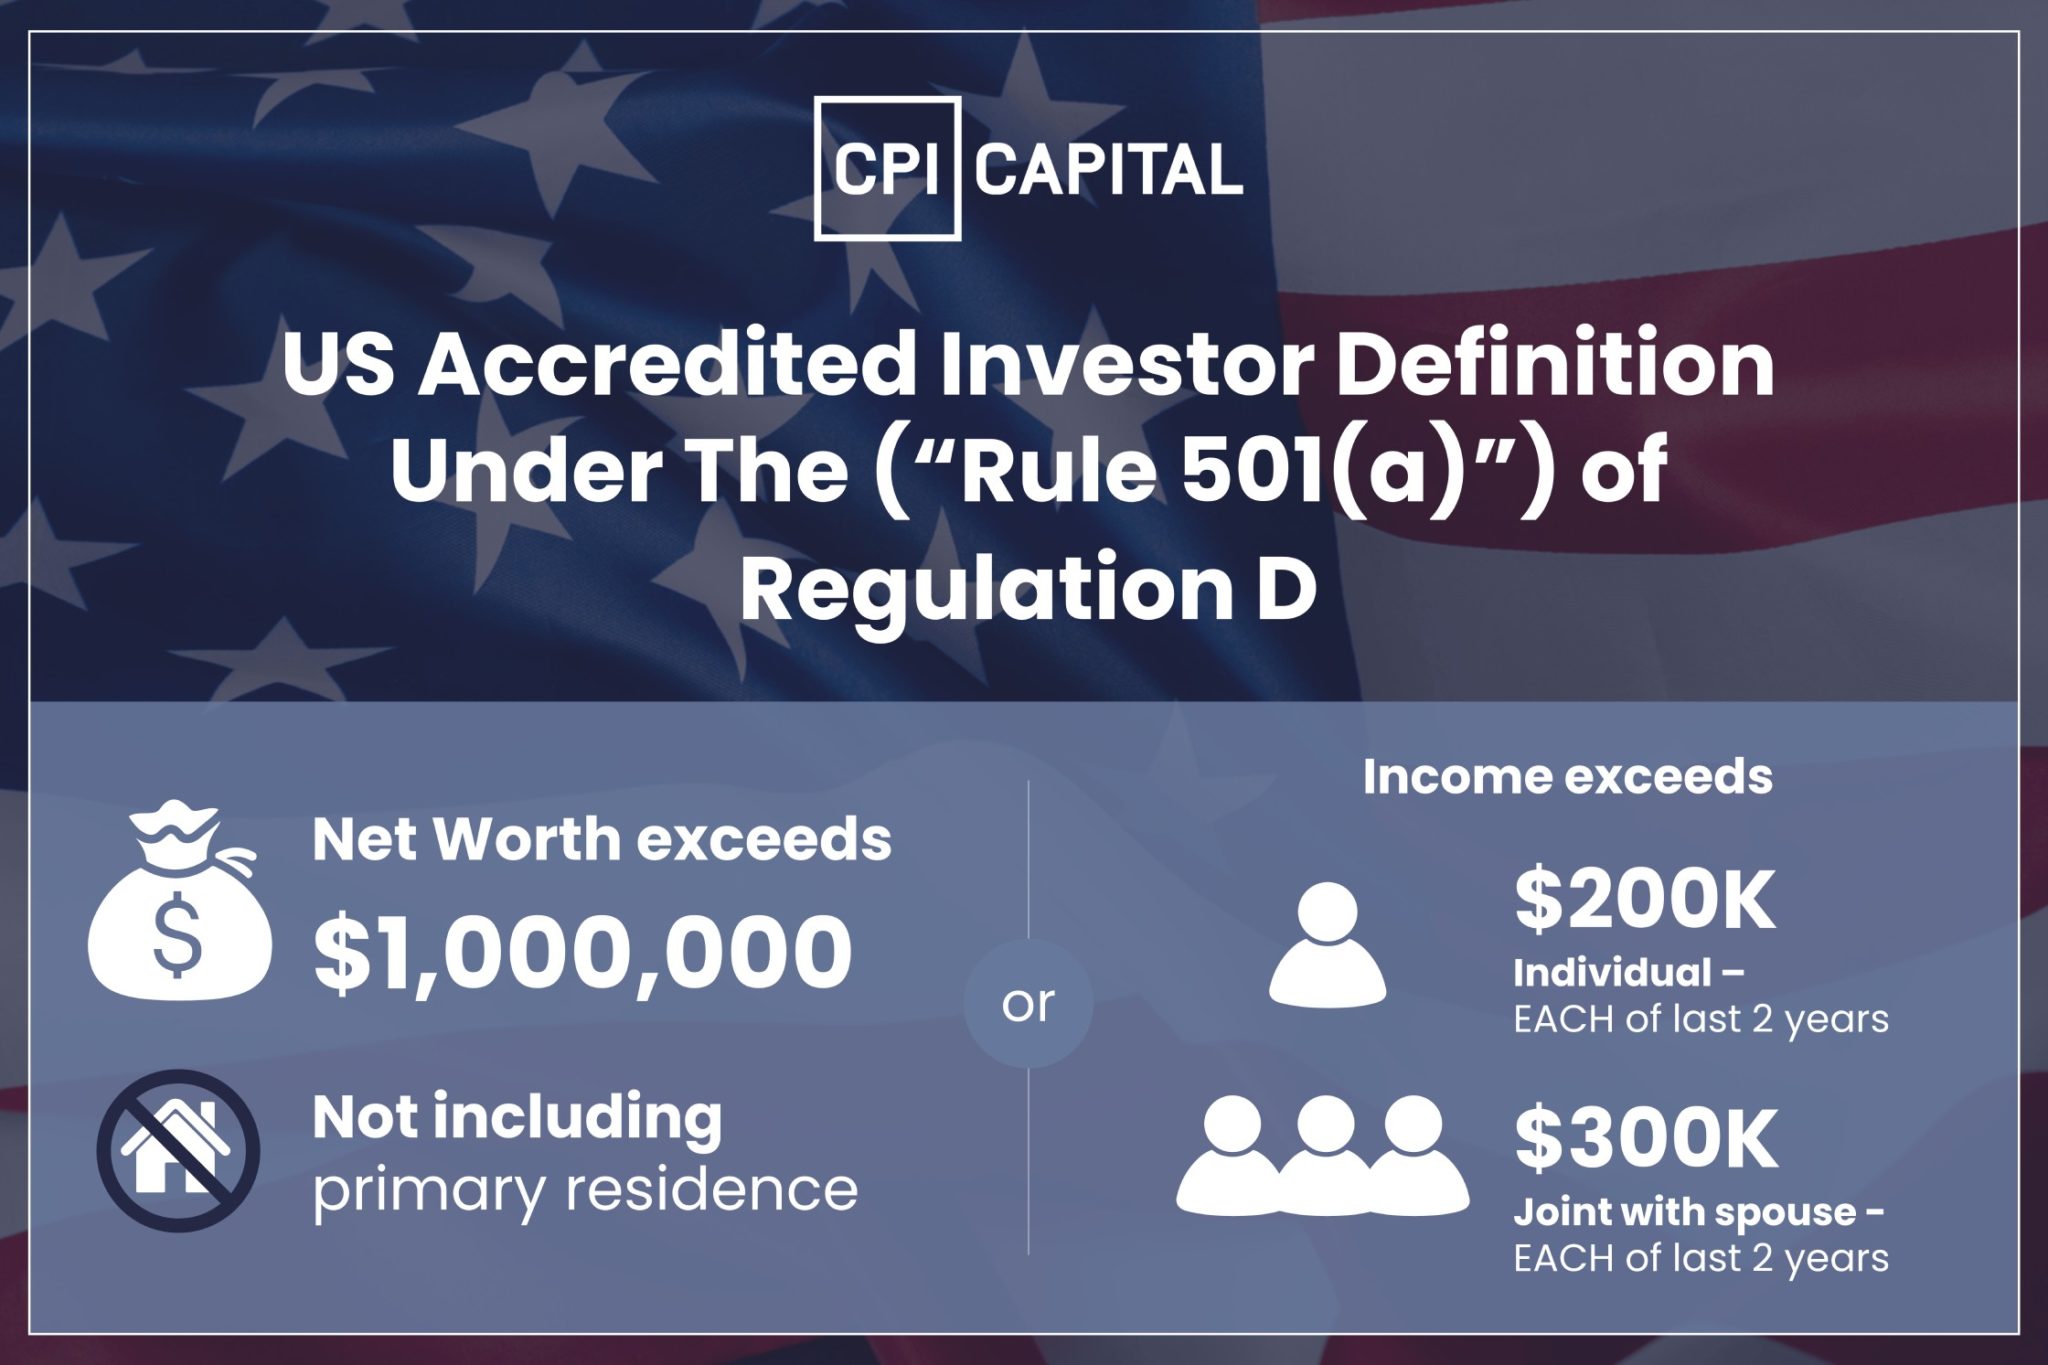
What Holds Up to Scrutiny
At its core, the accredited investor definition serves a single purpose: to protect retail investors from high-risk, illiquid assets they may not fully understand. The $1 million net worth threshold was designed to filter out those who could afford to lose the investment without significant financial harm. While the number itself may be outdated, the principle remains valid—access to certain investments should correlate with financial resilience. What’s less debated is the institutional exemption. Entities like banks, insurance companies, and investment advisers with assets over $5 million automatically qualify, regardless of individual wealth. This exemption reflects the reality that institutional investors operate on a different scale, with risk management frameworks that dwarf those of retail or individual accredited investors. The SEC’s focus here is on asset concentration rather than individual net worth, a distinction that’s rarely discussed in public forums."The accredited investor rule was never meant to be a wealth qualification—it was a risk tolerance qualification. But over time, it’s become a proxy for both, and that’s where the confusion lies." — SEC Commissioner Hester Peirce, 2021
| Common Belief | What the Evidence Says |
|---|---|
| $1 million net worth is the only path to accredited status. | Income-based qualifications ($200K+) and institutional exemptions also apply, but net worth remains the primary metric for individuals. |
| Accredited investors are always sophisticated. | The SEC’s definition is financial, not educational. A retiree with $1.2 million in bonds may qualify, but their risk profile differs vastly from a venture capitalist. |
| The threshold is globally consistent. | It varies by country (e.g., £100K in the UK, $2.5M in Australia) and even by U.S. state due to regulatory differences. |
Why the Confusion Persists
The primary reason for the confusion is regulatory inertia. The SEC updates its rules periodically, but the accredited investor definition has remained largely untouched since the 1980s. Meanwhile, the financial landscape has transformed—private equity, cryptocurrency, and real estate syndications now dominate the alternative investment space, yet the gatekeeping criteria haven’t kept pace. This disconnect creates a scenario where old rules govern new realities, leading to frustration among both investors and policymakers. Another factor is the self-reinforcing nature of the term. Financial media, advisors, and even the SEC itself often treat the $1 million figure as gospel, reinforcing the myth that it’s a fixed benchmark. When industry professionals repeat this number without context, it becomes embedded in public perception—even as the underlying economics shift. The result? A feedback loop where the definition’s rigidity is mistaken for clarity.
Conclusion
The phrase "an accredited investor has a net worth of" is less about a single number and more about a dynamic interplay of regulation, economics, and access. While the SEC’s $1 million threshold remains the legal standard, its real-world application is shaped by inflation, regional wealth disparities, and the evolving nature of private markets. The key takeaway? Net worth is just one piece of the puzzle. Income stability, investment experience, and even geographic location play equally critical roles in determining who can truly participate in accredited offerings. For policymakers, the challenge is clear: either update the definition to reflect modern economic conditions or acknowledge that the current system is a relic of a bygone era. For investors, the lesson is simpler—understanding the nuances of accredited status is as important as meeting the numerical threshold. The line between eligibility and exclusion isn’t drawn by a single dollar figure, but by a complex web of rules, opportunities, and realities.Comprehensive FAQs
Q: Can I qualify as an accredited investor if my net worth is below $1 million but my income is $200,000+?
A: Yes. The SEC allows individuals with $200,000 in annual income (or $300,000 for couples) to qualify, even if their net worth is below $1 million. However, this income must come from active sources (salary, business profits) rather than passive income like dividends. Some platforms may still require net worth verification for certain offerings.
Q: Does my primary residence count toward the $1 million net worth requirement?
A: No. The SEC explicitly excludes the value of a primary residence when calculating net worth for accredited investor status. This means if your home is worth $800,000 and your liquid assets total $300,000, you would not qualify under the net worth test.
Q: Are there any states where the accredited investor threshold is higher than $1 million?
A: Not officially. The SEC’s $1 million threshold is federal law, but some states impose additional requirements for certain investments. For example, a state might require a higher net worth for real estate syndications or oil and gas offerings, even if the federal definition is met. Always check state-specific regulations.
Q: Can a trust or family office qualify as an accredited investor if its net worth is below $1 million?
A: It depends. Institutional accredited investors (like trusts with assets over $5 million) qualify automatically, but smaller trusts or family offices may need to meet the $1 million net worth or income test for each beneficial owner. Some platforms also require the trust itself to demonstrate sophistication, even if individual beneficiaries qualify.
Q: Why hasn’t the SEC updated the $1 million threshold for inflation?
A: The SEC has considered updates, including a 2019 proposal to raise the threshold to $5 million. However, critics argue that increasing the bar could limit retail investor access to private markets while benefiting institutional players. The agency has also faced pushback from fintech firms and crowdfunding platforms that rely on the current definition to onboard investors. Until a consensus emerges, the threshold remains unchanged.
Q: Are there any non-financial perks to being an accredited investor?
A: Indirectly, yes. Accredited status often grants access to exclusive investment opportunities, such as early-stage startups, private credit funds, or real estate partnerships that are off-limits to retail investors. Some high-end networks and masterminds also restrict membership to accredited individuals, creating a social and professional tier beyond pure financial benefits.
